Since April 2026, Jack in the Box has been in a holding pattern, posting a small loss of 4.4% while floating around $12.15. The stock also fell short of the S&P 500’s 8.9% gain during that period.
Is now the time to buy Jack in the Box, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Jack in the Box Will Underperform?
We’re cautious about Jack in the Box. Here are three reasons why there are better opportunities than JACK, plus one stock we’d rather own.
1. Restaurants Are Closing, a Headwind for Revenue
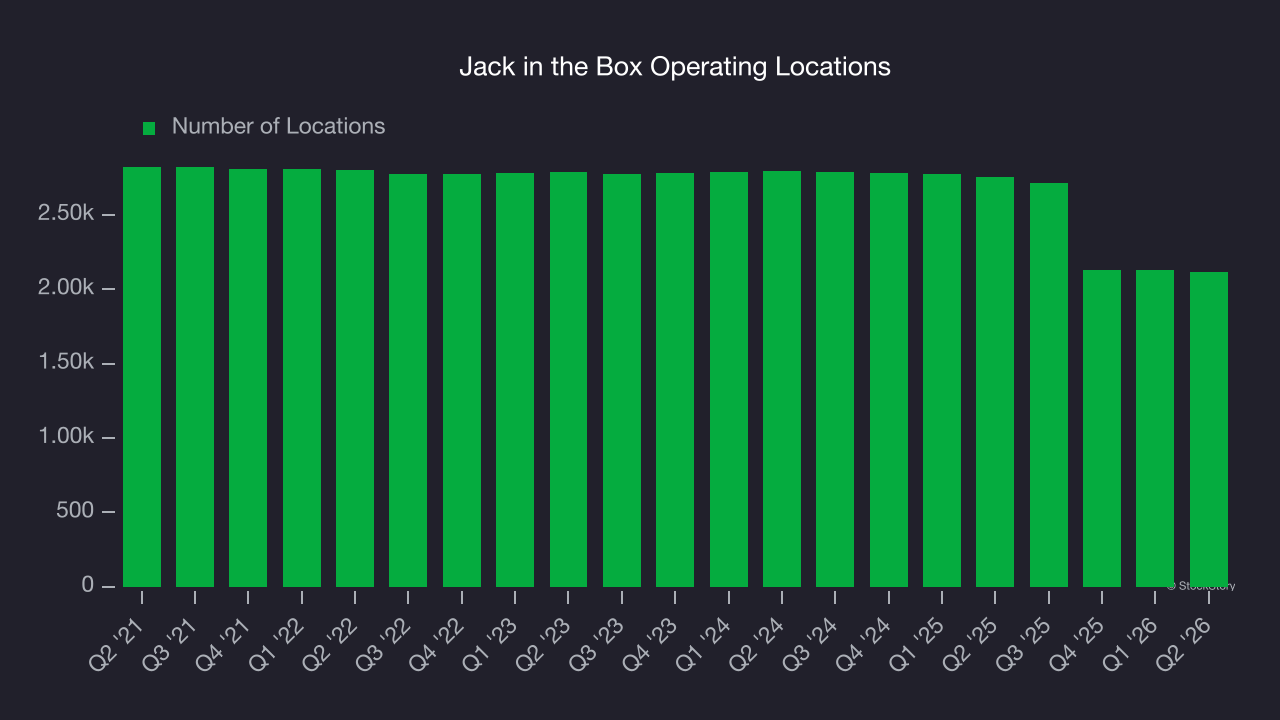
A restaurant chain’s total number of dining locations influences how much it can sell and how quickly revenue can grow.
Jack in the Box listed 2,115 locations in the latest quarter and has generally closed its restaurants over the last two years, averaging 9.3% annual declines.
When a chain shutters restaurants, it usually means demand for its meals is waning, and it is responding by closing underperforming locations to improve profitability.
2. Shrinking Same-Store Sales Indicate Waning Demand
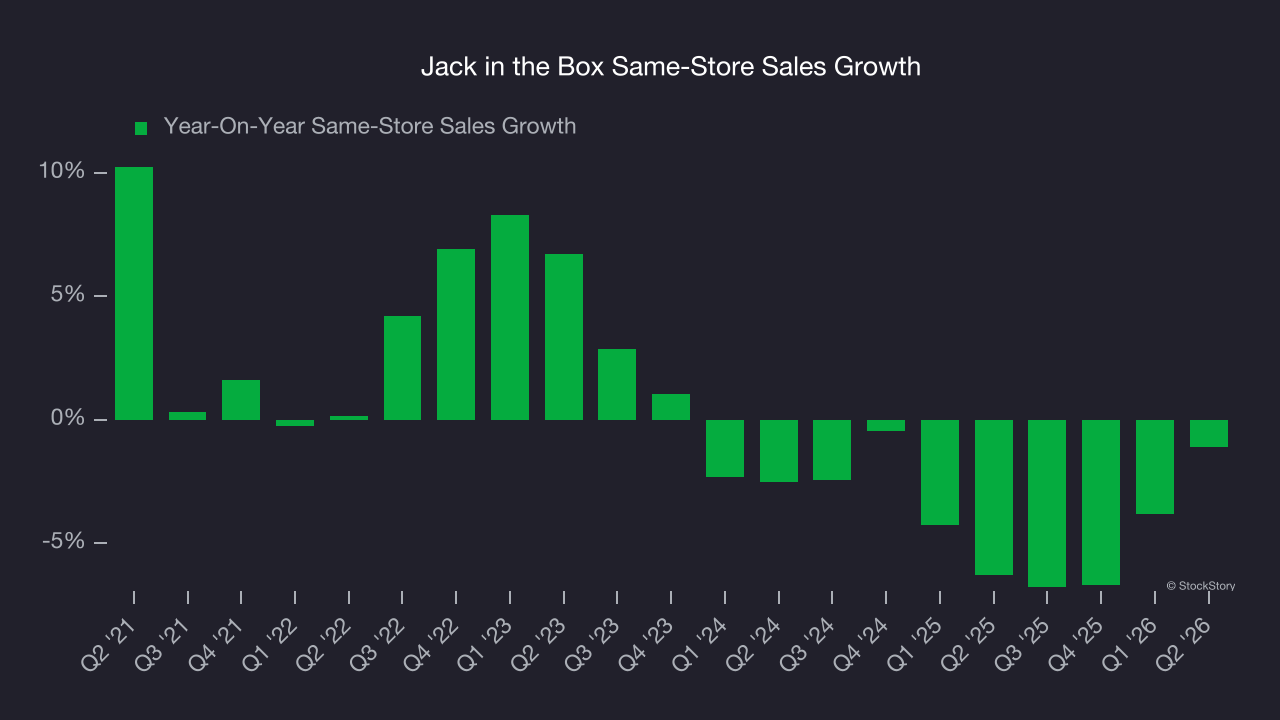
Same-store sales show the change in sales at restaurants open for at least a year. This is a key performance indicator because it measures organic growth.
Jack in the Box’s demand has been shrinking over the last two years as its same-store sales have averaged 4% annual declines.
3. High Debt Levels Increase Risk
Debt is a tool that can boost company returns but presents risks if used irresponsibly. As long-term investors, we aim to avoid companies taking excessive advantage of this instrument because it could lead to insolvency.
Jack in the Box’s $2.48 billion of debt exceeds the $46.32 million of cash on its balance sheet. Furthermore, its 11× net-debt-to-EBITDA ratio (based on its EBITDA of $226.3 million over the last 12 months) shows the company is overleveraged.
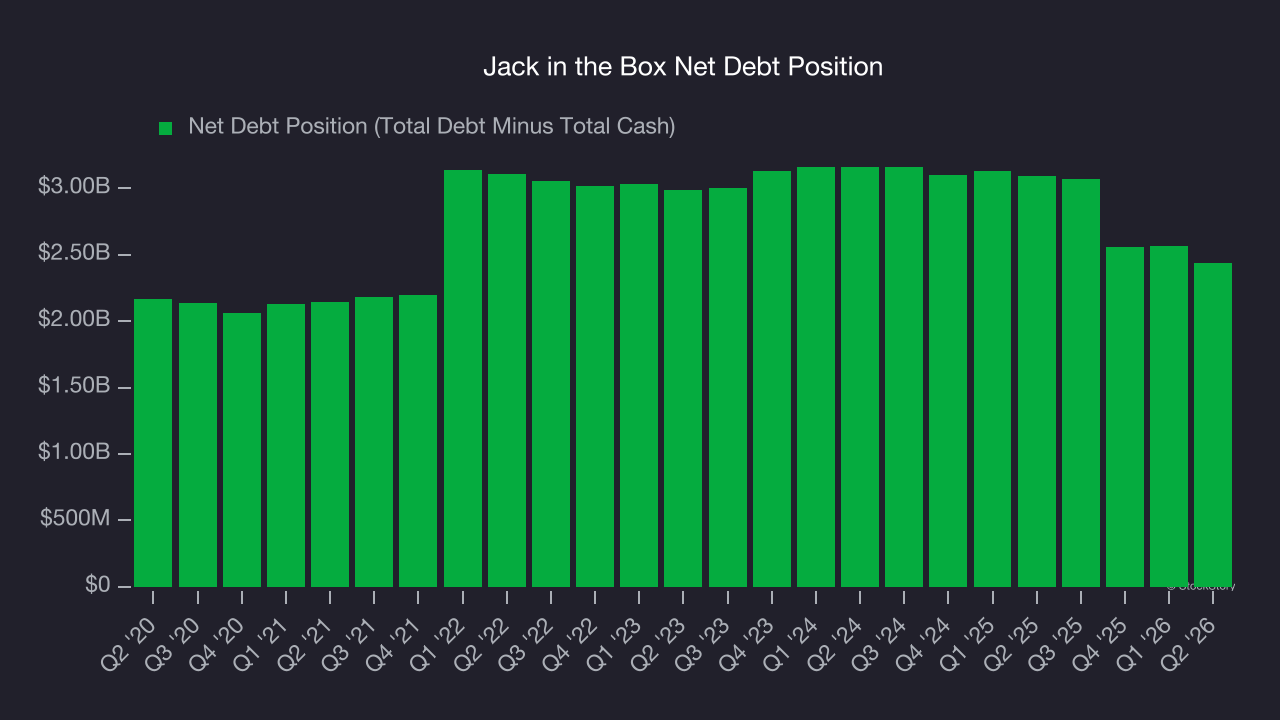
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Jack in the Box could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Jack in the Box can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
Jack in the Box falls short of our quality standards. With its shares trailing the market in recent months, the stock trades at 4.1× forward P/E (or $12.15 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. Let us point you toward a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of Jack in the Box
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.