Over the past six months, Gap’s stock price fell to $22.76. Shareholders have lost 12.2% of their capital, which is disappointing considering the S&P 500 has climbed by 8.1%. This might have investors contemplating their next move.
Is there a buying opportunity in Gap, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why is Gap not exciting?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons why there are better opportunities than GAP, plus one stock we’d rather own.
1. Stores are closing, a headwind for revenue
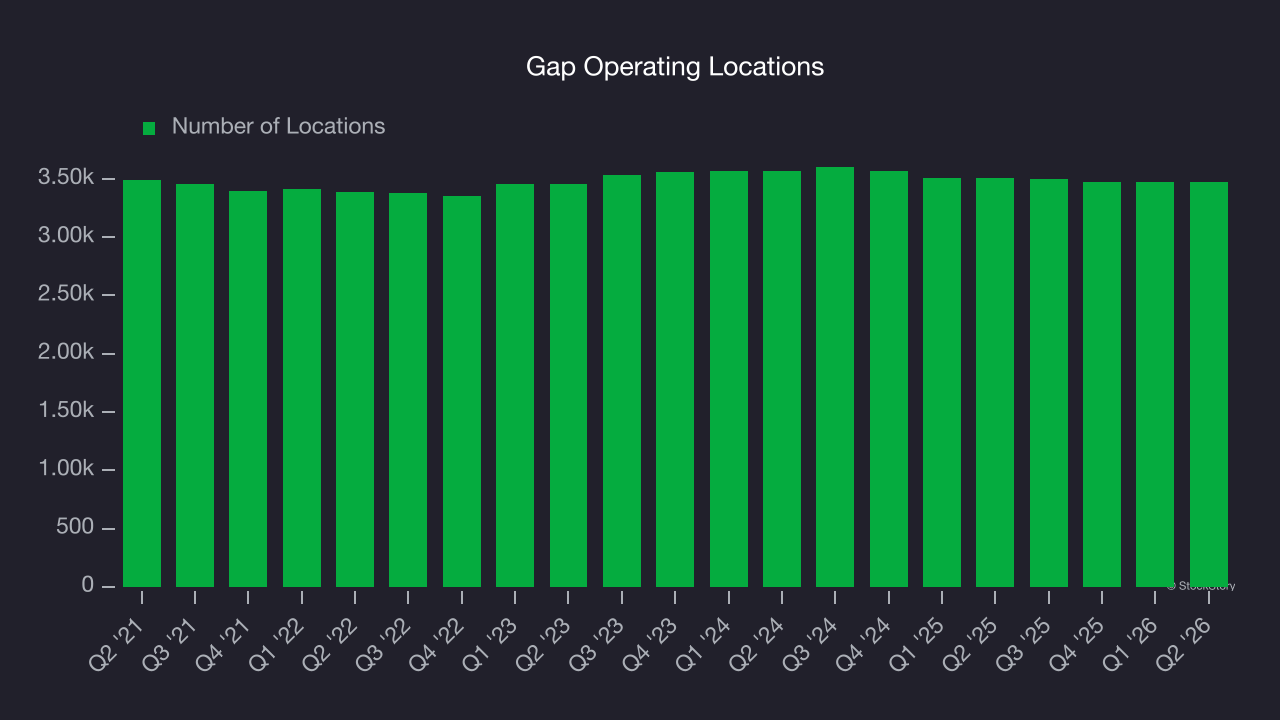
The number of stores a retailer operates is a critical driver of how quickly company-level sales can grow.
Gap operated 3,471 locations in the latest quarter. Over the last two years, the company has generally closed its stores, averaging 1.1% annual declines.
When a retailer shutters stores, it usually means that brick-and-mortar demand is less than supply, and it is responding by closing underperforming locations to improve profitability.
2. Same-store sales falling behind peers
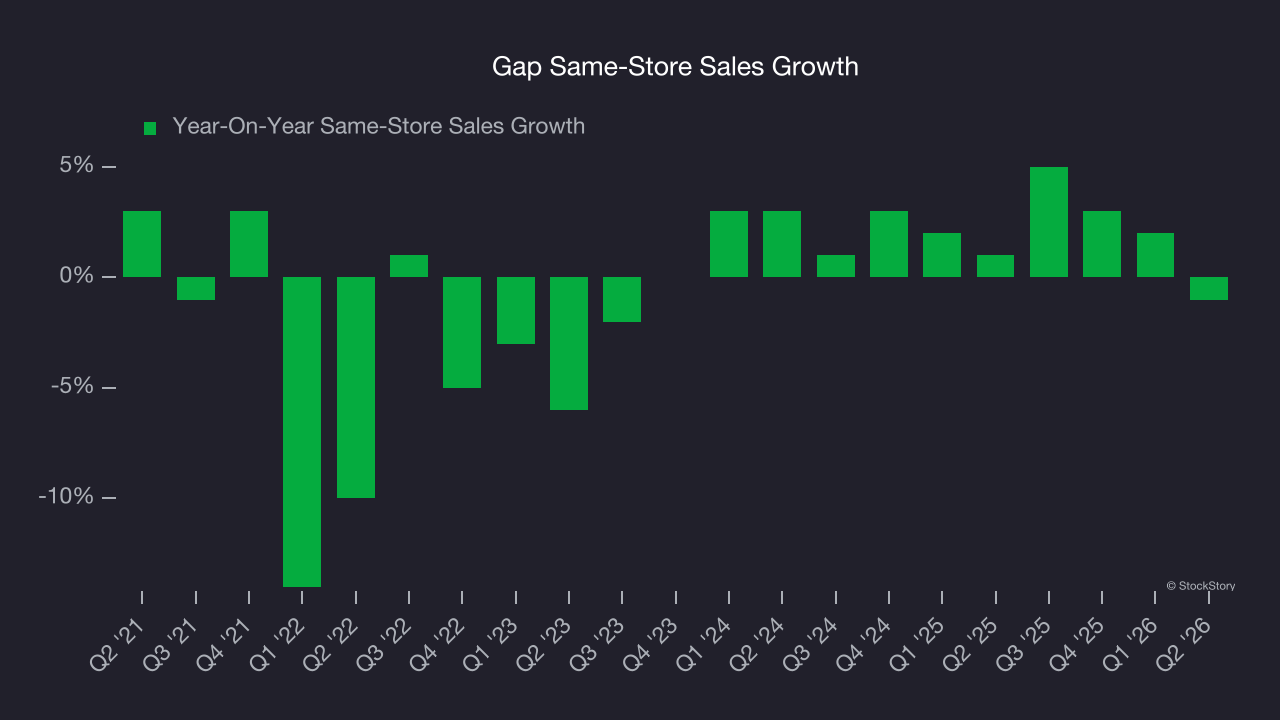
Same-store sales is a key performance indicator used to measure organic growth at brick-and-mortar shops for at least a year.
Gap’s demand within its existing locations has been relatively stable over the last two years but was below most retailers. On average, the company’s same-store sales have grown by 2% per year.
3. Previous growth initiatives haven’t impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Gap historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 9.4%, somewhat low compared to the best consumer retail companies that consistently pump out 30%+.
Final judgment
Gap’s business quality ultimately falls short of our standards. Following the recent decline, the stock trades at 9.3× forward P/E (or $22.76 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at our favorite semiconductor picks and shovels play.
High-quality stocks for all market conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.