Fluence Energy’s stock price has taken a beating over the past six months, shedding 41.9% of its value and falling to $7.56 per share. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Fluence Energy, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Fluence Energy Not Exciting?
Even though the stock has become cheaper, we don’t have much confidence in Fluence Energy. Here are three reasons we avoid FLNC, plus one stock we’d rather own.
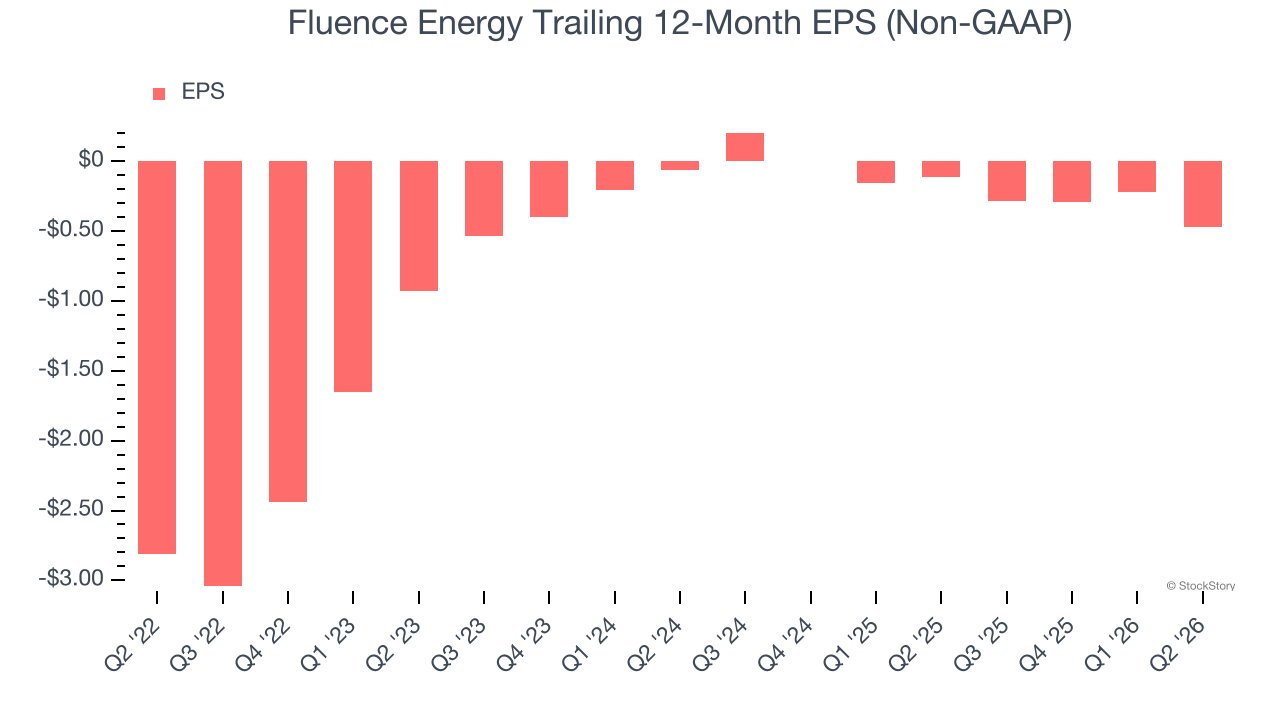
1. EPS Took a Dip Over the Last Two Years
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
For Fluence Energy, its two-year annual EPS declines of 180% mark a reversal from its (seemingly) healthy four-year trend. These shorter-term results weren’t ideal, but given it was successful in other measures of financial health, we’re hopeful Fluence Energy can return to earnings growth in the future.
2. Cash Burn Ignites Concerns
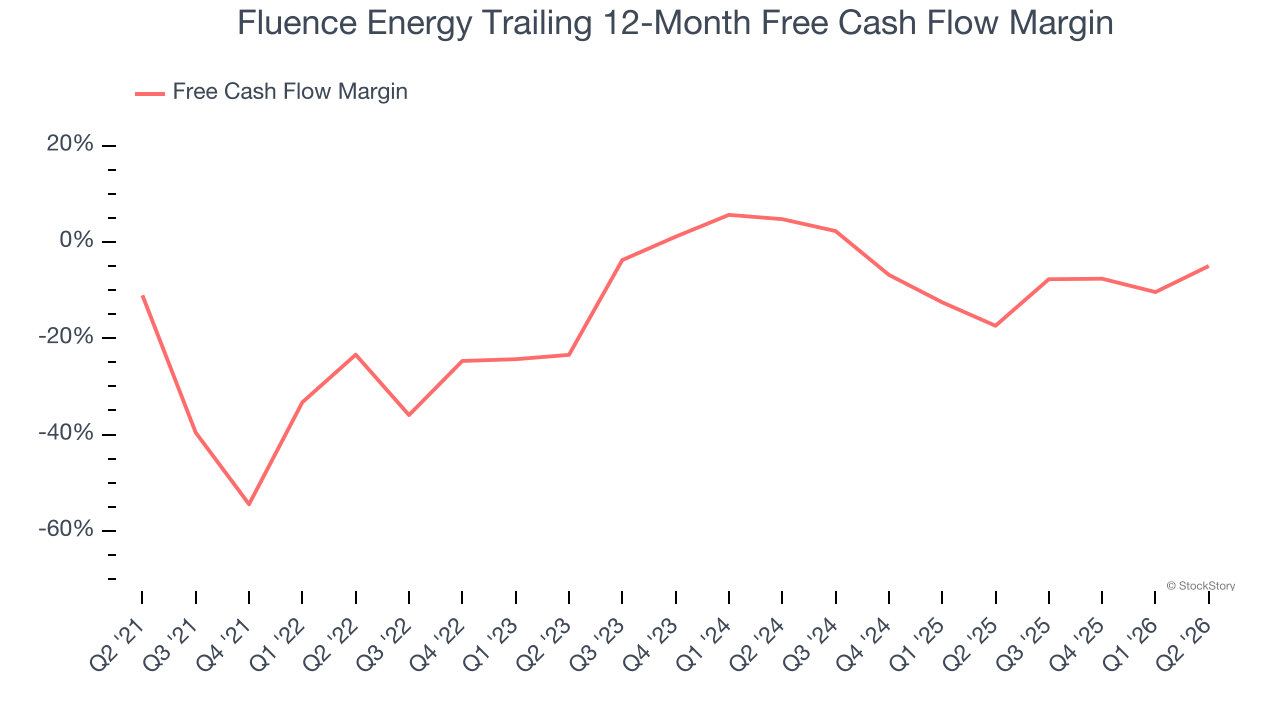
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Fluence Energy’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 11.3%, meaning it lit $11.27 of cash on fire for every $100 in revenue.
3. Restricted Access to Capital Increases Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Fluence Energy posted negative $18.61 million of EBITDA over the last 12 months, and its $400.6 million of debt exceeds the $365 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
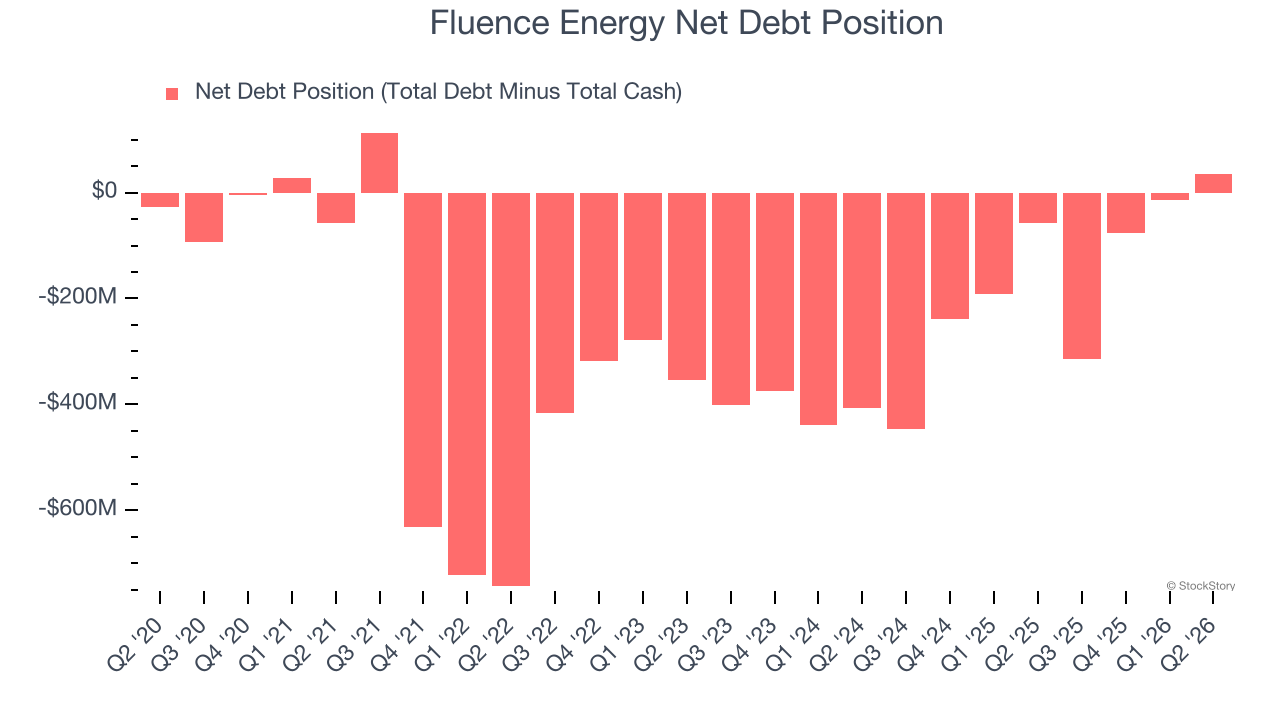
We implore our readers to tread carefully because credit agencies could downgrade Fluence Energy if its unprofitable ways continue, making incremental borrowing more expensive and restricting growth prospects. The company could also be backed into a corner if the market turns unexpectedly. We hope Fluence Energy can improve its profitability and remain cautious until then.
Final Judgment
Fluence Energy isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at $7.56 per share (or a forward price-to-sales ratio of 0.3×). The market typically values companies like Fluence Energy based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. We’d recommend looking at one of our top software and edge computing picks.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.