Over the last six months, Acushnet’s shares have sunk to $83.83, producing a disappointing 8% loss - a stark contrast to the S&P 500’s 22.1% gain. This might have investors contemplating their next move.
Is now the time to buy Acushnet, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Acushnet Will Underperform?
Even though the stock has become cheaper, we’re sitting this one out for now. Here are three reasons we avoid GOLF, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
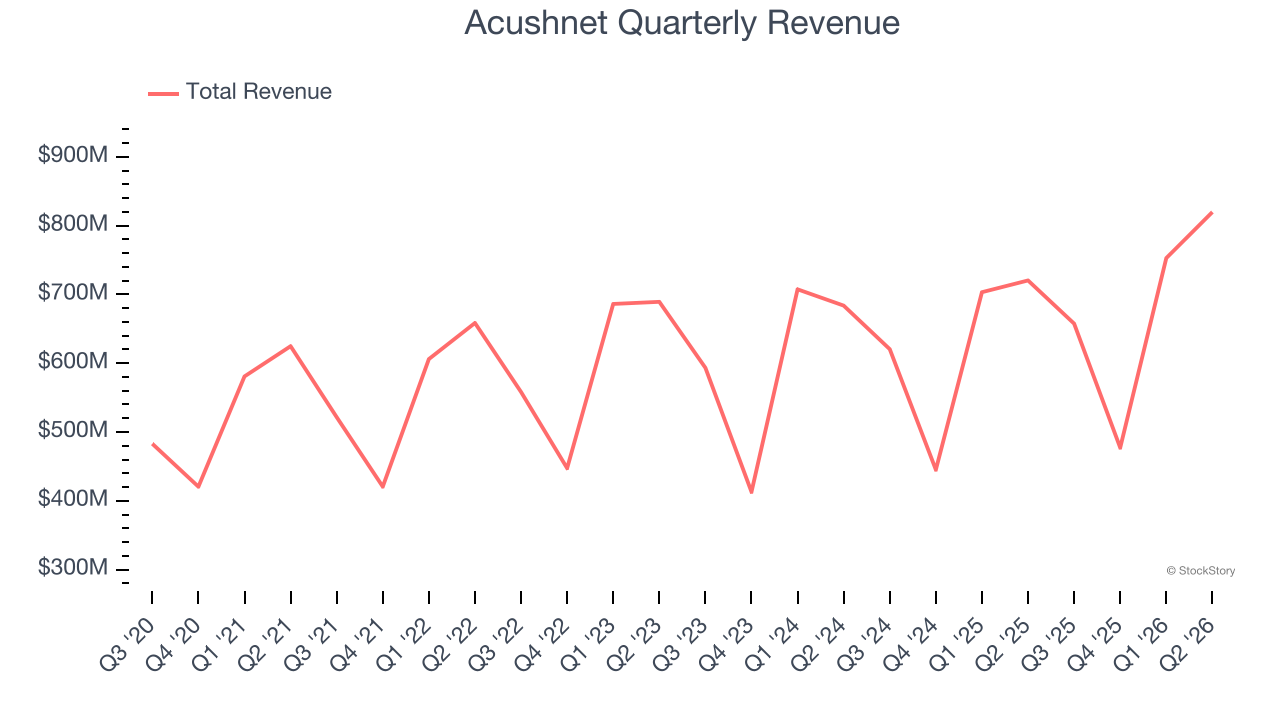
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, Acushnet’s 5.1% annualized revenue growth over the last five years was weak. This was below our standard for the consumer discretionary sector.
2. Free Cash Flow Projections Disappoint
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts’ consensus estimates show they’re expecting Acushnet’s free cash flow margin of 6.8% for the last 12 months to remain the same.
3. New Investments Aren’t Moving the Needle
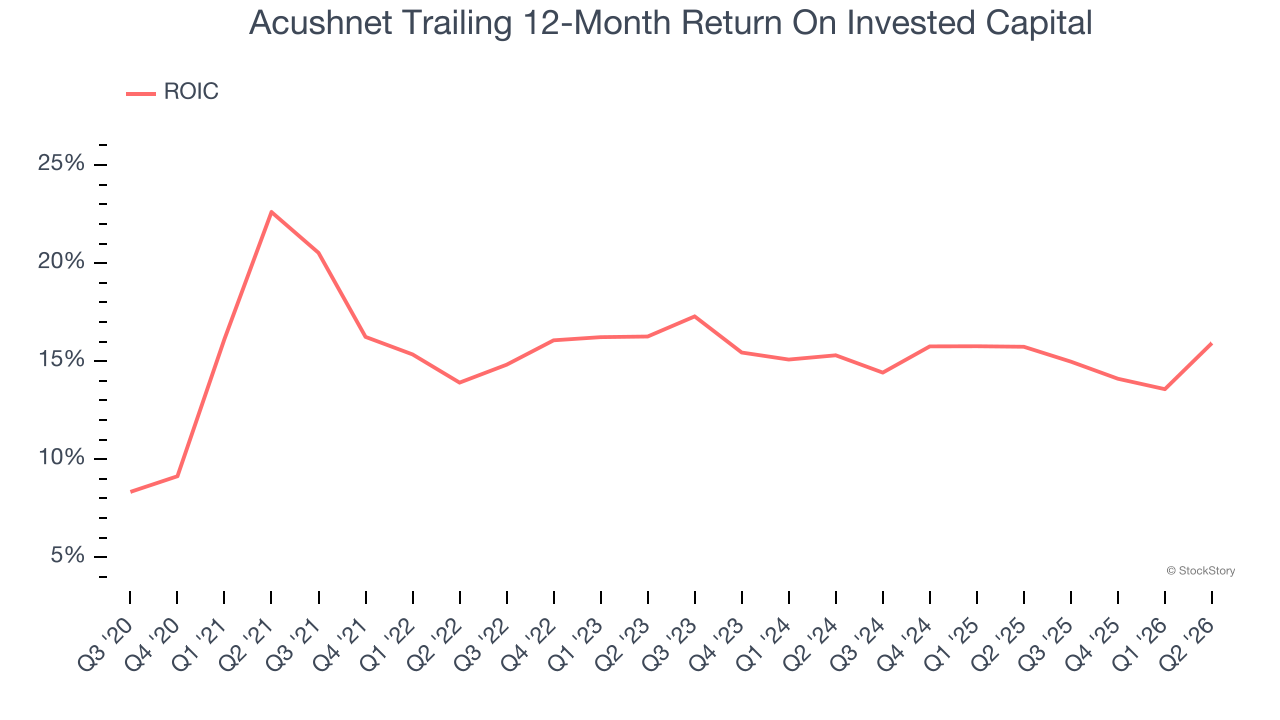
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Unfortunately, Acushnet’s ROIC has stayed the same over the last few years. If the company wants to become an investable business, it must improve its returns by generating more profitable growth.
Final Judgment
Acushnet doesn’t pass our quality test. After the recent drawdown, the stock trades at 20.3× forward P/E (or $83.83 per share). This valuation tells us a lot of optimism is priced in - we think there are better stocks to buy right now. We’d suggest looking at the most entrenched endpoint security platform on the market.
Stocks We Like More Than Acushnet
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.