Even though Home Bancshares (currently trading at $28.86 per share) has gained 9% over the last six months, it has lagged the S&P 500’s 22.1% return during that period. This might have investors contemplating their next move.
Is there a buying opportunity in Home Bancshares, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Home Bancshares Not Exciting?
We’re cautious about Home Bancshares. Here are three reasons why HOMB doesn’t excite us, plus one stock we’d rather own.
1. Net Interest Income Points to Soft Demand
Markets consistently prioritize net interest income over non-recurring fees, recognizing its superior quality compared to the more unpredictable revenue streams.
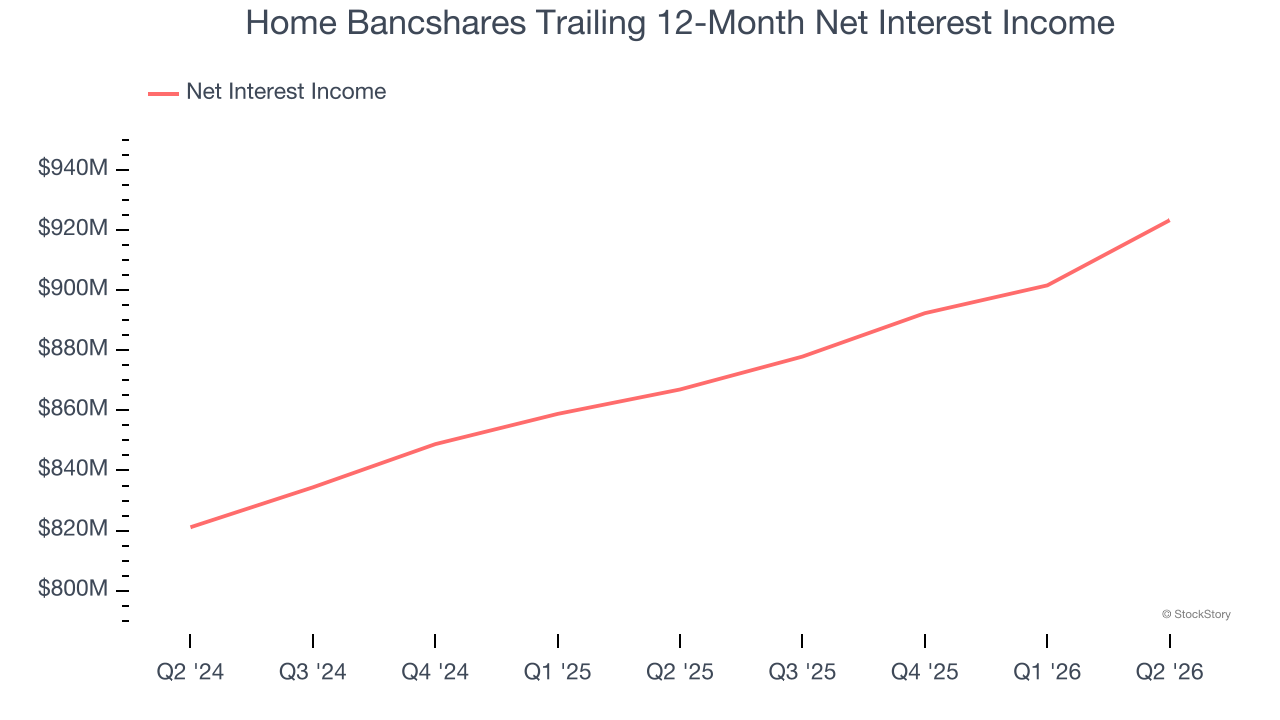
Home Bancshares’s net interest income has grown at a 9.6% annualized rate over the last five years, slightly worse than the broader banking industry and in line with its total revenue.
2. Projected Net Interest Income Growth Is Slim
Forecasted net interest income by Wall Street analysts signals a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Home Bancshares’s net interest income to rise by 5.9%, close to its 6% annualized growth for the past two years.
3. EPS Barely Growing
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
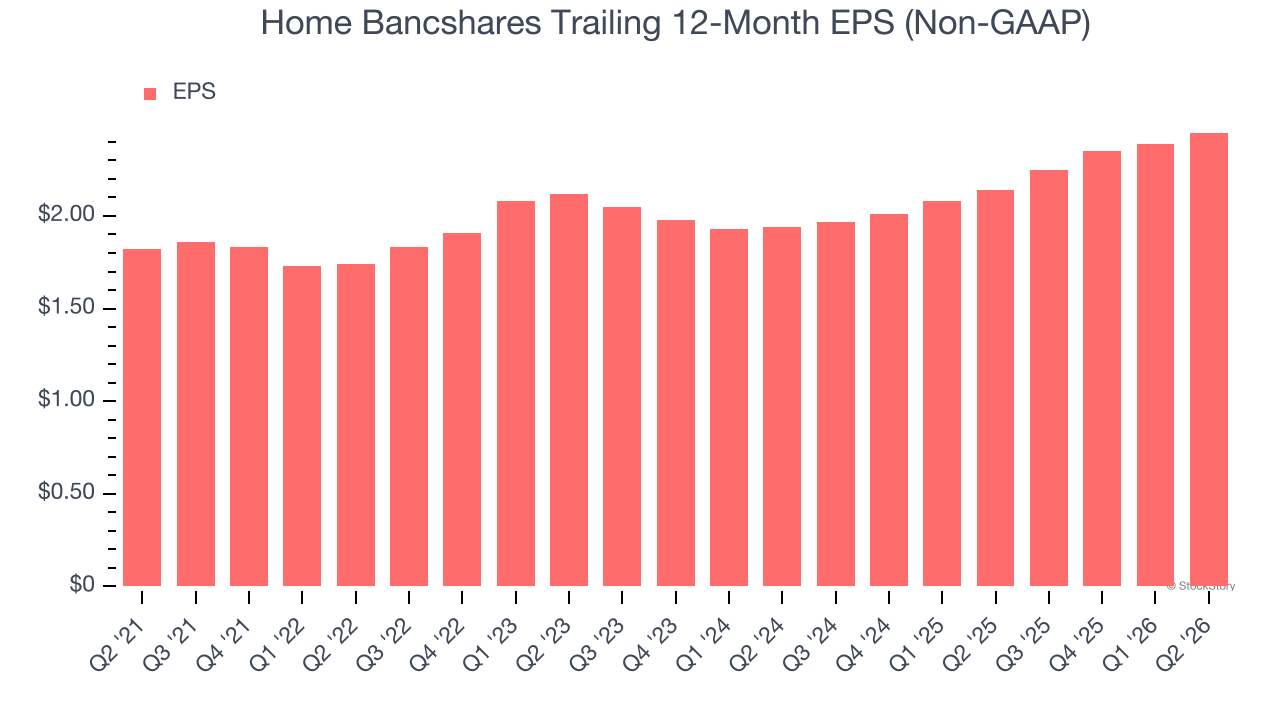
Home Bancshares’s EPS grew at a weak 6.1% compounded annual growth rate over the last five years, lower than its 9.8% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
Home Bancshares isn’t a terrible business, but it doesn’t pass our bar. With its shares lagging the market recently, the stock trades at 1.3× forward P/B (or $28.86 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better investments elsewhere. We’d recommend looking at our favorite semiconductor picks and shovels play.
Stocks We Like More Than Home Bancshares
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.