Intelligent lighting and space solutions provider Acuity Brands (NYSE: AYI) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026) as sales rose 2.9% year on year to $1.24 billion. Its non-GAAP profit of $5.77 per share was 3.8% above analysts’ consensus estimates.
Is now the time to buy Acuity Brands? Find out by accessing our full research report, it’s free.
Acuity Brands (AYI) Q3 CY2026 Highlights:
- Revenue: $1.24 billion vs analyst estimates of $1.26 billion (2.9% year-on-year growth, 1.1% miss)
- Adjusted EPS: $5.77 vs analyst estimates of $5.56 (3.8% beat)
- Adjusted EBITDA: $248.8 million vs analyst estimates of $245.1 million (20% margin, 1.5% beat)
- Operating Margin: 18.2%, up from 14.9% in the same quarter last year
- Free Cash Flow Margin: 23%, up from 14.7% in the same quarter last year
- Market Capitalization: $9.21 billion
"We demonstrated solid execution in the fourth quarter of fiscal 2026. We grew sales and expanded our adjusted operating profit and adjusted operating profit margin. We increased our adjusted diluted earnings per share, generated strong cash flow and allocated capital effectively," stated Neil Ashe, Chairman, President and Chief Executive Officer of Acuity Inc. "Throughout fiscal 2026 we strengthened Acuity Brands Lighting while continuing to scale Acuity Intelligent Spaces, building the operating and financial capacity needed to compound growth and value over time."
Company Overview
One of the pioneers of smart lights, Acuity (NYSE: AYI) designs and manufactures light fixtures and building management systems used in various industries.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Acuity Brands grew its sales at a mediocre 6% compounded annual growth rate. This wasn’t a great result compared to the rest of the industrials sector, but there are still things to like about Acuity Brands.
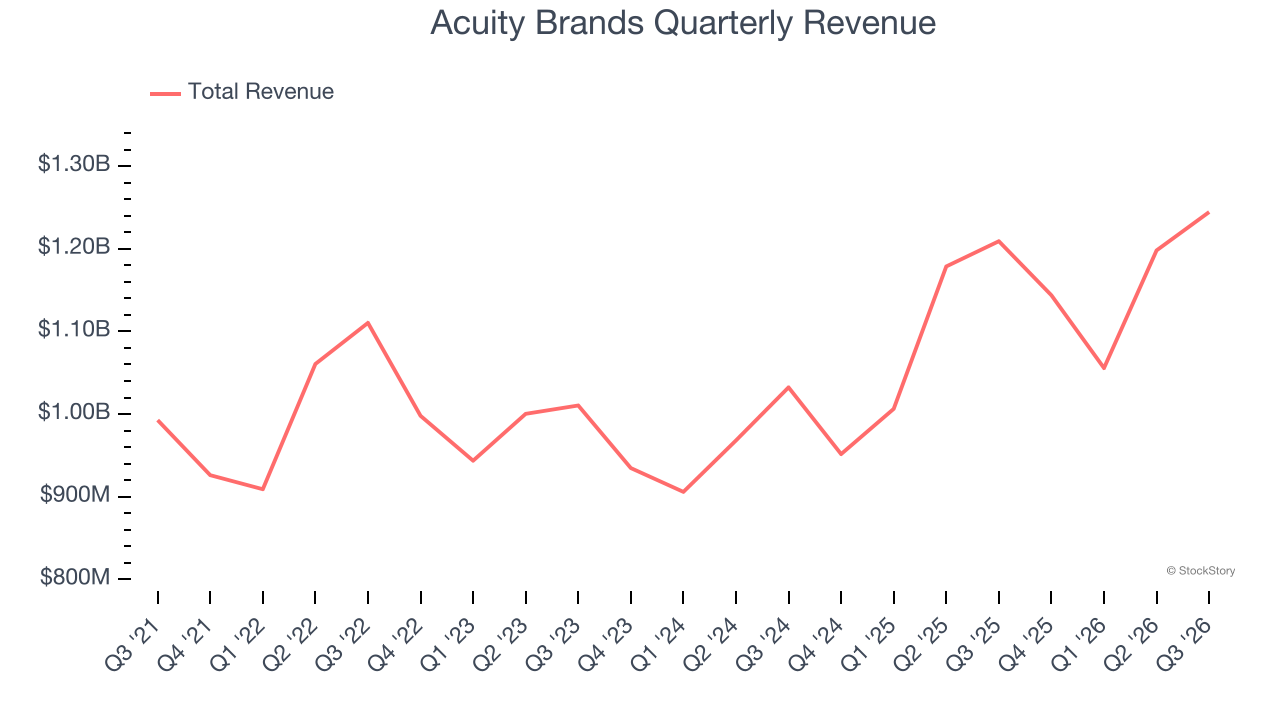
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Acuity Brands’s annualized revenue growth of 9.9% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 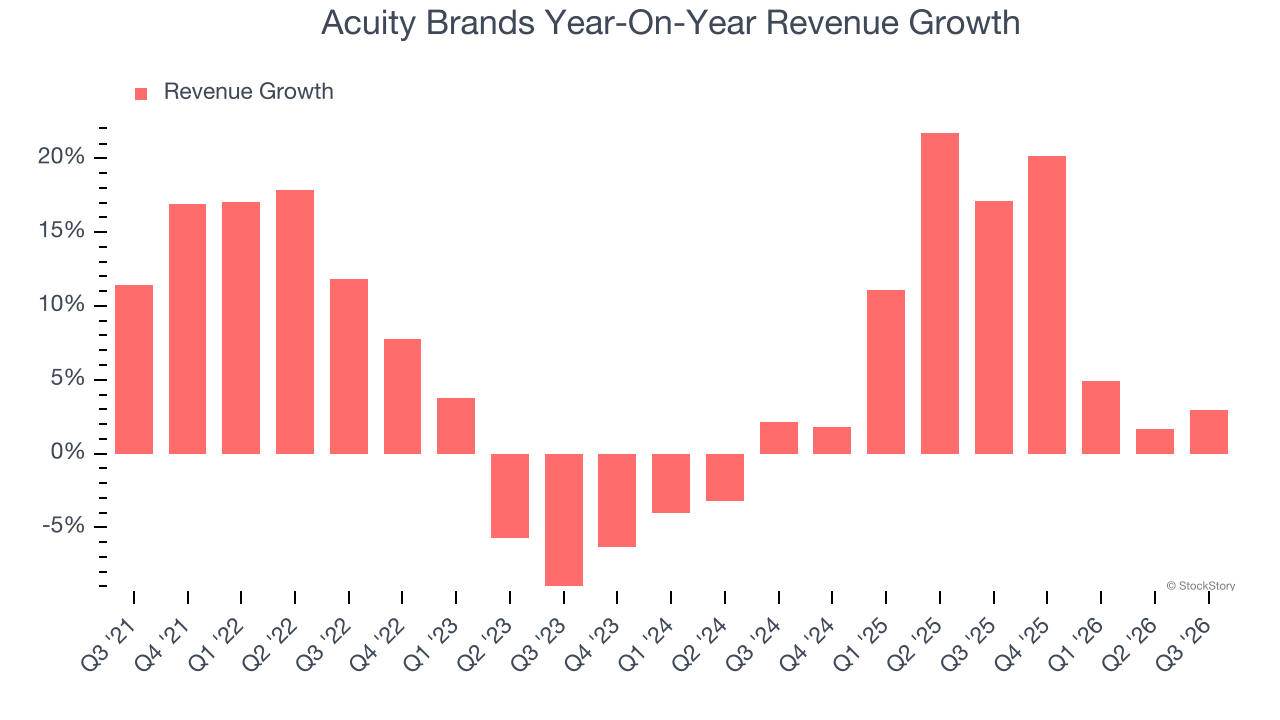
This quarter, Acuity Brands’s revenue grew by 2.9% year on year to $1.24 billion, falling short of Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 4.9% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating Margin
Acuity Brands has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, boasting an average operating margin of 13.5%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Looking at the trend in its profitability, Acuity Brands’s operating margin rose by 2.7 percentage points over the last five years, as its sales growth gave it operating leverage.
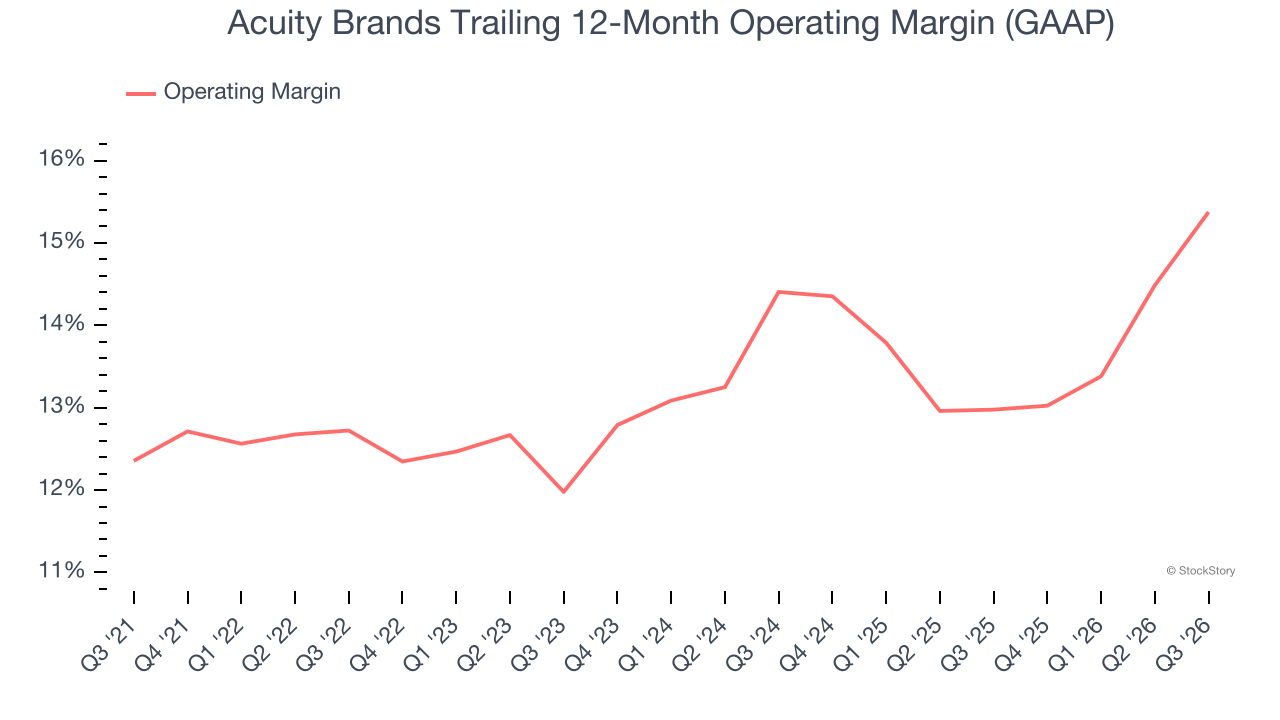
In Q3, Acuity Brands generated an operating margin profit margin of 18.2%, up 3.3 percentage points year on year. Since its gross margin expanded more than its operating margin, we can infer that leverage on its cost of sales was the primary driver behind the recently higher efficiency.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Acuity Brands’s EPS grew at 14.3% compounded annual growth rate over the last five years, higher than its 6% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
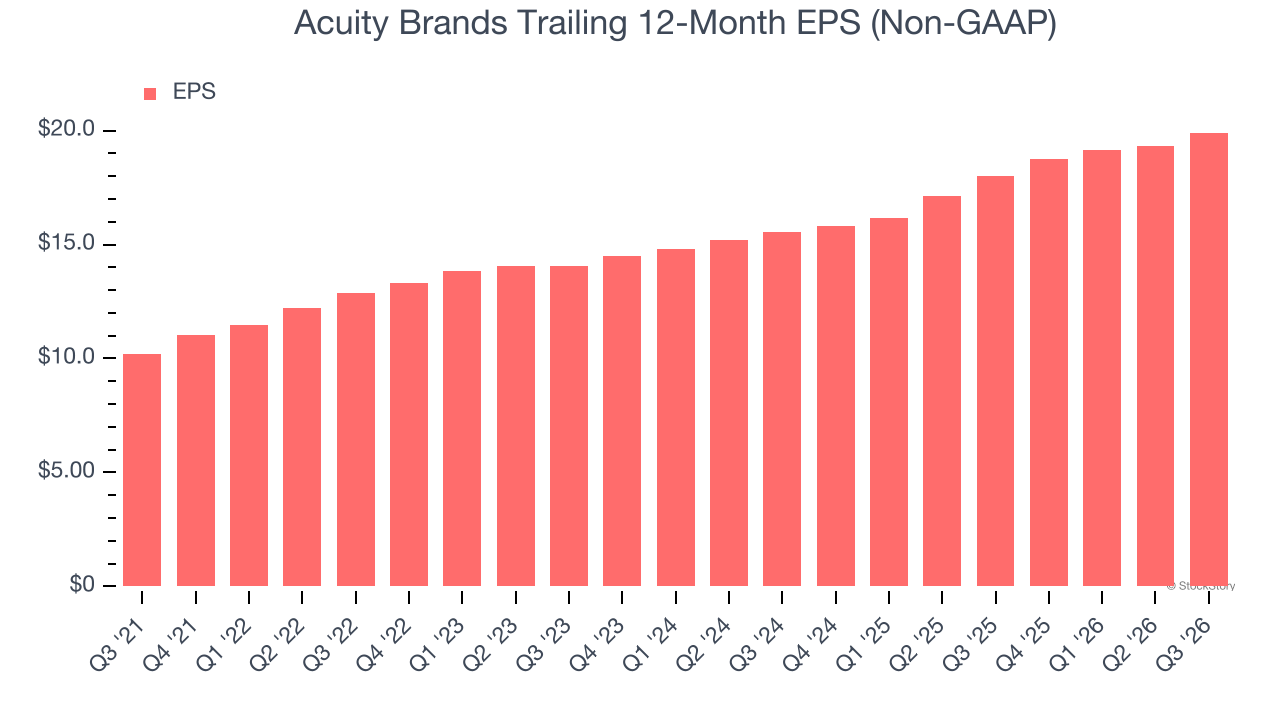
Diving into the nuances of Acuity Brands’s earnings can give us a better understanding of its performance. As we mentioned earlier, Acuity Brands’s operating margin expanded by 2.7 percentage points over the last five years. On top of that, its share count shrank by 14.6%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 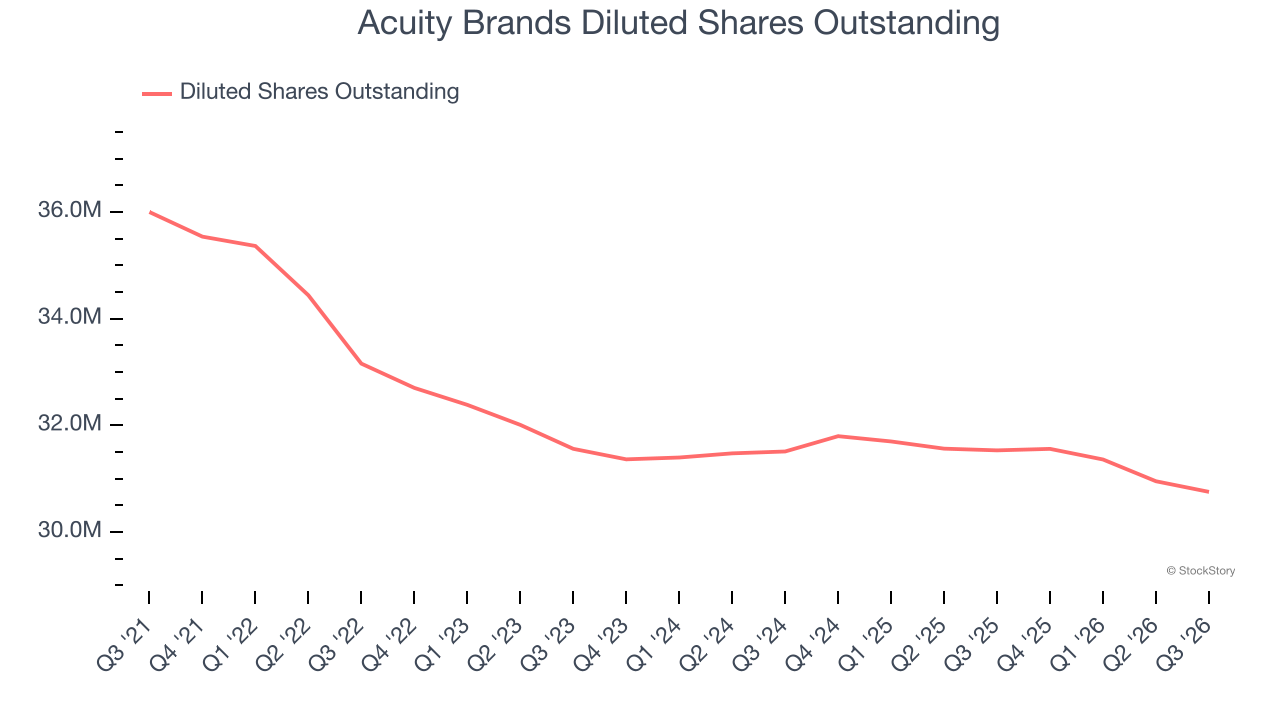
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Acuity Brands, its two-year annual EPS growth of 13.2% was lower than its five-year trend. We still think its growth was good and hope it can accelerate in the future.
In Q3, Acuity Brands reported adjusted EPS of $5.77, up from $5.20 in the same quarter last year. This print beat analysts’ estimates by 3.8%. Over the next 12 months, Wall Street expects Acuity Brands’s full-year EPS to grow 7.8% from $19.91 to $21.47.
Key Takeaways from Acuity Brands’s Q3 Results
It was encouraging to see Acuity Brands beat analysts’ EBITDA expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its revenue slightly missed. Overall, this was a mixed quarter. The stock traded down 2.1% to $303.65 immediately after reporting.
Is Acuity Brands an attractive investment opportunity at the current price? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).