Over the last six months, ADT’s shares have sunk to $6.76, producing a disappointing 7.1% loss - a stark contrast to the S&P 500’s 7.7% gain. This might have investors contemplating their next move.
Is there a buying opportunity in ADT, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think ADT Will Underperform?
Despite the more favorable entry price, we don’t have much confidence in ADT. Here are three reasons why ADT doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
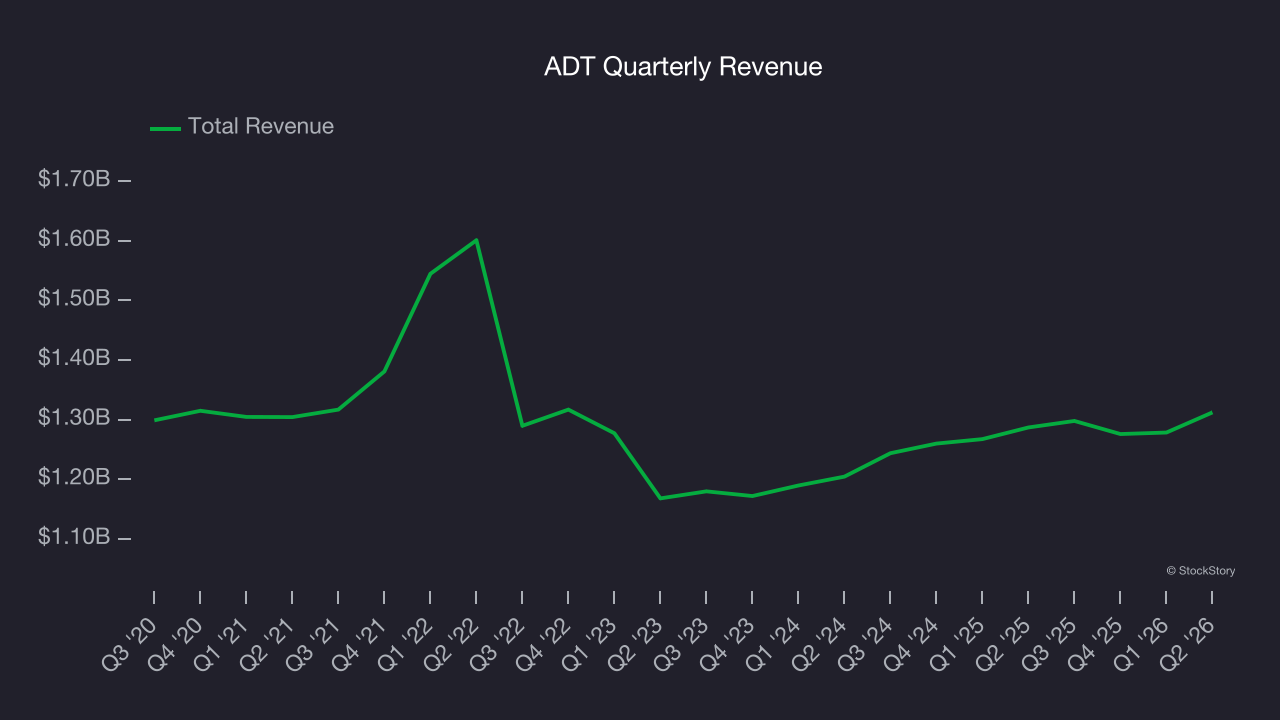
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, ADT struggled to consistently increase demand as its $5.16 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and signals it’s a low quality business.
2. Cash Flow Margin Set to Decline
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts predict ADT’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 21.8% for the last 12 months will decrease to 17.7%.
3. Previous Growth Initiatives Haven’t Impressed
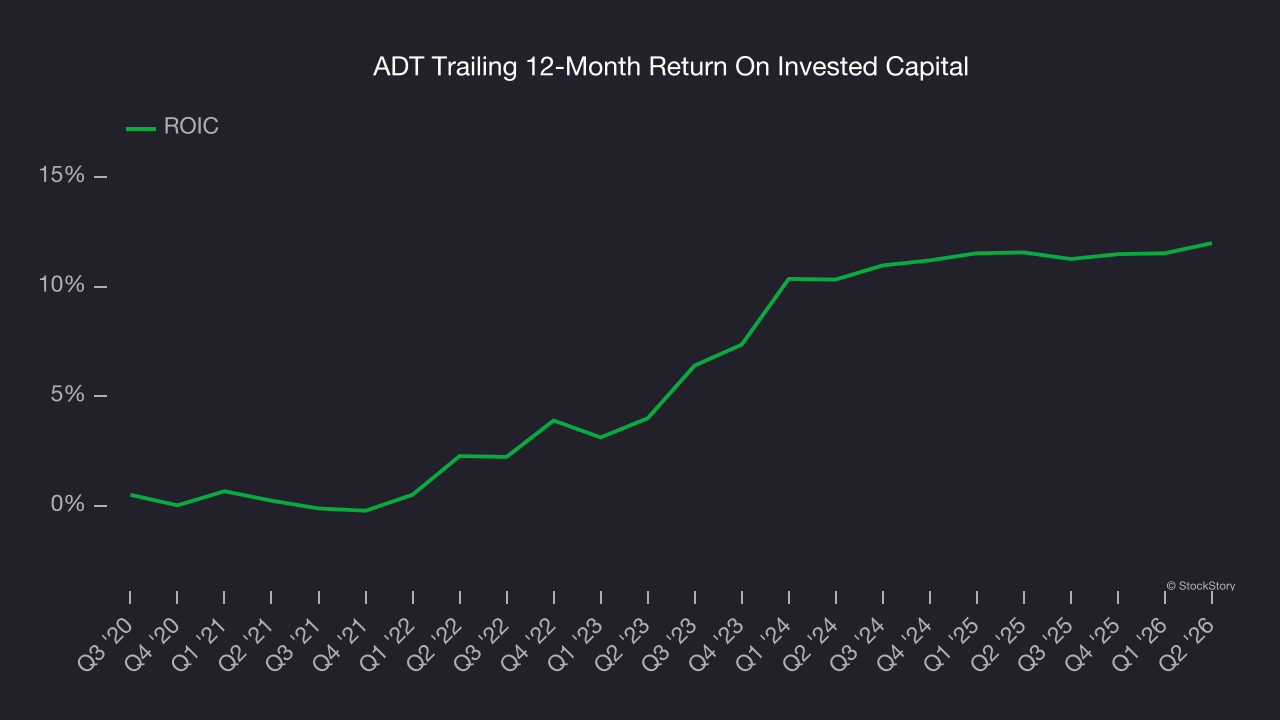
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
ADT historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 8%, somewhat low compared to the best consumer discretionary companies that consistently pump out 65%+.
Final Judgment
ADT falls short of our quality standards. After the recent drawdown, the stock trades at 7.2× forward P/E (or $6.76 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are superior stocks to buy right now. Let us point you toward one of our top software and edge computing picks.
Stocks We Like More Than ADT
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.