Electronic component provider Littelfuse (NASDAQ: LFUS) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 22.7% year on year to $766.7 million. On the other hand, next quarter’s outlook exceeded expectations with revenue guided to $760 million at the midpoint, or 4.1% above analysts’ consensus estimates. Its non-GAAP profit of $5.79 per share was 16.2% above analysts’ consensus estimates.
For more on Littelfuse, read our free full research report.
Littelfuse (LFUS) Q3 2026 highlights:
- Revenue $766.7 million vs S&P analysts’ consensus estimates of $789.9 million (22.7% year-on-year growth, 2.9% miss)
- Adjusted EPS $5.79 vs S&P analysts’ consensus estimates of $4.98 (16.2% beat)
- Adjusted EBITDA $225.9 million vs analysts’ consensus estimates of $203.9 million (29.5% margin, 10.8% beat)
- Revenue guidance $760 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $730.1 million
- Adjusted EPS guidance $5.15 at the midpoint for Q4 2026, above analysts’ consensus estimates of $4.45
- Operating margin 20%, up from 15.6% in the same quarter last year
- Free cash flow margin 28.1%, up from 21% in the same quarter last year
- Market capitalization $9.73 billion
“We delivered strong third quarter results reflecting broad-based demand strength, disciplined execution, and continued momentum across the portfolio,” said Greg Henderson, Littelfuse President and Chief Executive Officer. “Our teams drove significant growth across our segments, while delivering meaningful margin expansion and robust cash generation as we continued to advance our strategic priorities.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Littelfuse’s 7.4% annualized revenue growth over the last five years was mediocre. That was an underwhelming result compared with the rest of the industrials sector, but there are still things to like about Littelfuse.
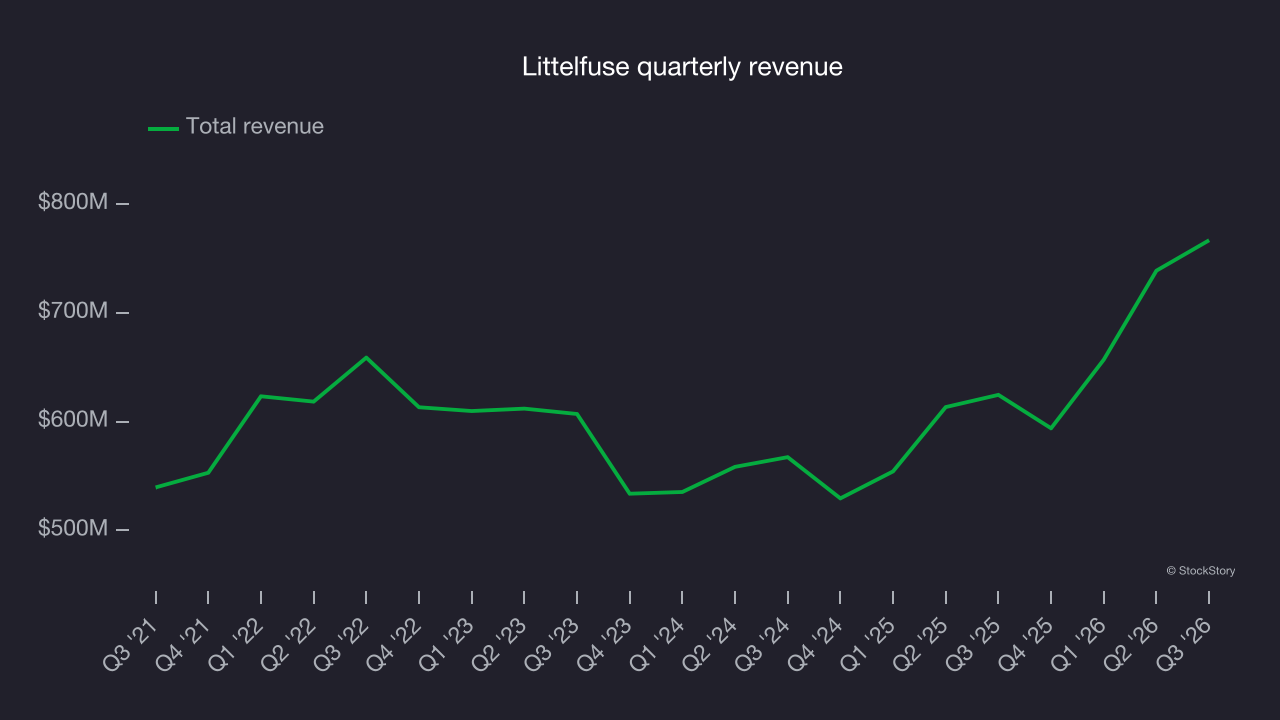
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Littelfuse’s annualized revenue growth of 12.1% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 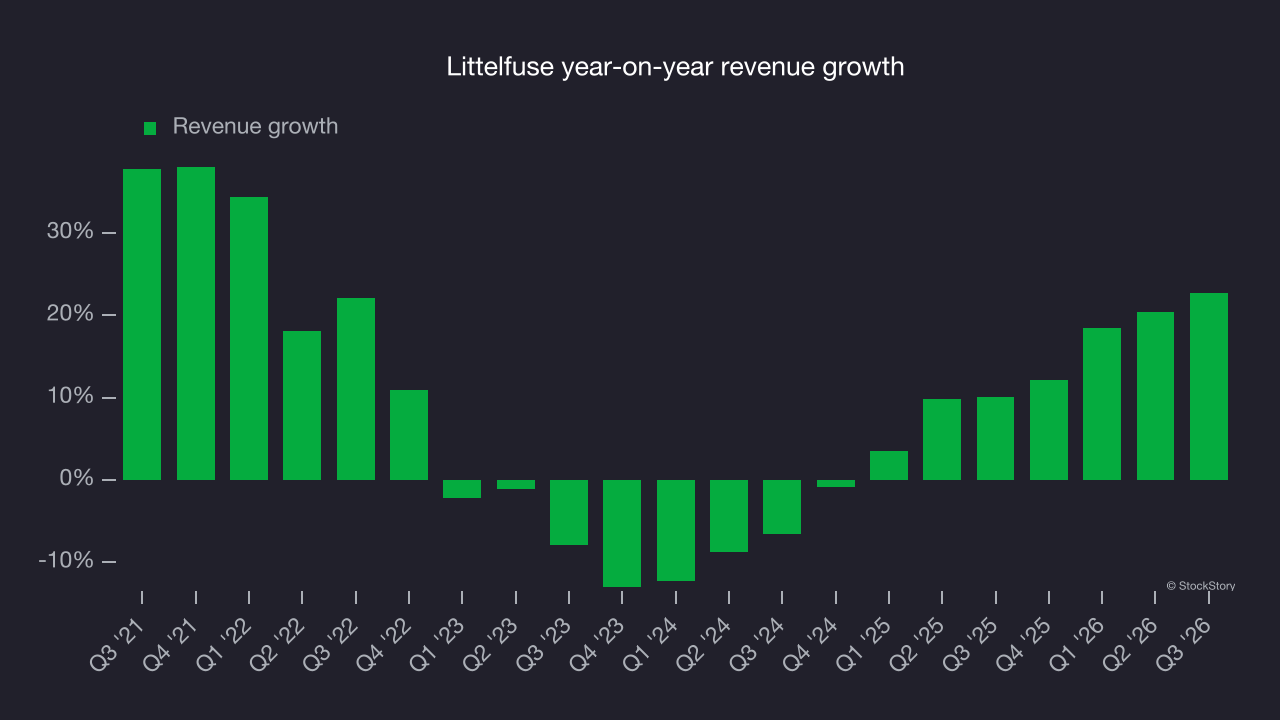
Littelfuse also breaks out the revenue for its most important segments, Electronics and Automotive, which are 55.6% and 23.8% of revenue. Over the last two years, Littelfuse’s Electronics revenue (fuses and switches) averaged 16% year-on-year growth while its Automotive revenue (trucks, commercial machinery, marine) averaged 2.3% growth. 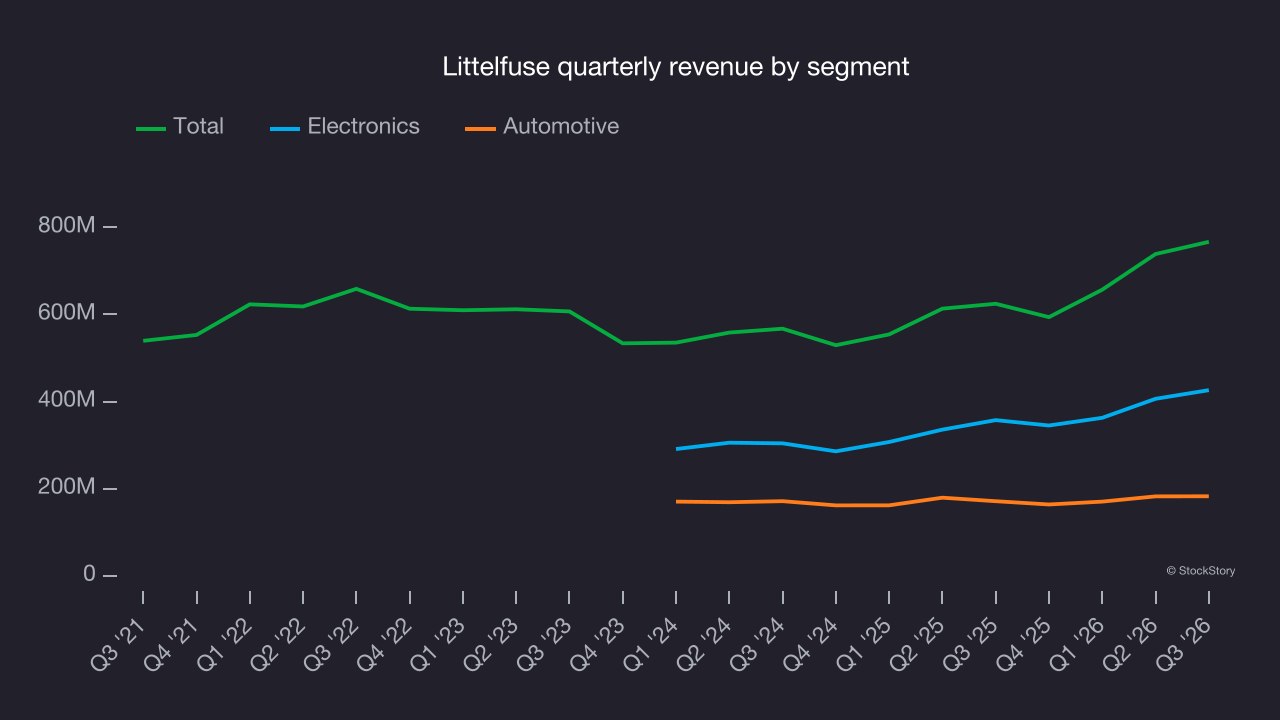
This quarter, Littelfuse generated strong year-on-year revenue growth of 22.7%, but its $766.7 million of revenue fell short of Wall Street’s high expectations. Company management is currently guiding for a 28% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 14.2% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is noteworthy and suggests its newer products and services will fuel better top-line performance.
Operating margin
Littelfuse has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 12.5%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Analyzing the trend in its profitability, Littelfuse’s operating margin decreased by 14.9 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
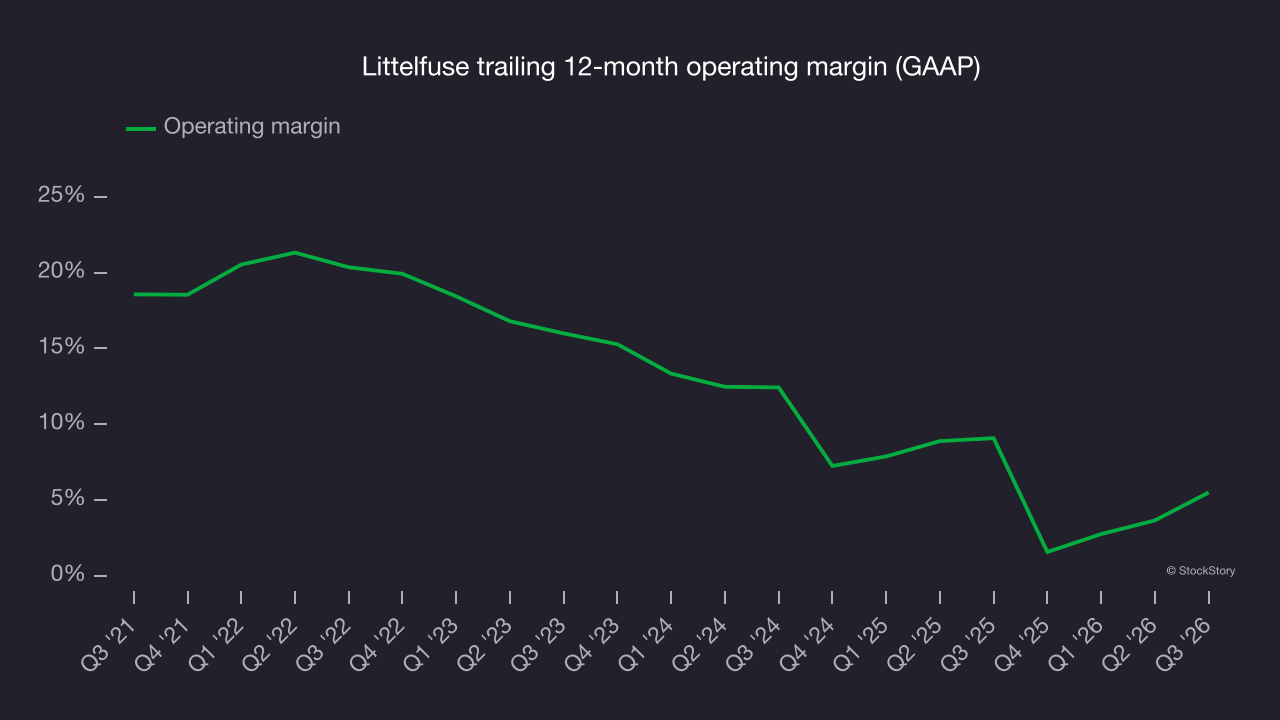
In Q3, Littelfuse generated an operating margin of 20%, up 4.4 percentage points year on year. The increase was a positive sign, and the larger rise in operating margin than in gross margin suggests it was more efficient with expenses such as marketing, R&D and administrative overhead.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Littelfuse’s unimpressive 5.4% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
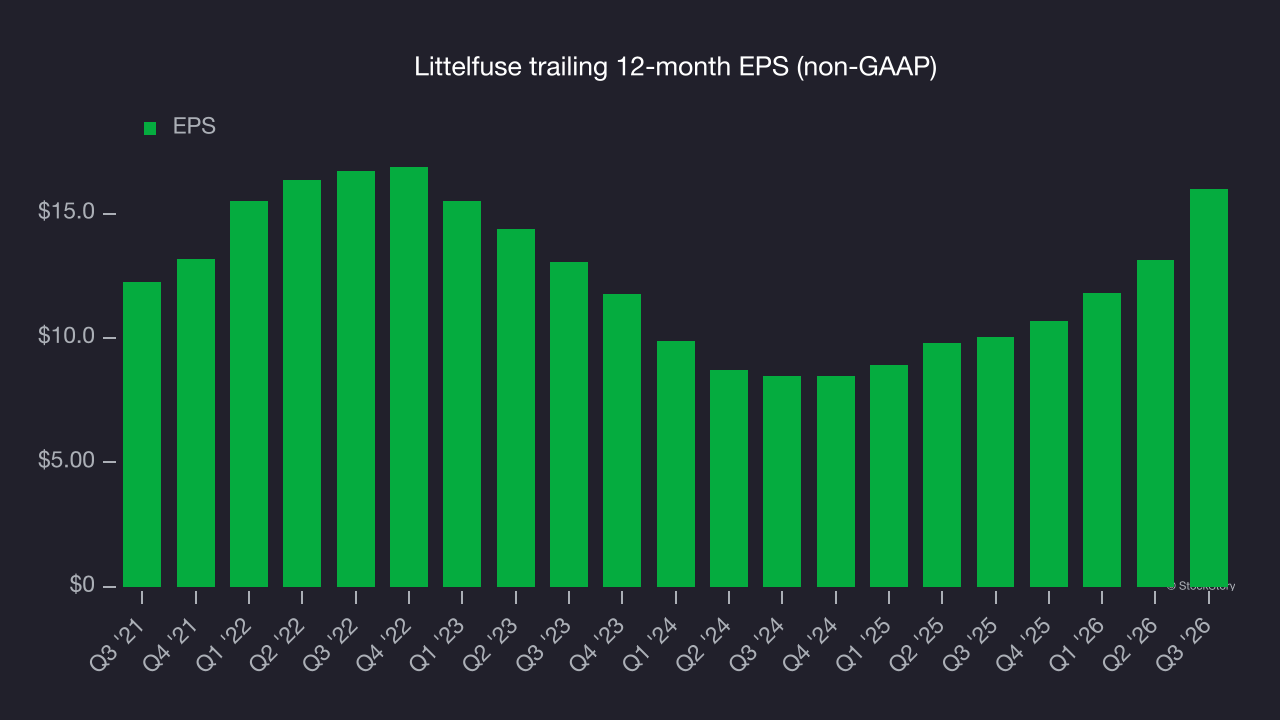
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Littelfuse’s two-year annual EPS growth of 37.4% was strong and topped its 12.1% two-year revenue growth.
Diving into the nuances of Littelfuse’s earnings can give us a better understanding of its performance. Littelfuse’s operating margin has expanded over the last two years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Littelfuse reported adjusted EPS of $5.79, up from $2.95 in the same quarter last year. This result easily beat analysts’ consensus estimates. Over the next 12 months, Wall Street expects Littelfuse’s full-year EPS to grow 22.9% from $15.98 to $19.64, according to S&P.
Key takeaways from Littelfuse’s Q3 results
Next-quarter EPS guidance was a highlight of Littelfuse’s solid quarter, coming in well above analysts’ consensus estimates. EBITDA also topped Wall Street’s consensus by a wide margin, but revenue missed expectations. Shares surged 7.7% to $412.36 immediately after the report.
Littelfuse had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. The latest quarter matters, but longer-term fundamentals and valuation are far more important to that decision. For more on Littelfuse, read our full research report here (it’s free).