Civil infrastructure construction company Sterling Infrastructure (NASDAQ: STRL) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 127% year on year to $1.56 billion. The company’s full-year revenue guidance of $4.68 billion at the midpoint came in 13.6% above analysts’ consensus estimates. Its non-GAAP profit of $7.58 per share was 23.6% above analysts’ consensus estimates.
For more on Sterling, read our free full research report.
Sterling (STRL) Q3 2026 highlights:
- Revenue $1.56 billion vs S&P analysts’ consensus estimates of $1.19 billion (127% year-on-year growth, 31.4% beat)
- Adjusted EPS $7.58 vs S&P analysts’ consensus estimates of $6.13 (23.6% beat)
- Adjusted EBITDA $337.8 million vs analysts’ consensus estimates of $278.3 million (21.6% margin, 21.4% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $4.68 billion at the midpoint from $4.08 billion, a 14.8% increase
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $21.83 at the midpoint, a 9.1% increase
- EBITDA guidance $910.5 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 19.6%, in line with the same quarter last year
- Free cash flow margin 3.4%, down from 9.3% in the same quarter last year
- Market capitalization $11.24 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Sterling’s revenue grew at a strong 23.1% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
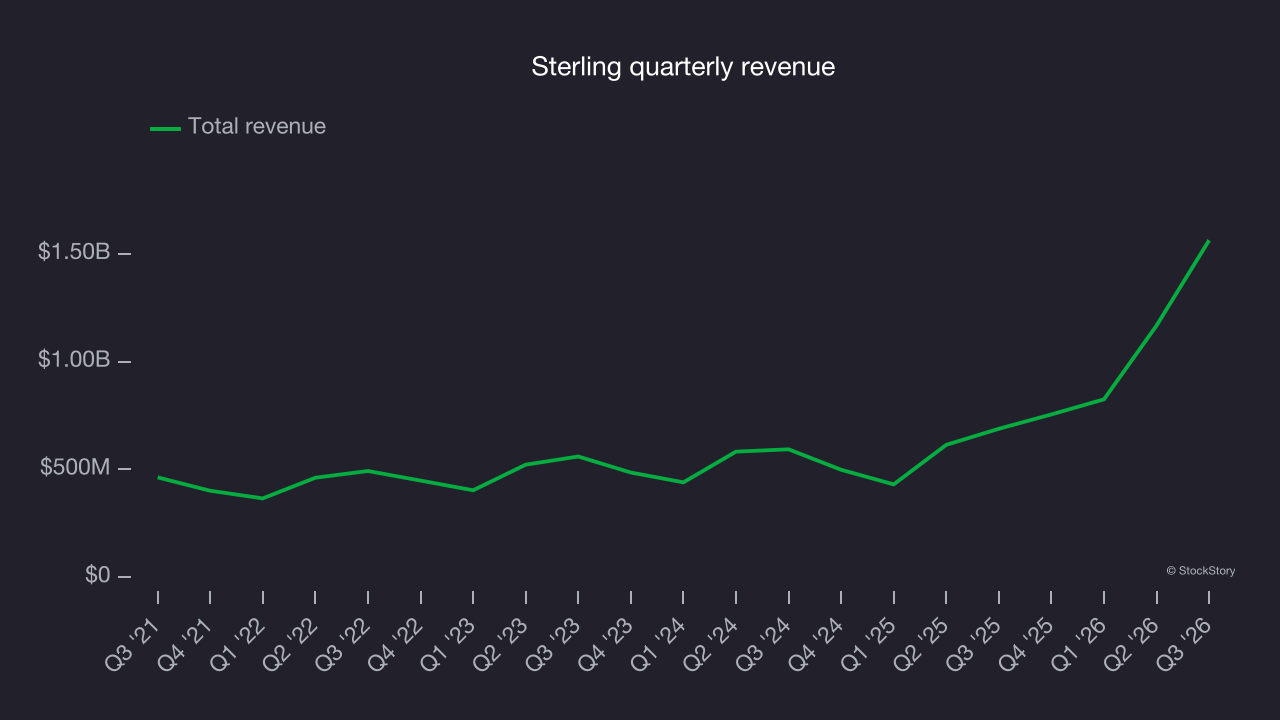
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Sterling’s annualized revenue growth of 43.2% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 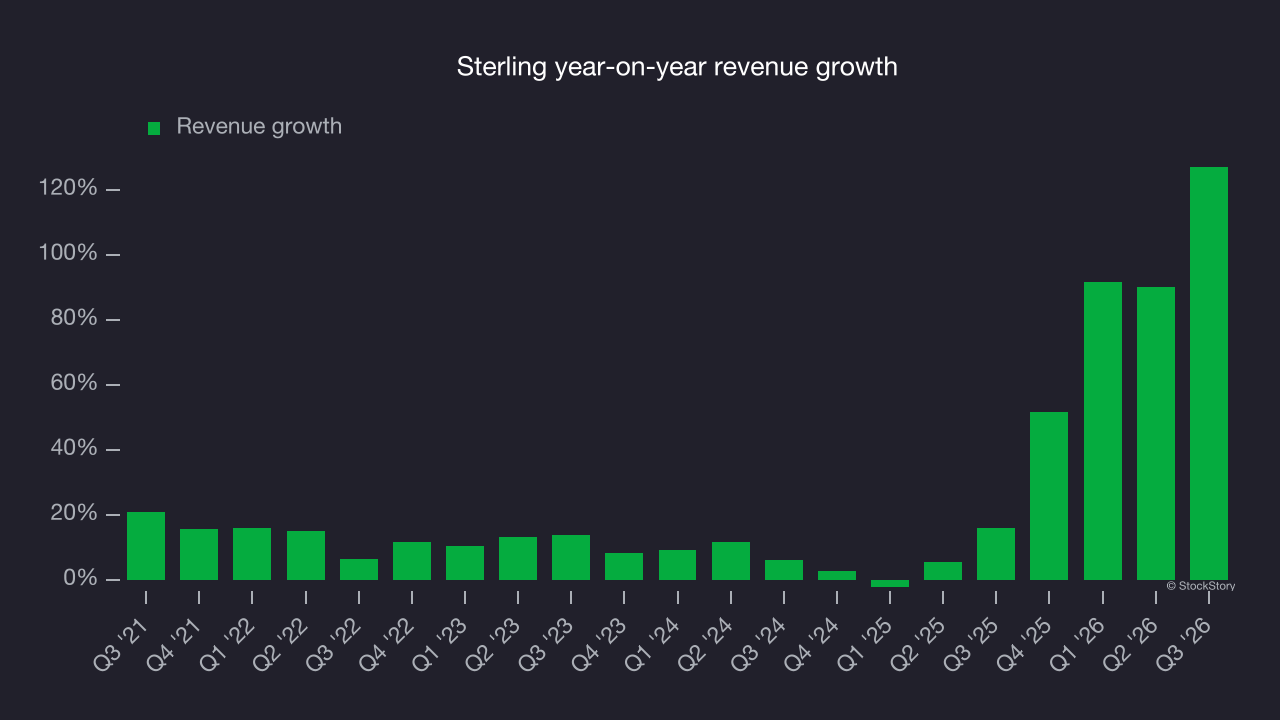
This quarter, Sterling reported year-on-year revenue growth of 127%, and its $1.56 billion of revenue beat Wall Street’s consensus estimates by 31.4%.
Looking ahead, sell-side analysts expect revenue to grow 8% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is above the sector average and suggests the market expects some success for its newer products and services.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Sterling has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 14.2%. This result was particularly impressive given its low gross margin, which is mostly a function of what it sells and requires significant shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Analyzing the trend in its profitability, Sterling’s operating margin rose by 10.2 percentage points over the last five years, as its revenue growth provided operating leverage.
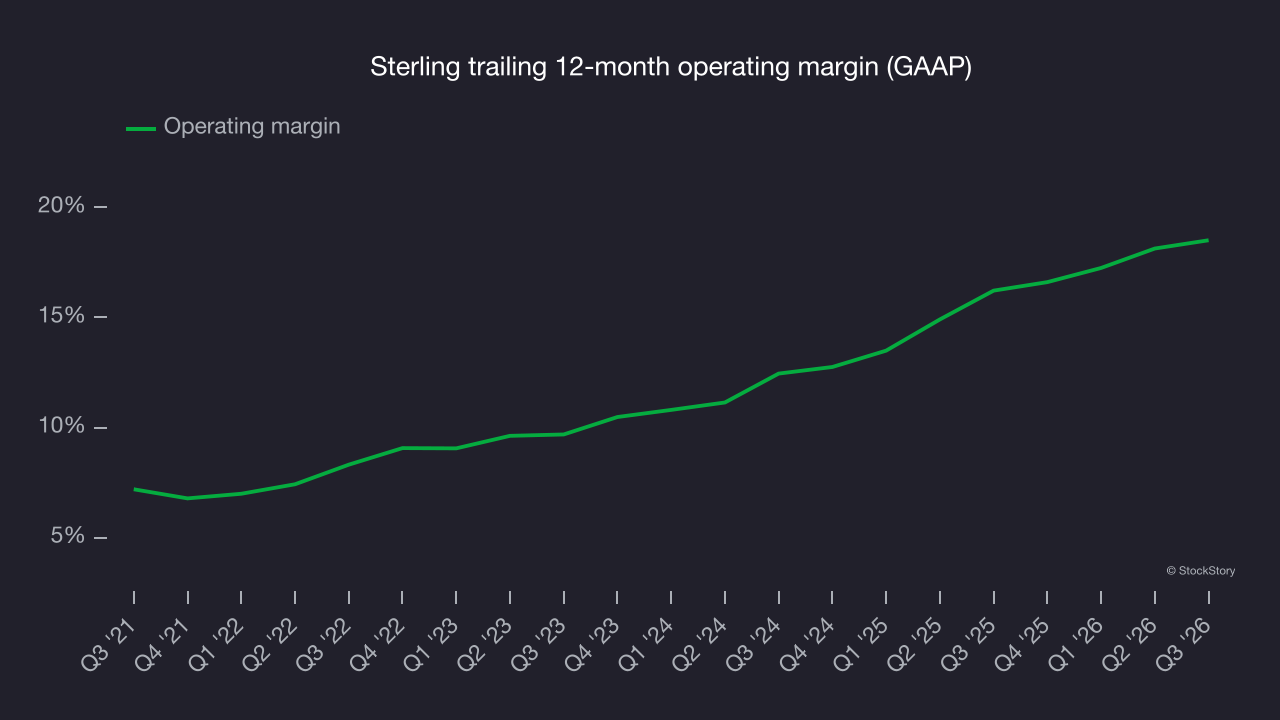
In Q3, Sterling generated an operating margin of 19.6%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Sterling’s EPS grew at a 59.7% compounded annual growth rate over the last five years, higher than its 23.1% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
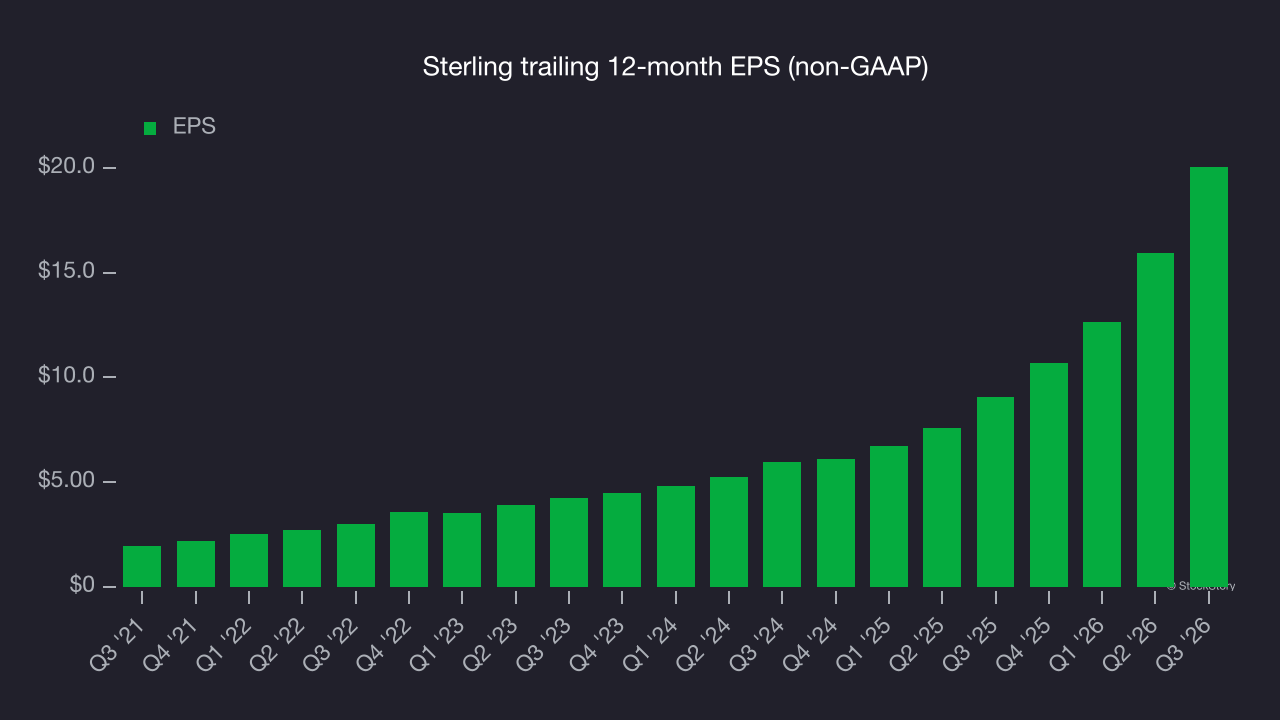
A closer look at Sterling’s earnings helps explain its performance. As mentioned earlier, Sterling’s operating margin was flat this quarter but expanded by 10.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but reveal less about a company’s fundamentals.
As with revenue, examining EPS over a shorter period can reveal changes in the business.
Sterling’s two-year annual EPS growth of 83.7% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Sterling reported adjusted EPS of $7.58, up from $3.48 in the same quarter last year. This result comfortably beat analysts’ consensus estimates. Over the next 12 months, Wall Street expects Sterling’s full-year EPS to grow 18.6% from $20.05 to $23.78, according to S&P.
Key takeaways from Sterling’s Q3 results
Wide beats on EBITDA and revenue were the key positives in Sterling’s quarter, with both measures well above analysts’ consensus estimates. Even so, the market seemed to be hoping for more. Shares tumbled 5.6% to $366.47 immediately after the report.
Considering Sterling at its current price? That decision should take into account its valuation, business quality and latest quarterly results. Read more in our full research report here (it’s free).