


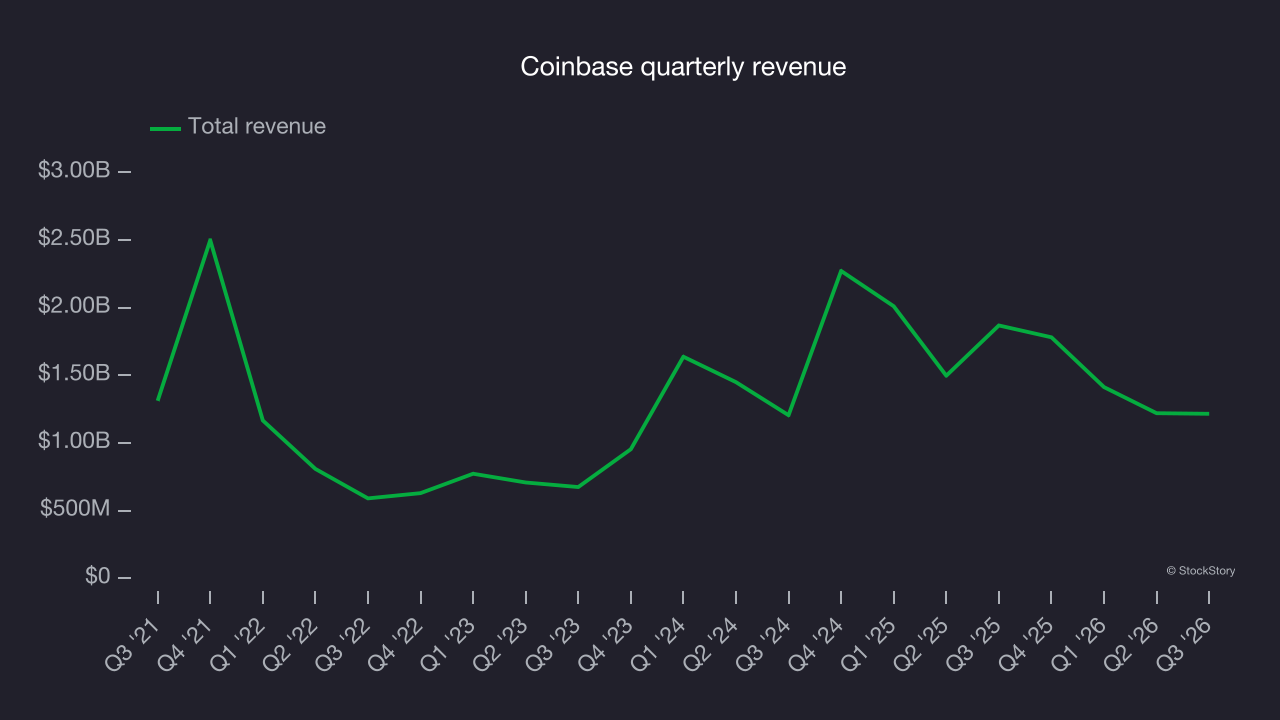
Blockchain infrastructure company Coinbase (NASDAQ: COIN) announced better-than-expected revenue in Q3 2026, but revenue fell by 35% year on year to $1.22 billion. Its GAAP profit of $2.51 per share was significantly above analysts’ consensus estimates.
For more on Coinbase, read our free full research report.
Coinbase (COIN) Q3 2026 highlights:
- Revenue $1.22 billion vs S&P analysts’ consensus estimates of $1.21 billion (35% year-on-year decline, 0.8% beat)
- EPS (GAAP) $2.51 vs analysts’ consensus estimates of -$0.10 (significant beat)
- Adjusted EBITDA $332.9 million vs analysts’ consensus estimates of $286.2 million (27.4% margin, 16.3% beat)
- Operating margin 5.1%, down from 25.7% in the same quarter last year
- Free cash flow margin 33.4%, up from 16.2% in the previous quarter
- Market capitalization $42.83 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Coinbase’s demand was weak over the last five years as its revenue fell at a 1% annual rate. That result was underwhelming, but there are still things to like about Coinbase.
Long-term growth matters the most, but within consumer internet, a half-decade historical view may miss recent innovations or disruptive industry trends. Coinbase’s annualized revenue growth of 3.6% over the last two years is above its five-year trend, a positive sign. 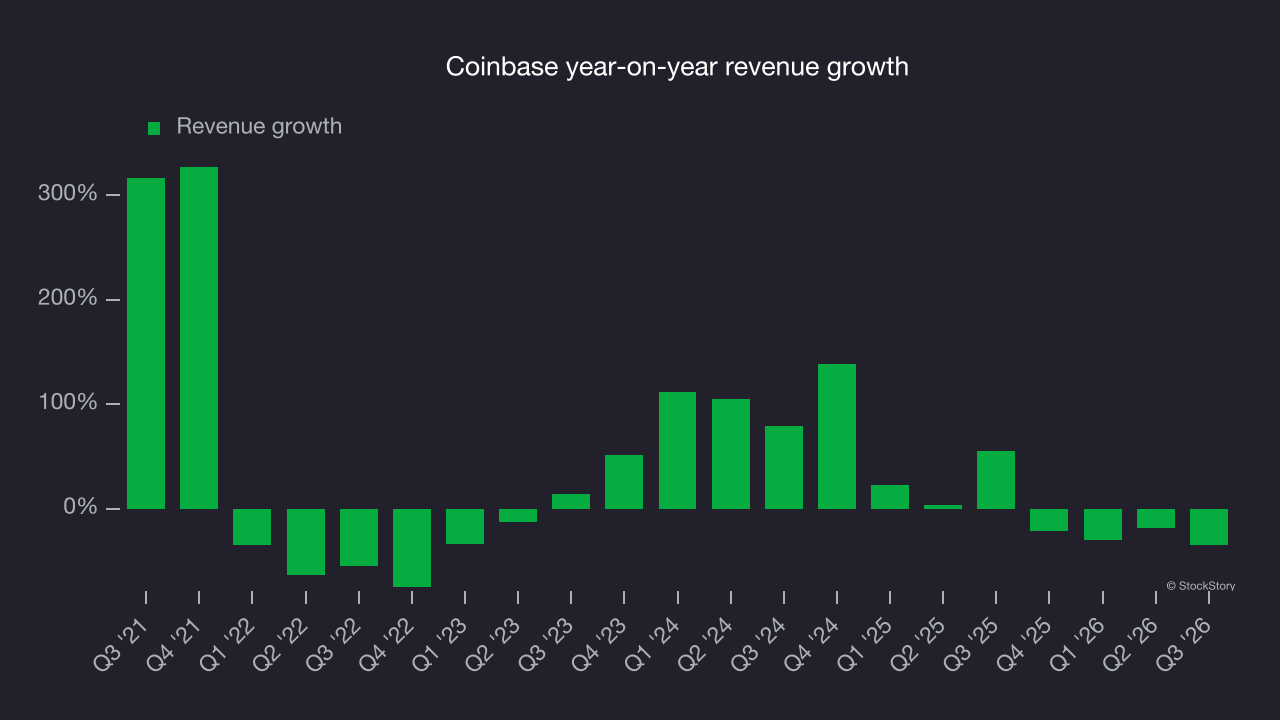
This quarter, Coinbase’s revenue fell by 35% year on year to $1.22 billion but beat Wall Street’s consensus estimates by 0.8%.
Looking ahead, sell-side analysts expect revenue to grow 12% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above average for the sector and implies its newer products and services will drive better revenue performance.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s revealing because it accounts for all operating and capital expenses, making it difficult to manipulate.
Coinbase has shown strong cash profitability, driven by its lucrative business model and cost-effective customer acquisition strategy that enable it to stay ahead of the competition through investments in new products rather than sales and marketing. The company’s free cash flow margin was among the best in the consumer internet sector, averaging 31.5% over the last two years.
On the positive side, Coinbase’s margin expanded meaningfully over the last five years. Its free cash flow profitability rose more than its operating profitability, indicating that it became a less capital-intensive business.
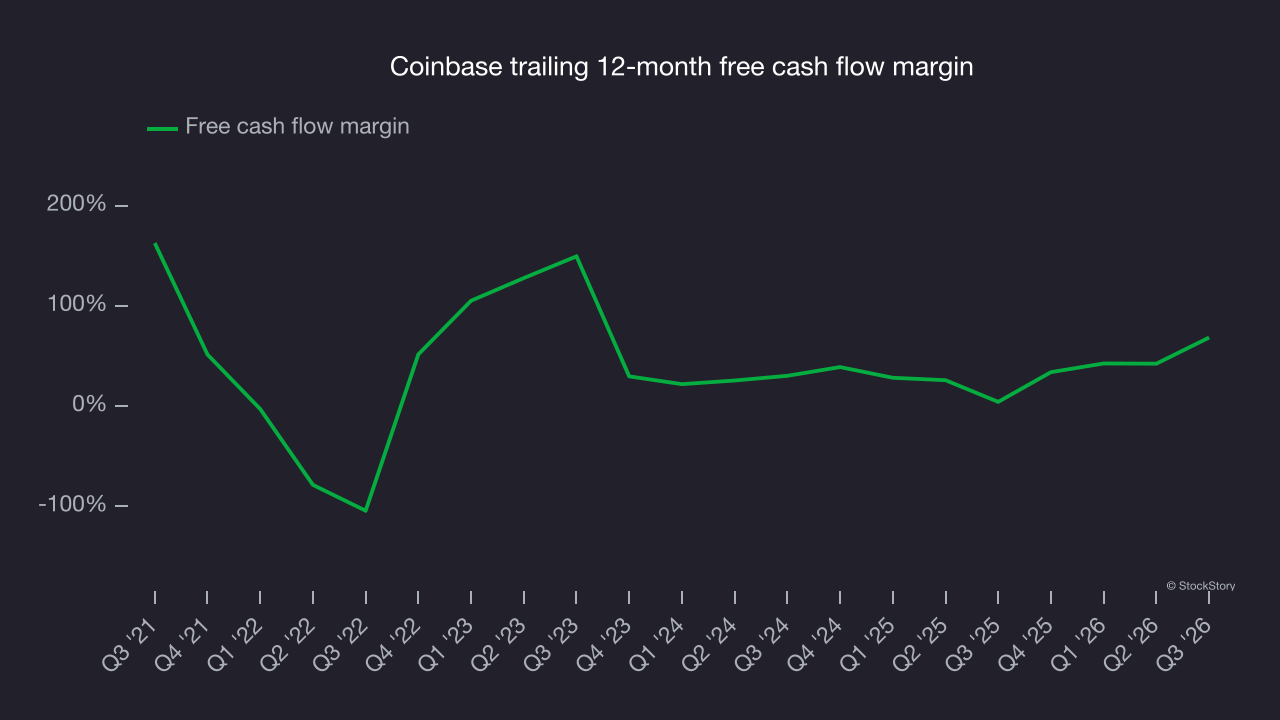
Coinbase’s free cash flow totaled $405.5 million in Q3, equivalent to a 33.4% margin. Its cash flow turned positive after being negative in the same quarter last year, building on its favorable historical trend.
Key takeaways from Coinbase’s Q3 results
Coinbase delivered a solid Q3, with EBITDA well above analysts’ consensus estimates. Investors were likely hoping for more: Shares fell 2% to $156.86 immediately after the results.
Should you invest in Coinbase right now? When making that decision, it’s important to consider its valuation and business quality, as well as what has happened in the latest quarter. Read more in our full research report here (it’s free).






