


Freight transportation and logistics provider Saia (NASDAQ: SAIA) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 17% year on year to $982.5 million. Its GAAP profit of $3.41 per share was 3.2% above analysts’ consensus estimates.
For more on Saia, read our free full research report.
Saia (SAIA) Q3 2026 highlights:
- Revenue $982.5 million vs S&P analysts’ consensus estimates of $968.4 million (17% year-on-year growth, 1.5% beat)
- EPS (GAAP) $3.41 vs analysts’ consensus estimates of $3.31 (3.2% beat)
- Operating margin 12.4%, down from 14.1% in the same quarter last year
- Free cash flow margin 11.3%, down from 12.8% in the same quarter last year
- Sales volumes rose 48.7% year on year (-1.5% in the same quarter last year)
- Market capitalization $8.64 billion
Saia President and CEO Fritz Holzgrefe said, “Our team delivered solid third quarter performance, which included record revenue and tonnage per workday. Revenue per shipment, excluding fuel surcharge, increased 5.8% compared with the third quarter of last year, reflecting continued progress in pricing and mix optimization. We continue to execute our long-term strategy to build a leading national LTL carrier. Investments in our network, people, equipment and technology are strengthening our customer value proposition and further positioning Saia to deliver sustained, profitable growth and long-term value for stockholders.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Saia’s revenue grew at a solid 10.5% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers.
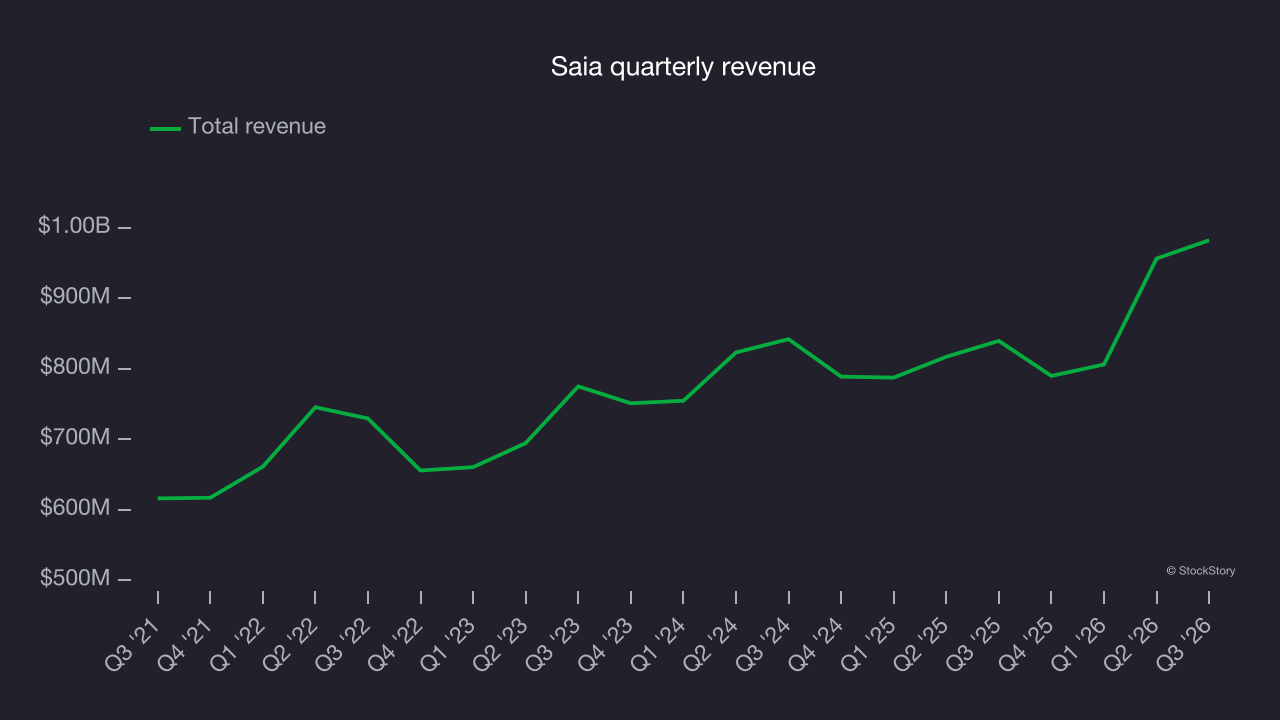
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Saia’s recent performance shows its demand has slowed as its annualized revenue growth of 5.6% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 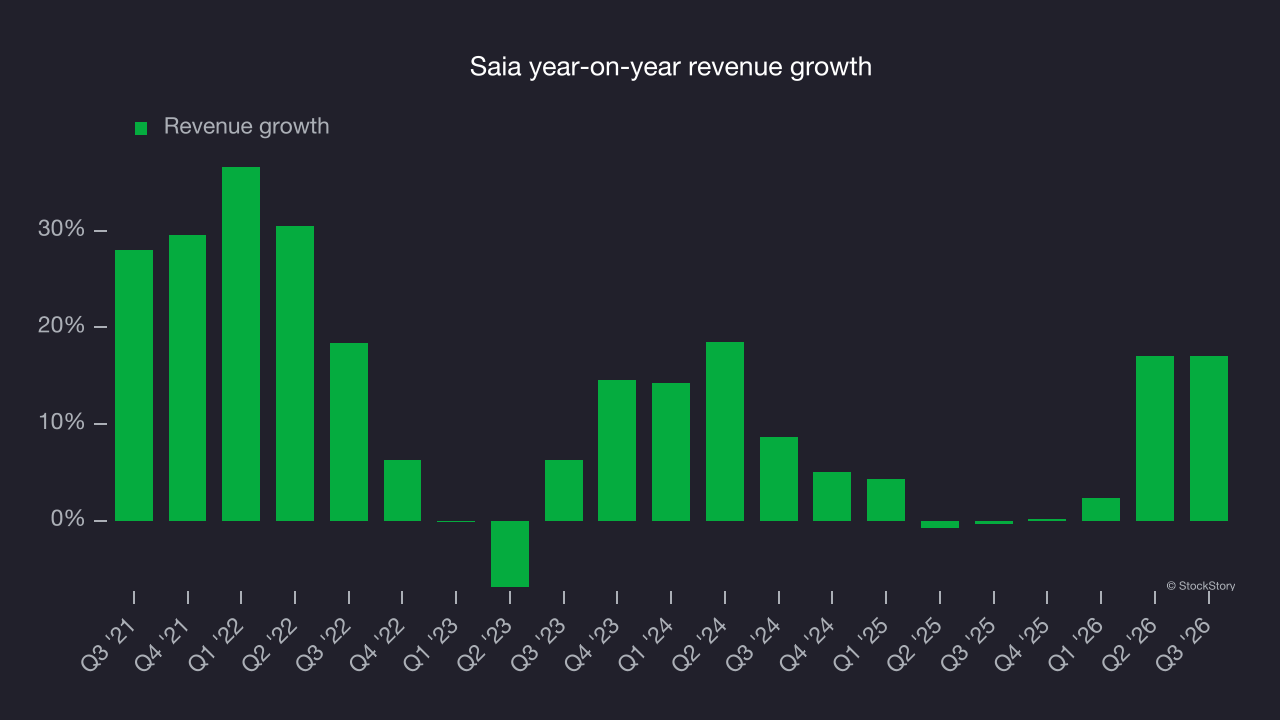
Another way to assess the company’s revenue dynamics is through its tons shipped, which reached 2.35 million in the latest quarter. Over the last two years, Saia’s tons shipped averaged 9.2% year-on-year growth. This metric outpaced revenue growth, indicating that average selling prices decreased. 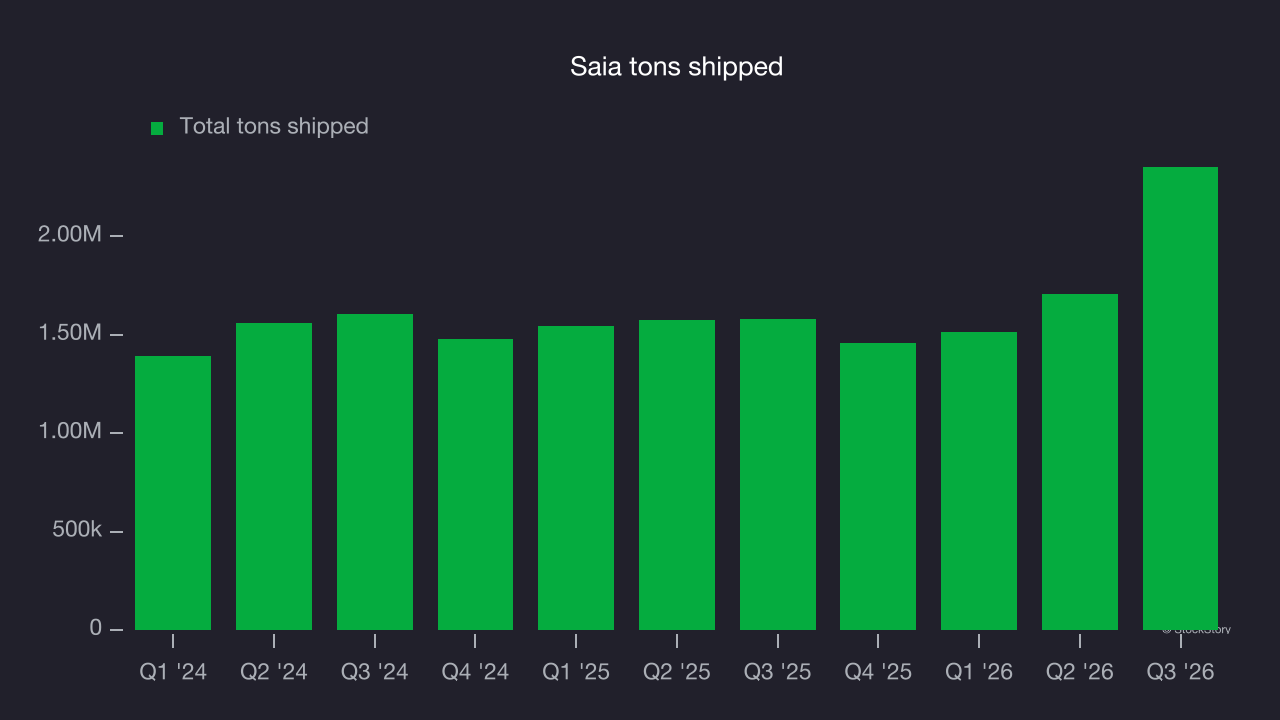
This quarter, Saia reported year-on-year revenue growth of 17%, and its $982.5 million of revenue exceeded Wall Street’s consensus estimates by 1.5%.
Looking ahead, sell-side analysts expect revenue to grow 8.9% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above the sector average and suggests its newer products and services will drive faster revenue growth.
Operating margin
Saia has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 14.1%. This result was particularly impressive because of its low gross margin, which largely reflects what it sells and requires substantial shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Analyzing the trend in its profitability, Saia’s operating margin decreased by 6.6 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
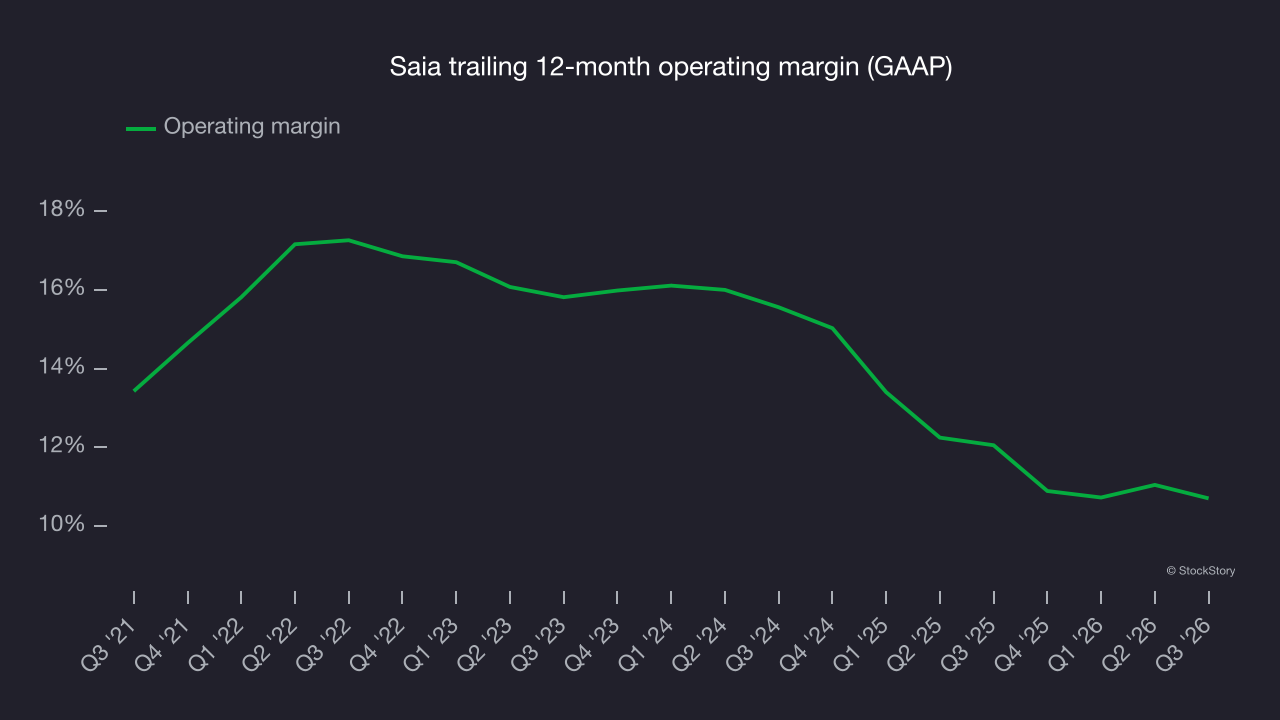
This quarter, Saia generated an operating margin of 12.4%, down 1.7 percentage points year on year. Since Saia’s gross margin decreased more than its operating margin, its recent inefficiencies were likely driven more by weaker leverage on its cost of sales than by increased marketing, R&D and administrative overhead expenses.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Saia’s EPS grew at an unimpressive 5.1% compounded annual growth rate over the last five years, lower than its 10.5% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
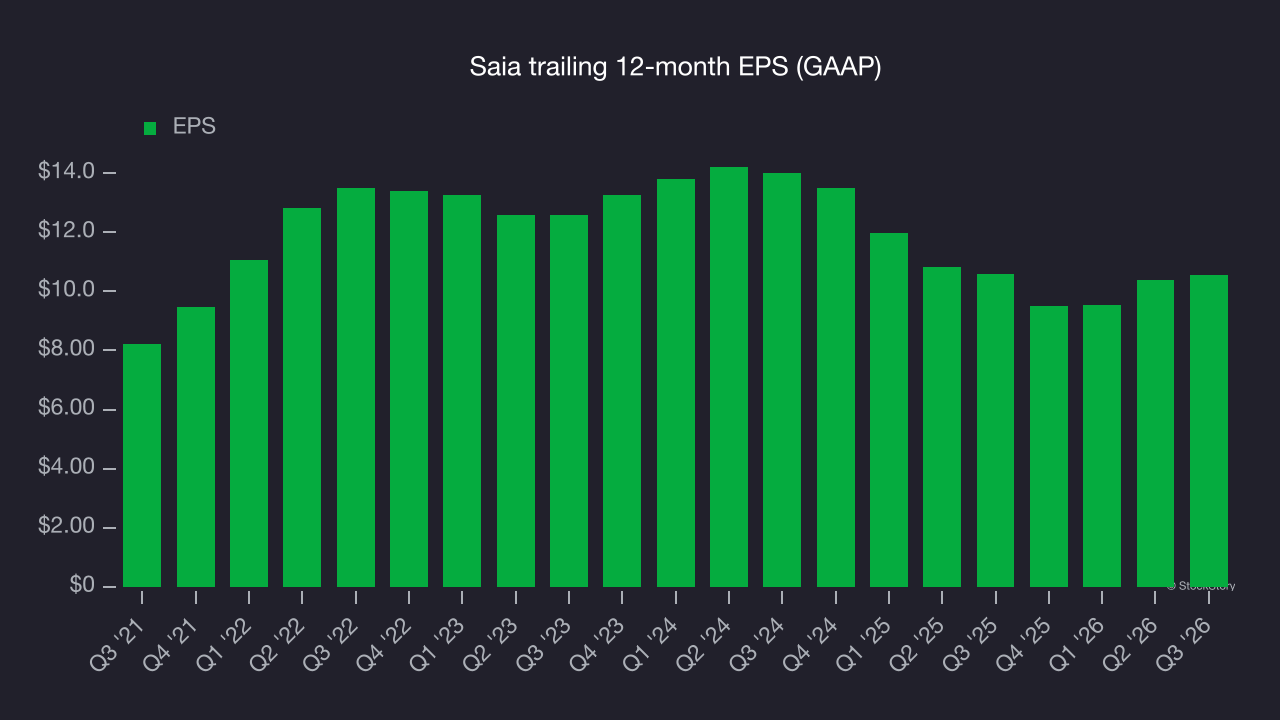
A closer look at Saia’s earnings helps explain its performance. As we mentioned earlier, Saia’s operating margin declined by 6.6 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Saia, its two-year annual EPS declines of 13.2% show it’s continued to underperform. These results were poor across the periods examined.
In Q3, Saia reported EPS of $3.41, up from $3.22 in the same quarter last year. This result beat analysts’ consensus estimates by 3.2%. Over the next 12 months, Wall Street expects Saia’s full-year EPS to grow 29.8% from $10.56 to $13.70, according to S&P.
Key takeaways from Saia’s Q3 results
Saia’s Q3 results had some key positives: Revenue narrowly topped analysts’ consensus estimates, and EPS also beat Wall Street’s estimates. Shares remained flat at $325.54 immediately after the release.
Saia reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. To assess the investment, consider the bigger picture of valuation, business quality and the latest earnings. For more on those factors, read our full research report here (it’s free).






