


Agricultural and farm machinery company Titan (NYSE: TWI) reported earnings that beat analyst estimates. However, next quarter’s revenue guidance of $420 million underwhelmed, coming in 1.3% below analysts’ consensus estimates. Its non-GAAP loss of $0.03 per share was $0.02 above analysts’ consensus estimates.
For more on Titan International, read our free full research report.
Titan International (TWI) Q3 2026 highlights:
- Revenue $335.2 million ($454 million inclusive of discontinued operations) vs S&P analysts’ consensus estimates of $448.8 million
- Adjusted EPS -$0.03 vs S&P analysts’ consensus estimates of -$0.05 ($0.02 beat)
- Adjusted EBITDA $28.15 million vs analysts’ consensus estimates of $27.91 million (8.4% margin, 0.9% beat)
- Revenue guidance $420 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $425.4 million
- EBITDA guidance $96 million at the midpoint for the full year, below analysts’ consensus estimates of $101.7 million
- Operating margin -0.3%, down from 2.2% in the same quarter last year
- Free cash flow margin 2.9%, down from 6.4% in the same quarter last year
- Market capitalization $427.3 million
Operating margin
Titan International was profitable over the last five years but held back by its large cost base. Its average operating margin of 4.9% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
Looking at the trend in its profitability, Titan International’s operating margin decreased by 8.1 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Titan International’s poor performance indicates that costs were rising and it couldn’t pass them on to its customers.
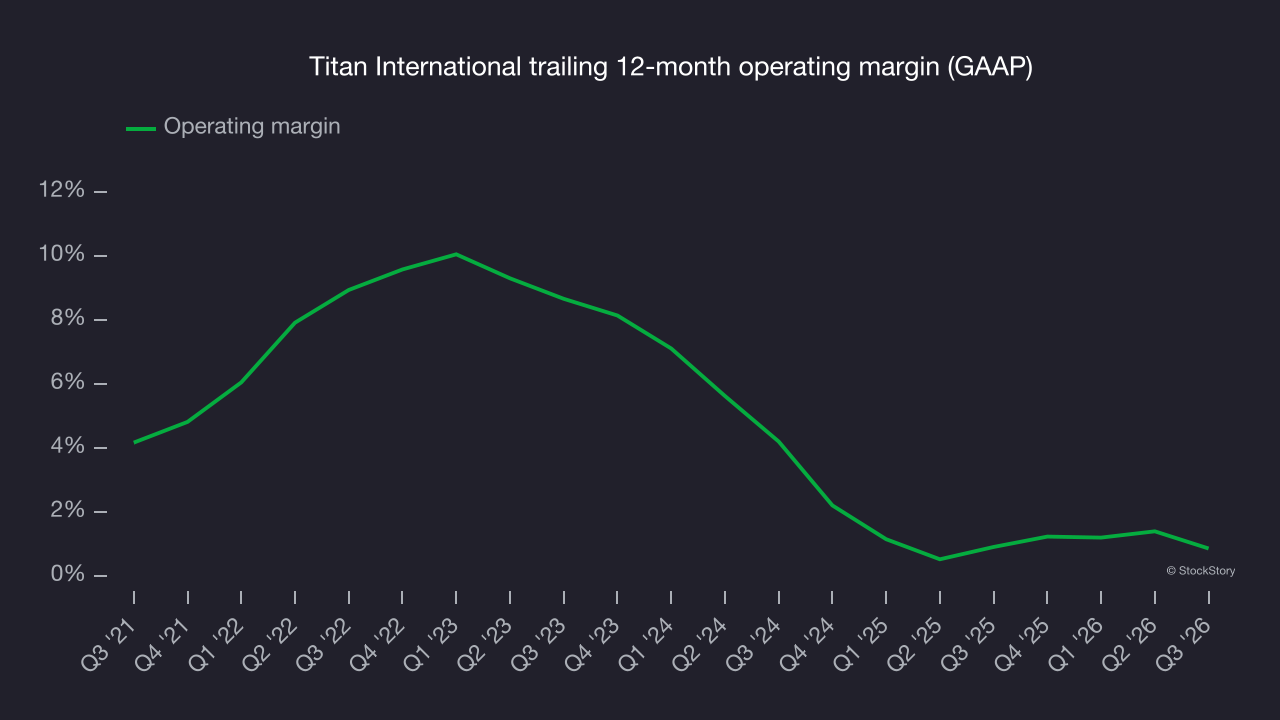
This quarter, Titan International’s breakeven margin was -0.3%, down 2.5 percentage points year on year. Its operating margin decreased more than its gross margin, suggesting it was less efficient as expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Titan International’s EPS declined by 20.6% annually over the last five years while its revenue grew by 1.4%. This shows the company became less profitable on a per-share basis as it expanded.
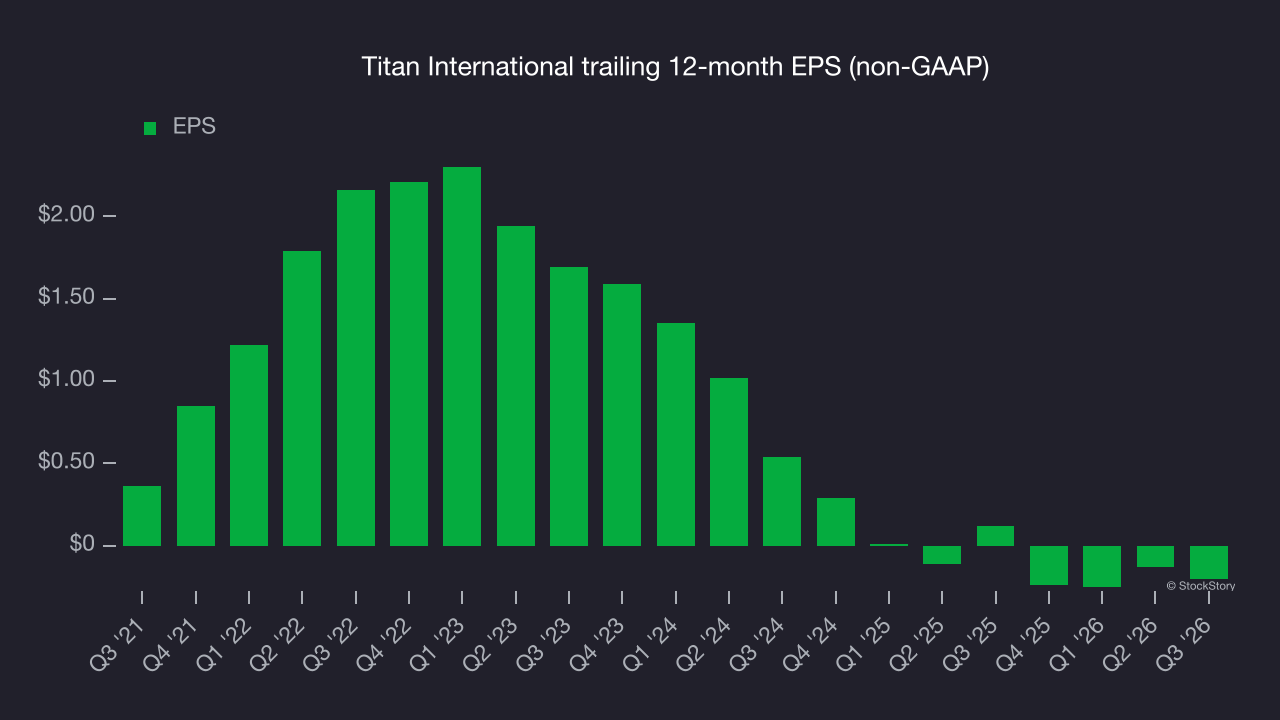
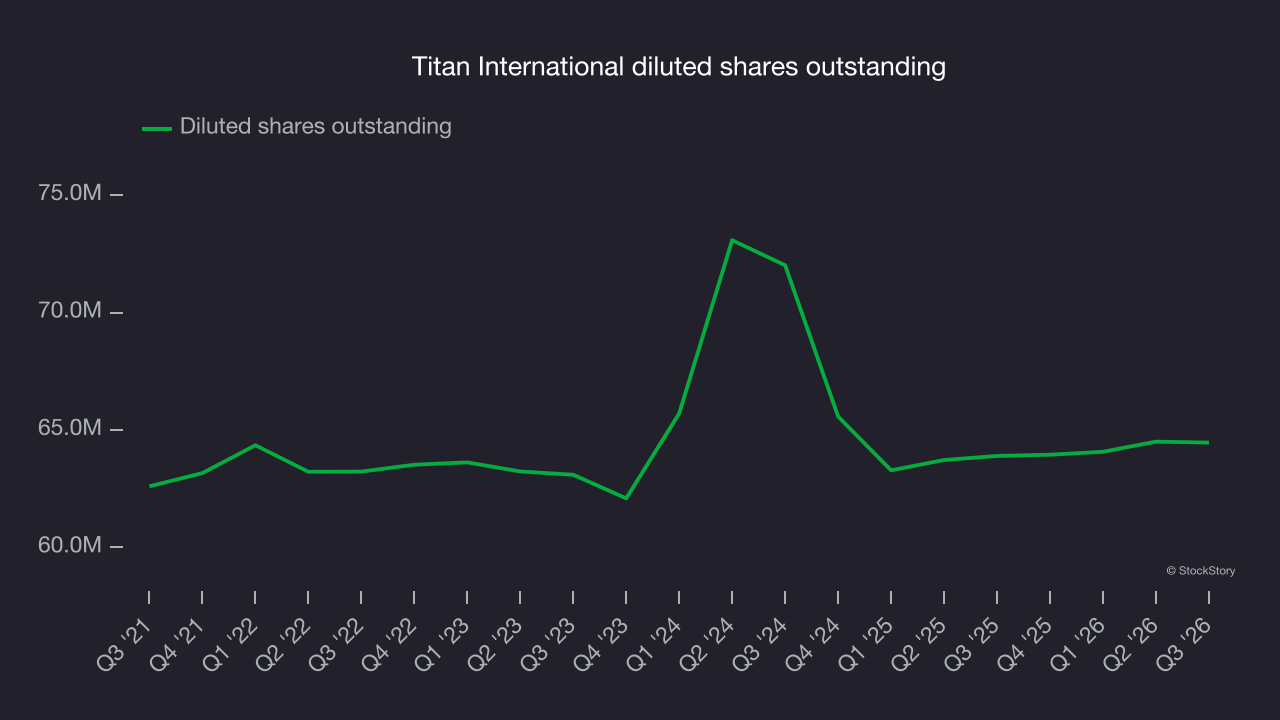
We can take a deeper look into Titan International’s earnings to better understand the drivers of its performance. As we mentioned earlier, Titan International’s operating margin declined by 8.1 percentage points over the last five years. Its share count also grew by 3%, meaning the company not only became less efficient with its operating expenses but also diluted its shareholders.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Titan International, its two-year annual EPS declines of 54% show it has continued to underperform. These results were poor by any measure.
In Q3, Titan International reported adjusted EPS of negative $0.03, down from $0.04 in the same quarter last year. Despite falling year on year, the result comfortably exceeded analysts’ consensus estimates. Over the next 12 months, Wall Street expects an improvement. Analysts forecast Titan International’s full-year EPS will turn from negative $0.20 to positive $0.10, according to S&P.
Key takeaways from Titan International’s Q3 results
Titan International’s quarter was softer overall, with full-year EBITDA guidance missing expectations. There were positives: EPS beat analysts’ consensus estimates, and EBITDA narrowly topped Wall Street’s consensus. Shares remained flat at $6.63 immediately after the results.
The latest quarter is only one factor in assessing Titan International’s longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. For more on the company, read the full research report here (it’s free).






