Energy management company World Kinect (NYSE: WKC) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 41.3% year on year to $13.27 billion. Its non-GAAP profit of $0.99 per share was 3.5% above analysts’ consensus estimates.
For more on World Kinect, read the full research report, available free.
World Kinect (WKC) Q3 2026 highlights:
- Revenue $13.27 billion vs S&P analysts’ consensus estimates of $12.34 billion (41.3% year-on-year growth, 7.5% beat)
- Adjusted EPS $0.99 vs S&P analysts’ consensus estimates of $0.96 (3.5% beat)
- Adjusted EBITDA $127.1 million vs analysts’ consensus estimates of $113.4 million (1% margin, 12.1% beat)
- Operating margin 0.6%, in line with the same quarter last year
- Free cash flow margin 1.2%, similar to the same quarter last year
- Production volumes down -5.7% year on year
- Market capitalization $1.87 billion
"We delivered another strong quarter, supported by healthy fundamentals in Aviation, strong performance in Marine and continued progress in Land," said Ira M. Birns, Chief Executive Officer. "The actions we have taken to reshape the company are creating a stronger, more focused business, better positioned to deliver improved returns and profitable growth."
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. World Kinect’s 11.8% annualized revenue growth over the last five years was decent. Its growth was slightly above that of the average energy upstream and integrated energy company and shows its offerings resonate with customers.
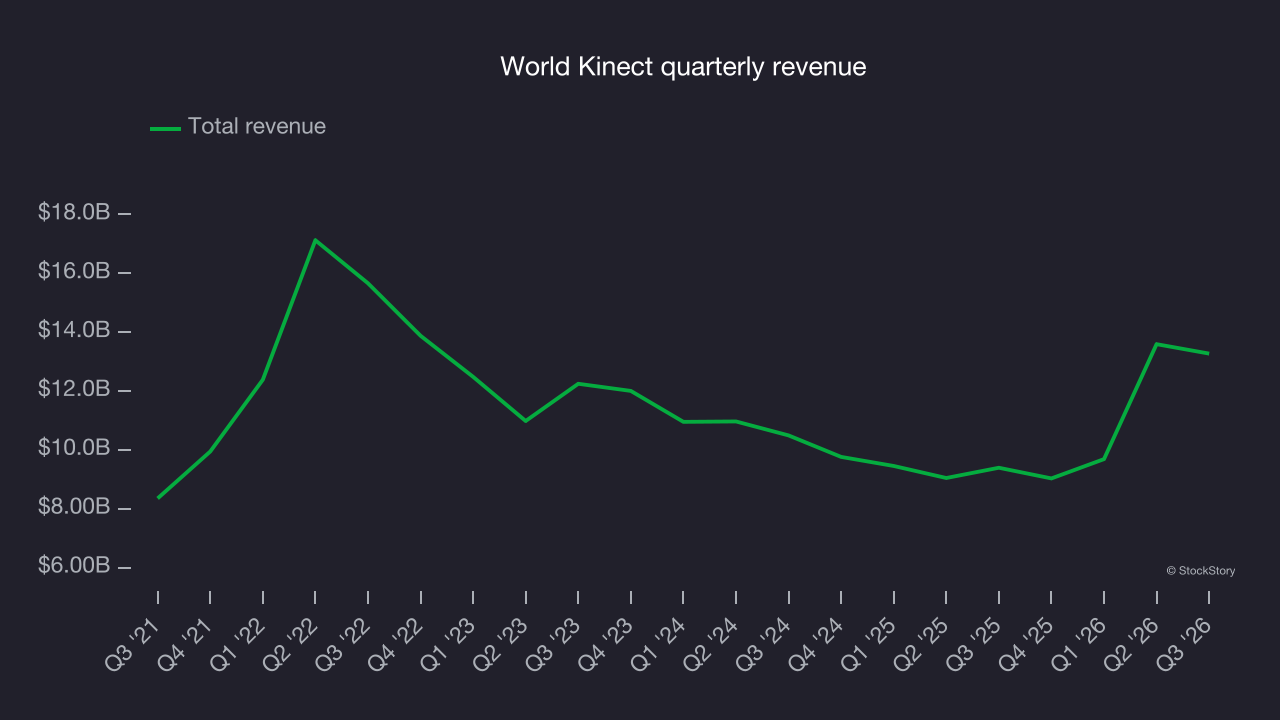
Within energy, a single timeframe, even a long one, only sheds light on how well a company rode the last commodity cycle. To better assess whether a company compounds through cycles, it helps to consider an even longer, ten-year view. World Kinect’s annualized revenue growth of 5.8% over the last ten years is below its five-year trend, but the results were still good.
Revenue provides useful context, but it is heavily influenced by commodity prices and acquisitions. Production volumes, by contrast, reveal whether the underlying asset base is actually growing. Over the last two years, World Kinect’s production volumes averaged 4.6% year-on-year declines. 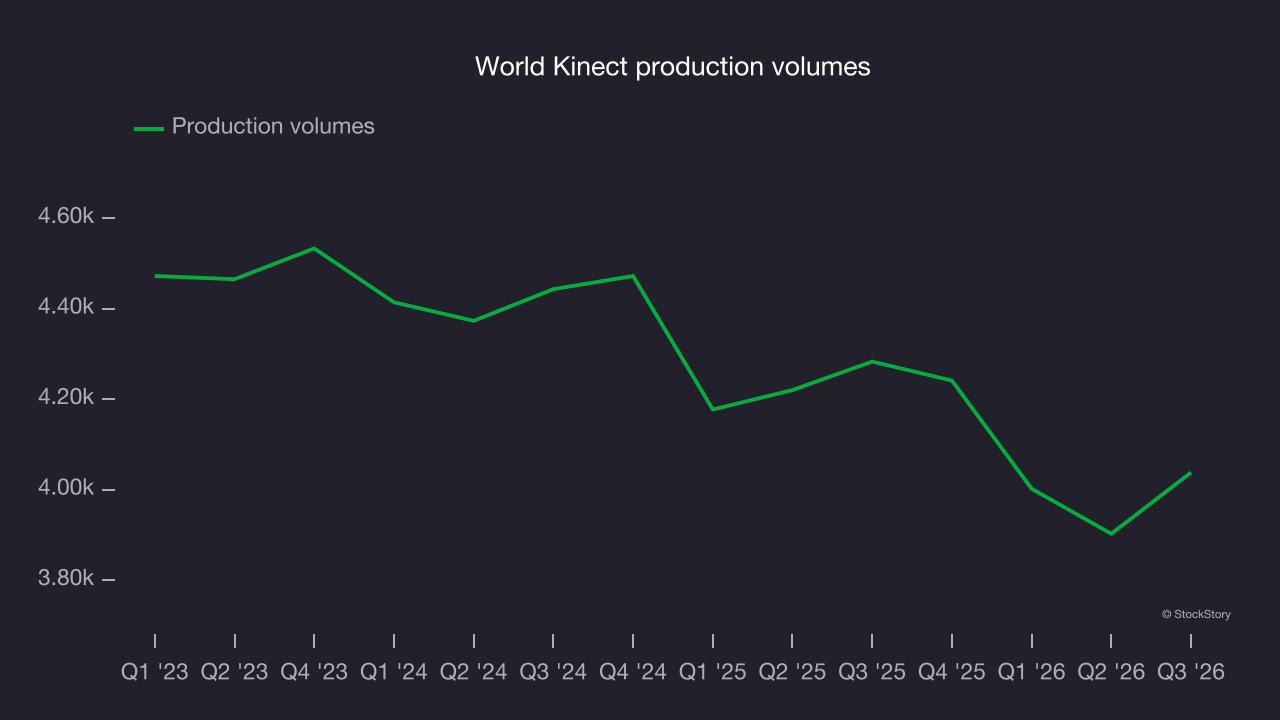
This quarter, World Kinect reported year-on-year revenue growth of 41.3%, and its $13.27 billion of revenue beat Wall Street’s consensus estimates by 7.5%. Its production volumes fell by 5.7% year on year.
Adjusted EBITDA margin
World Kinect was roughly breakeven when averaging the last five years of quarterly operating profits, one of the worst outcomes in the energy upstream and integrated energy sector.
World Kinect’s EBITDA margin may have fluctuated slightly but has generally stayed the same over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
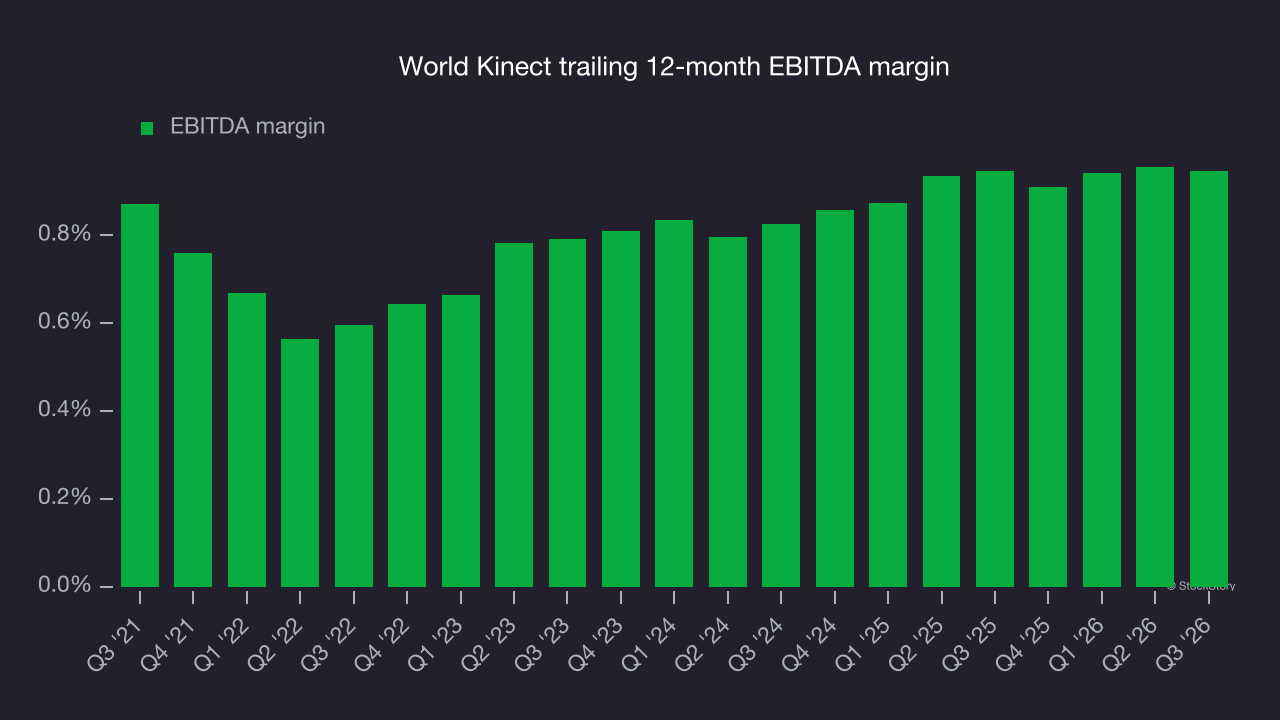
This quarter, World Kinect’s breakeven margin was 1%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable. Adjusted EBITDA beat Wall Street’s consensus estimates by 12.1%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
World Kinect broke even from a free cash flow perspective over the last five years, giving the company limited opportunities to return capital to shareholders.
While the level of free cash flow margins is important, their consistency matters just as much.
World Kinect’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 18.3 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
Why use free cash flow to assess World Kinect’s stability against commodity prices rather than compare its revenue or EBITDA with WTI? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
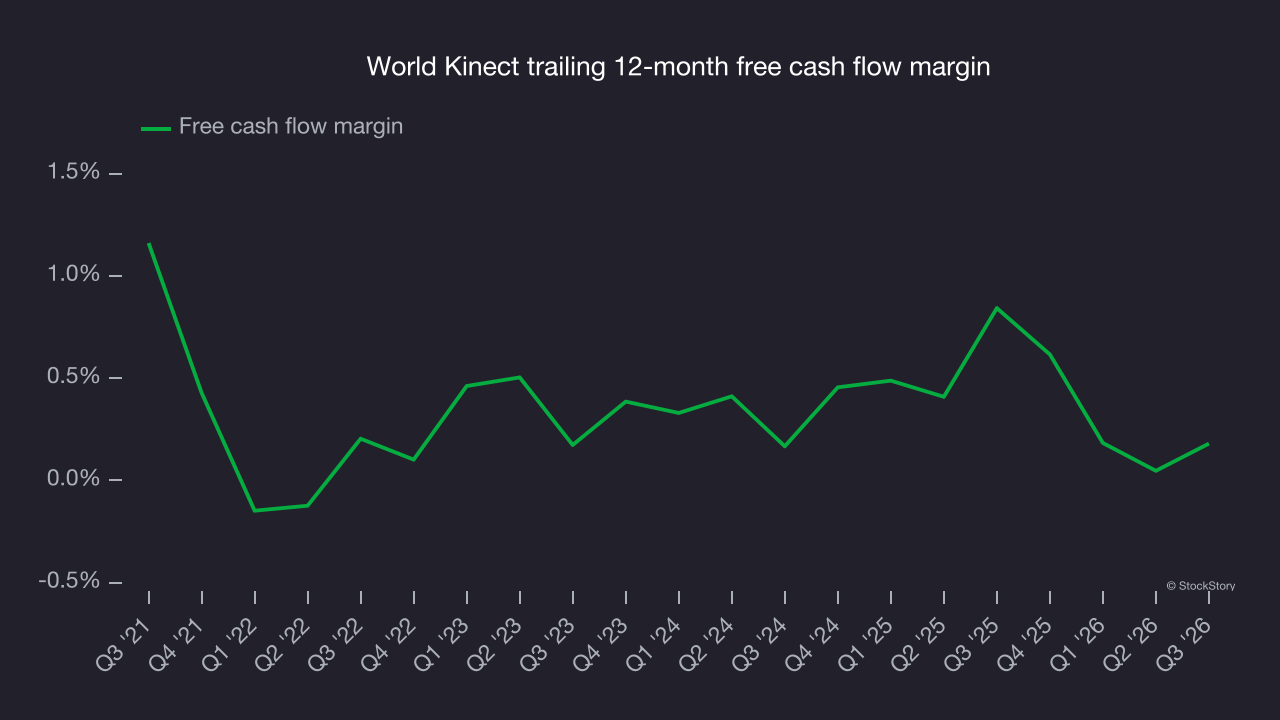
World Kinect’s free cash flow was $164.4 million in Q3, equivalent to a 1.2% margin. This cash profitability was in line with the comparable period last year and its five-year average.
Key takeaways from World Kinect’s Q3 results
World Kinect’s sizable revenue beat and better-than-expected EBITDA gave its Q3 results some clear positives, making this a good quarter overall. Revenue came in well above analysts’ consensus estimates, and EBITDA topped Wall Street’s estimates. Still, the market seemed to be hoping for more: shares tumbled 6.2% to $34.91 immediately after the report.
The latest quarter is only one part of assessing World Kinect’s longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. For more on World Kinect, read our full research report here (it’s free).