Online insurance comparison site EverQuote (NASDAQ: EVER) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 25.4% year on year to $218.1 million. Revenue guidance for next quarter was $218 million at the midpoint, 2.6% above analysts’ consensus estimates. Its GAAP profit of $0.49 per share was in line with analysts’ consensus estimates.
For more on EverQuote, read our free full research report.
EverQuote (EVER) Q3 2026 highlights:
- Revenue $218.1 million vs S&P analysts’ consensus estimates of $202.6 million (25.4% year-on-year growth, 7.6% beat)
- EPS (GAAP) $0.49 vs analysts’ consensus estimates of $0.49 (in line)
- Adjusted EBITDA $35.45 million vs analysts’ consensus estimates of $29.65 million (16.3% margin, 19.6% beat)
- Revenue guidance $218 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $212.5 million
- EBITDA guidance $30.5 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $28.89 million
- Operating margin 11%, in line with the same quarter last year
- Free cash flow margin 17.7%, up from 11.7% in the previous quarter
- Market capitalization $828.5 million
“We are generating record results across our key financial metrics as we successfully grow and deepen our relationships with our carrier and agent customers,” said Jayme Mendal, Chief Executive Officer of EverQuote. “Carriers continue to maintain strong underwriting profitability and an appetite for growth, and our team is executing seamlessly to meet this demand. As we build on our strong foundation to accelerate new product innovation and development, we believe EverQuote is uniquely positioned to help steward P&C insurance into the agentic AI era.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can post a good quarter or two, but the best consistently grow over the long haul. Over the last three years, EverQuote grew its revenue at a strong 35.6% compounded annual growth rate. Its growth beat the average consumer internet company and shows its offerings resonate with customers.
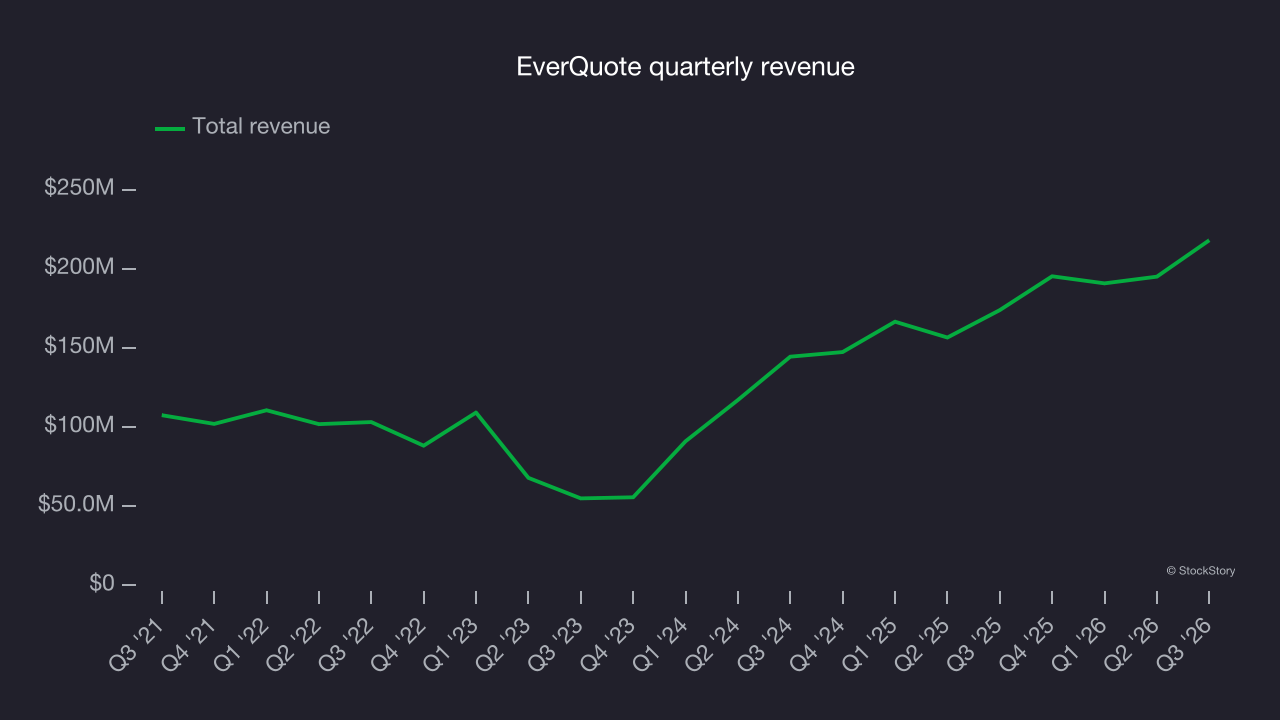
This quarter, EverQuote reported year-on-year revenue growth of 25.4%, and its $218.1 million in revenue topped Wall Street’s consensus estimates by 7.6%. Management is guiding for an 11.6% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 6.4% over the next 12 months, according to S&P, a deceleration versus the last three years. This underwhelming projection implies its products and services will face some demand challenges.
Cash flow
Although EBITDA is valuable for assessing company performance, cash matters more because accounting profits alone cannot pay the bills.
EverQuote has shown strong cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors while maintaining a cash cushion. The company’s free cash flow margin averaged 13.8% over the last two years, an impressive level for a consumer internet business.
EverQuote’s margin expanded by 17.9 percentage points over the last few years. This is a positive development, and the company became less capital-intensive, as its free cash flow profitability rose more than its operating profitability.
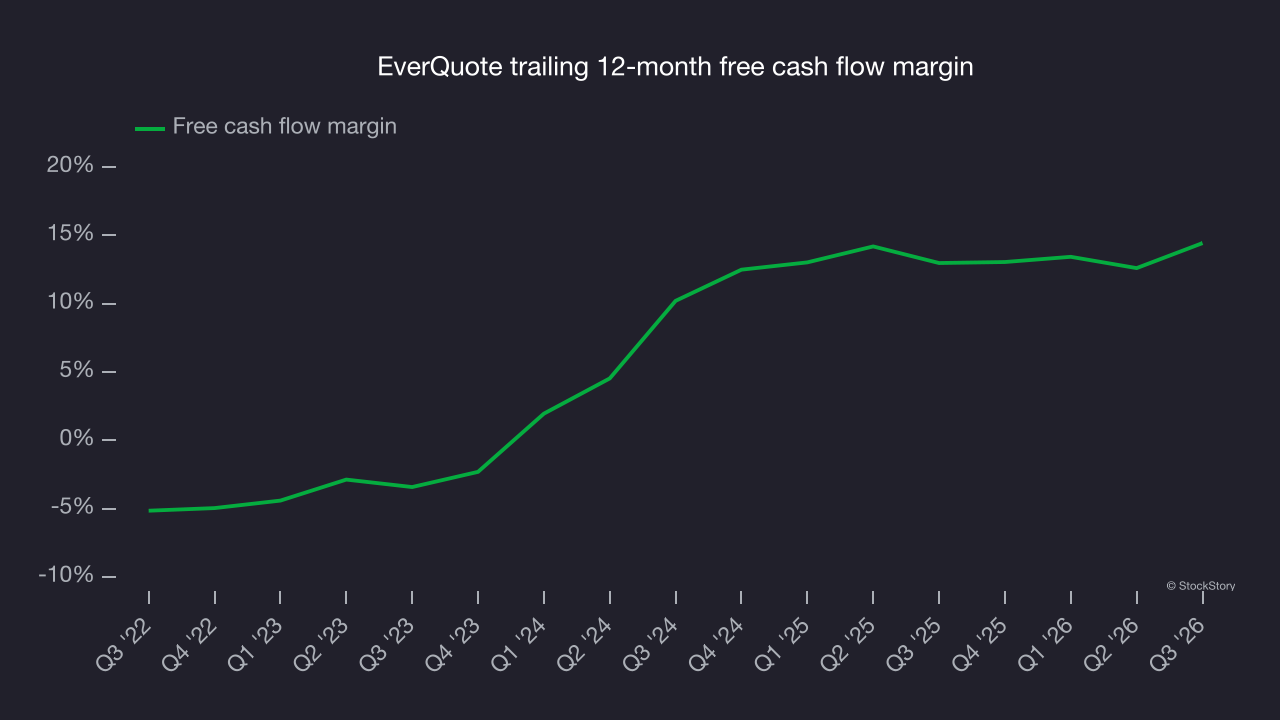
EverQuote’s free cash flow totaled $38.65 million in Q3, equivalent to a 17.7% margin. This was a good result, as its margin was 7.1 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from EverQuote’s Q3 results
EverQuote delivered a solid quarter, with EBITDA well above analysts’ consensus estimates and revenue also topping Wall Street’s consensus. Shares surged 5.3% to $25.55 immediately after the results.
EverQuote reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter matters, but longer-term fundamentals and valuation matter far more when making that decision. For more on those factors, read the full research report here (it’s free).