Cloud contact center software provider Five9 (NASDAQ: FIVN) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue rising 13.1% year on year to $323.3 million. The company expects next quarter’s revenue to be around $331 million, close to analysts’ consensus estimates. Its non-GAAP profit of $0.82 per share was 2.9% above analysts’ consensus estimates.
For more on Five9, read our free full research report.
Five9 (FIVN) Q3 2026 highlights:
- Revenue $323.3 million vs S&P analysts’ consensus estimates of $319.2 million (13.1% year-on-year growth, 1.3% beat)
- Adjusted EPS $0.82 vs S&P analysts’ consensus estimates of $0.80 (2.9% beat)
- Adjusted EBITDA $81.23 million vs analysts’ consensus estimates of $77.78 million (25.1% margin, 4.4% beat)
- Revenue guidance $331 million at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $3.19 at the midpoint, a 2.1% decrease
- Operating margin 4.4%, down from 5.6% in the same quarter last year
- Free cash flow margin 18.1%, up from 4.9% in the previous quarter
- Billings $335.7 million at quarter end, up 14.8% year on year
- Market capitalization $2.72 billion
“Q3 was another solid quarter, highlighted by accelerating subscription revenue growth, with AI revenue growth stepping up significantly. These results indicate that our Humantic CX strategy is working. As AI reshapes the customer experience landscape, we believe adding Level AI strengthens our competitive position, expands the customers we can serve, and deepens the AI talent behind our continuous innovation.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Five9 grew its revenue at a 17.1% compounded annual growth rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough for the software sector, which can display significant earnings volatility. The bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year growth period starts around Covid, when revenue was depressed then rebounded.
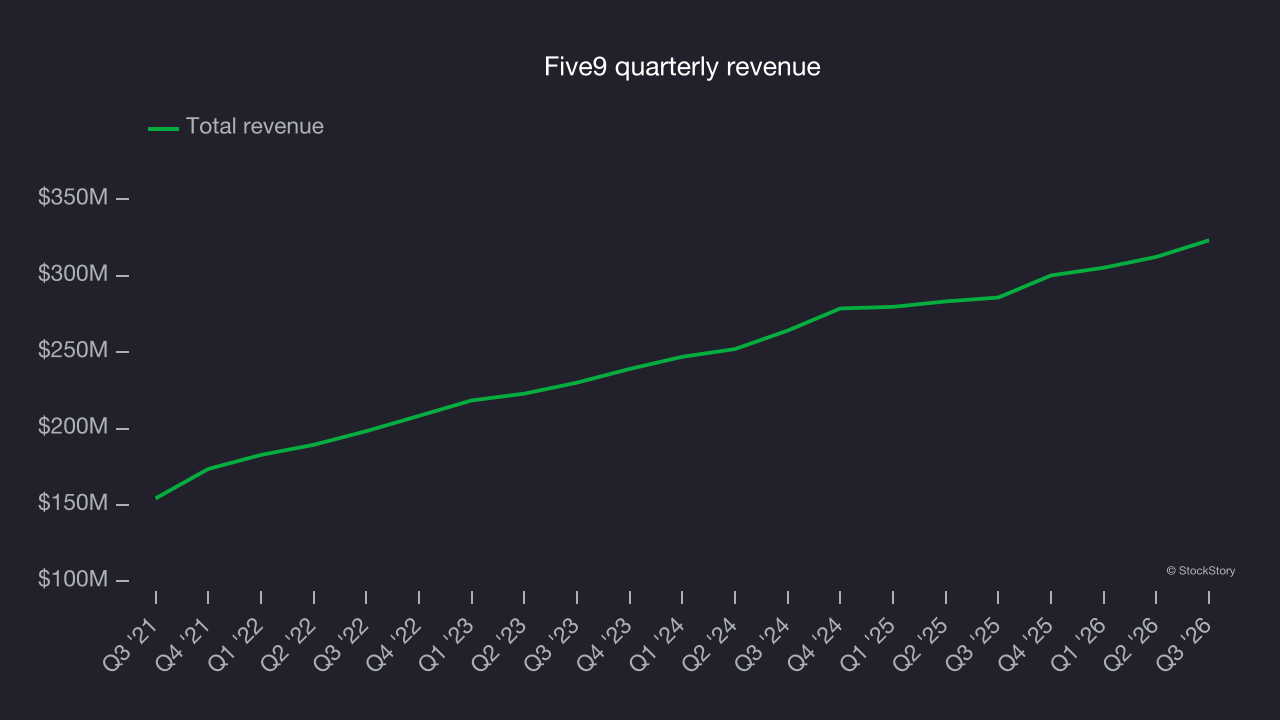
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. Five9’s recent performance shows its demand has slowed as its annualized revenue growth of 11.3% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 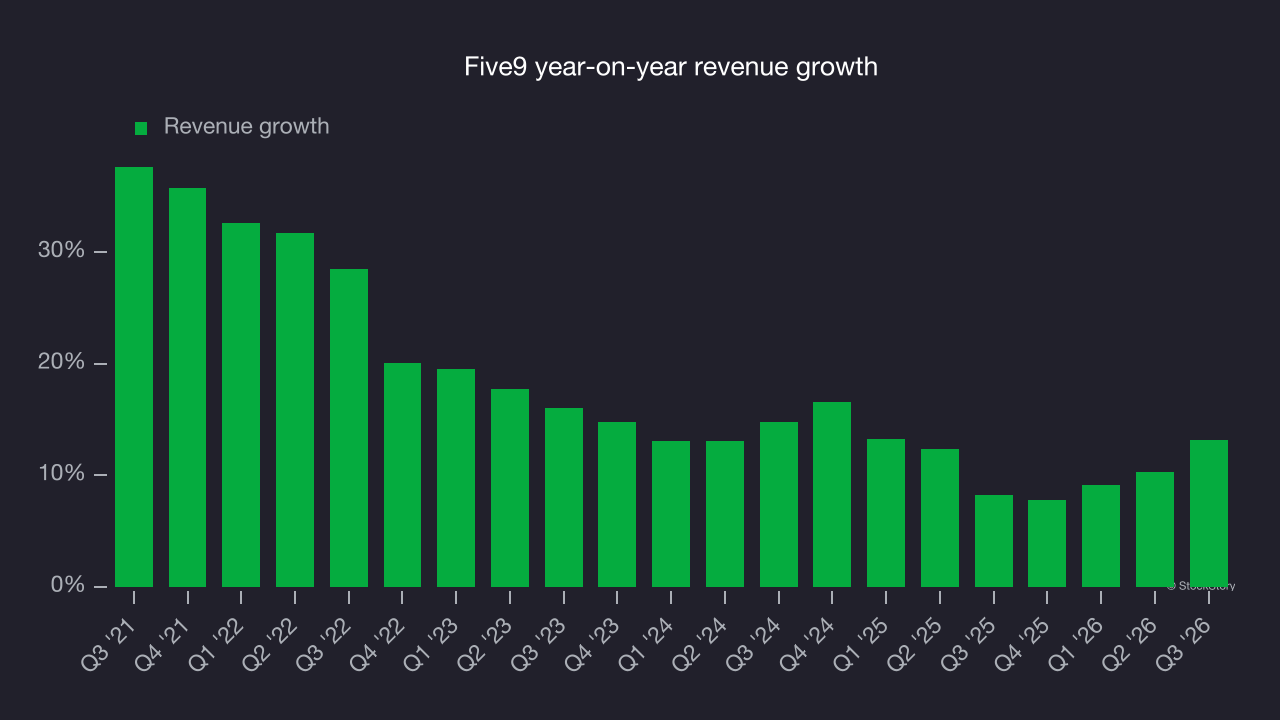
This quarter, Five9 reported year-on-year revenue growth of 13.1%, and its $323.3 million of revenue exceeded Wall Street’s consensus estimates by 1.3%. Company management is currently guiding for a 10.2% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 9.7% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This underwhelming projection implies its products and services will face some demand challenges.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Five9’s billings came in at $335.7 million in Q3, and over the last four quarters, its growth was underwhelming as it averaged 11.6% year-on-year increases. This performance mirrored its total revenue and suggests that increasing competition is making it harder to acquire and retain customers. 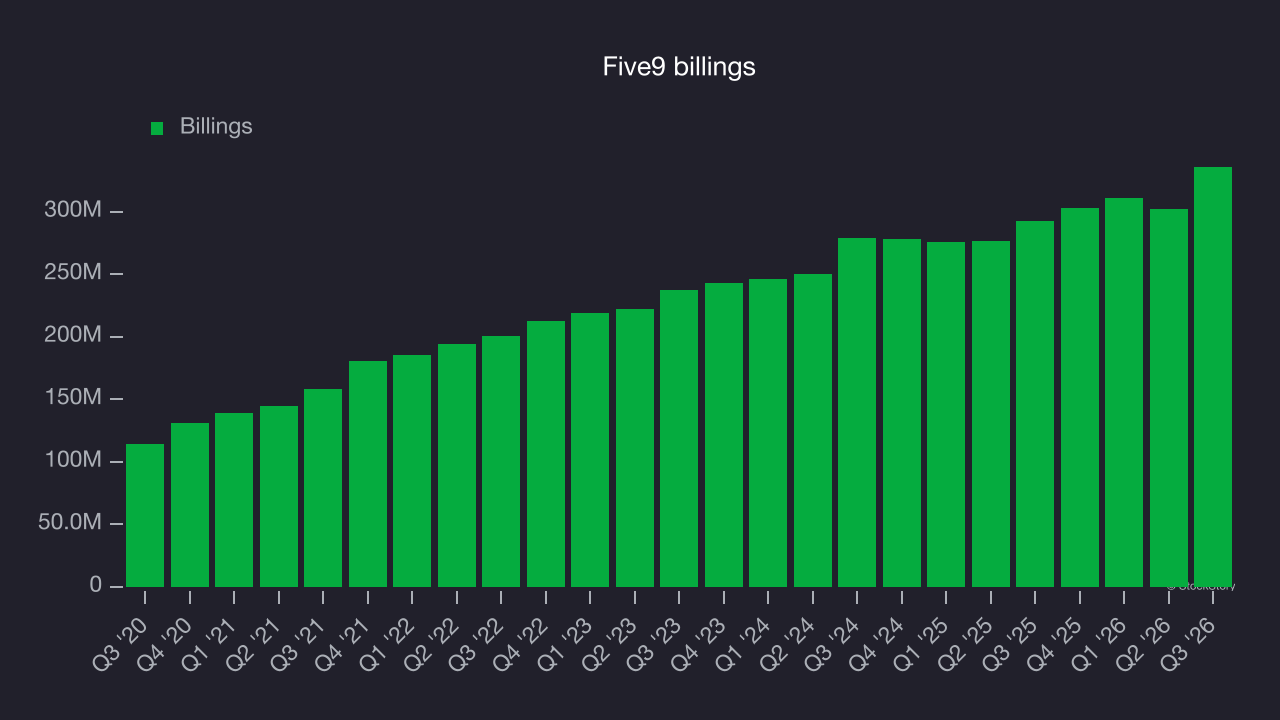
Customer acquisition efficiency
The customer acquisition cost, or CAC, payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
It’s relatively expensive for Five9 to acquire new customers as its CAC payback period was 53.1 months this quarter. The company’s slow recovery of its sales and marketing expenses indicates it operates in a highly competitive market and must invest to stand out, even if the return on that investment is low.
Key takeaways from Five9’s Q3 results
Five9’s guidance put a weaker cast on its Q3 results: EPS forecasts for both next quarter and the full year fell short of Wall Street’s consensus estimates. Those shortfalls contrasted with beats on adjusted operating income and billings this quarter. Overall, it was a weaker quarter, and shares plunged 19.8% to $27.40 immediately after the release.
Considering an investment in Five9? The decision should account for valuation, business quality and the latest earnings. Read our full research report here (it’s free).