Luxury hotels and casino operator Wynn Resorts (NASDAQ: WYNN) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 7.9% year on year to $1.69 billion. Its non-GAAP profit of $0.33 per share was 44.5% below analysts’ consensus estimates.
For more on Wynn Resorts, read our free full research report.
Wynn Resorts (WYNN) Q3 2026 highlights:
- Revenue $1.69 billion vs S&P analysts’ consensus estimates of $1.76 billion (7.9% year-on-year decline, 3.8% miss)
- Adjusted EPS $0.33 vs S&P analysts’ consensus estimates of $0.59 (44.5% miss)
- Operating margin 10.6%, down from 16.9% in the same quarter last year
- Market capitalization $8.36 billion
"Our third quarter results demonstrated strong operational discipline from the teams in each of our regions," said Craig Billings, CEO of Wynn Resorts, Limited. "Wynn Las Vegas and our Macau properties both saw healthy demand amid slower market conditions. Wynn Las Vegas was also negatively impacted by a hold rate outside of our expected range. In Boston, the team did an excellent job managing through the strike that began in early September, ensuring that we could continue delighting guests at our resort. The team at Wynn Al Marjan Island has also made substantial progress with ongoing finishing works occurring throughout the property, including the interior fit-out of all guest rooms, as we move closer to a planned September 2027 opening."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Over the last five years, Wynn Resorts grew its revenue at a 16.4% annual rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough in the consumer discretionary sector, which can display significant earnings volatility. This means the bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year growth period begins around Covid, when revenue was depressed before rebounding.
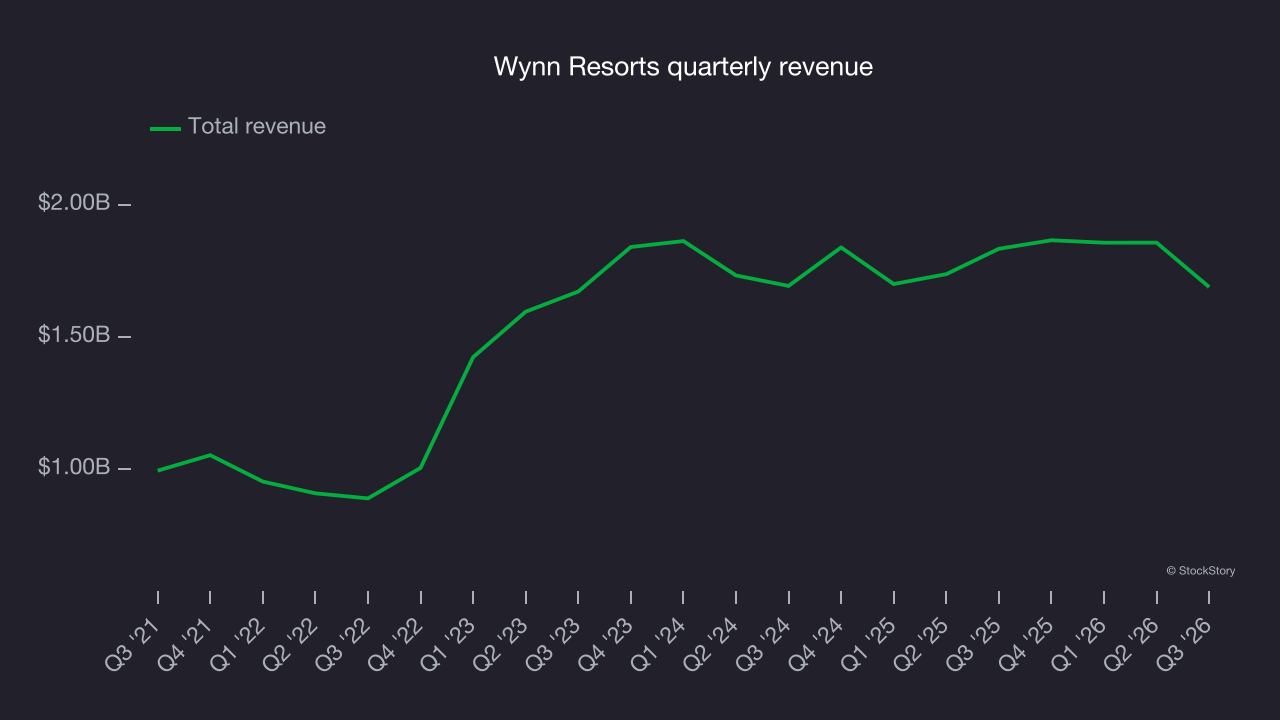
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Wynn Resorts’s recent performance shows its demand has slowed as its revenue was flat over the last two years. Note that Covid hurt Wynn Resorts’s business in 2020 and part of 2021, and it recovered sharply thereafter. 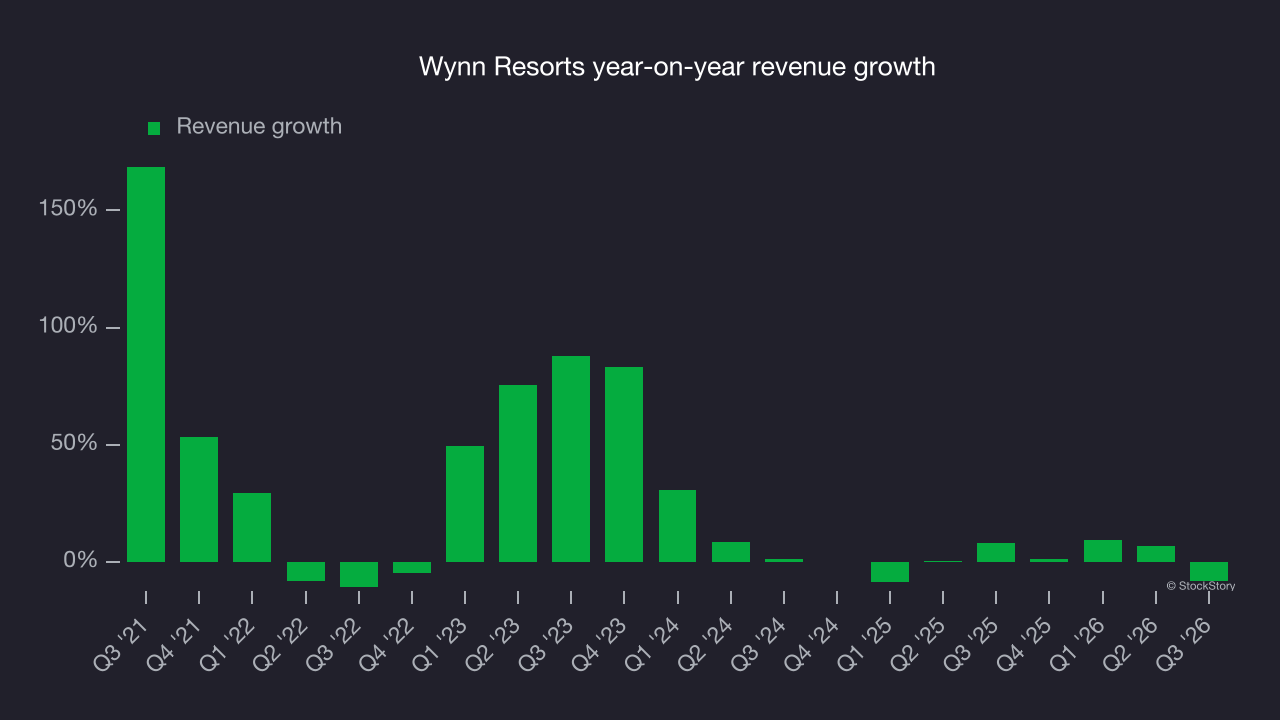
The company’s revenue dynamics become clearer through its three most important segments: Casino, Hotel and Dining and Entertainment, which account for 62.2%, 15.5% and 15.3% of revenue. Over the last two years, Wynn Resorts’s Casino revenue (poker, slots) averaged 4.2% year-on-year growth while its Hotel (overnight bookings) and Dining and Entertainment (food, beverage, Wynn Interactive) revenues averaged declines of 4.5% and 1.6%. 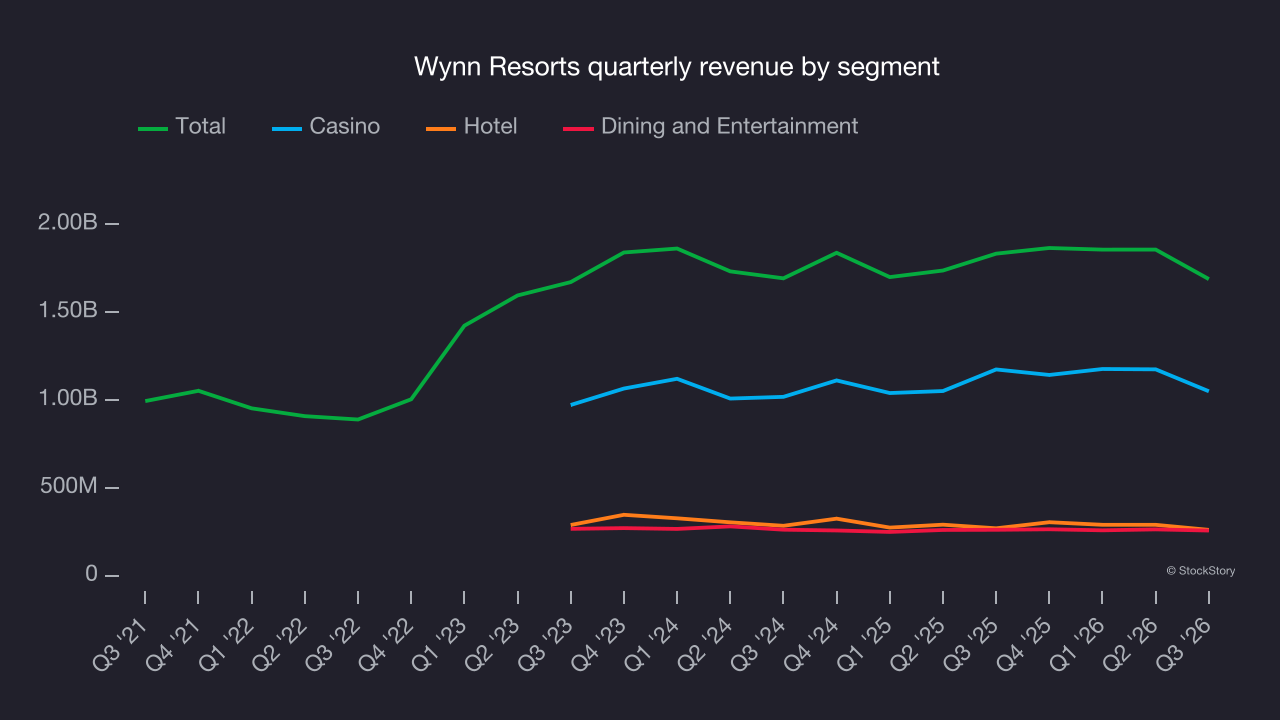
This quarter, Wynn Resorts missed Wall Street’s consensus estimates and reported an uninspiring 7.9% year-on-year revenue decline, generating $1.69 billion of revenue.
Looking ahead, sell-side analysts expect revenue to grow 3.9% over the next 12 months, according to S&P. While this projection implies its newer products and services will spur better top-line performance, it is still below the sector average.
Operating margin
Wynn Resorts’s operating margin has been trending down over the last 12 months and averaged 15.6% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses on to its customers.
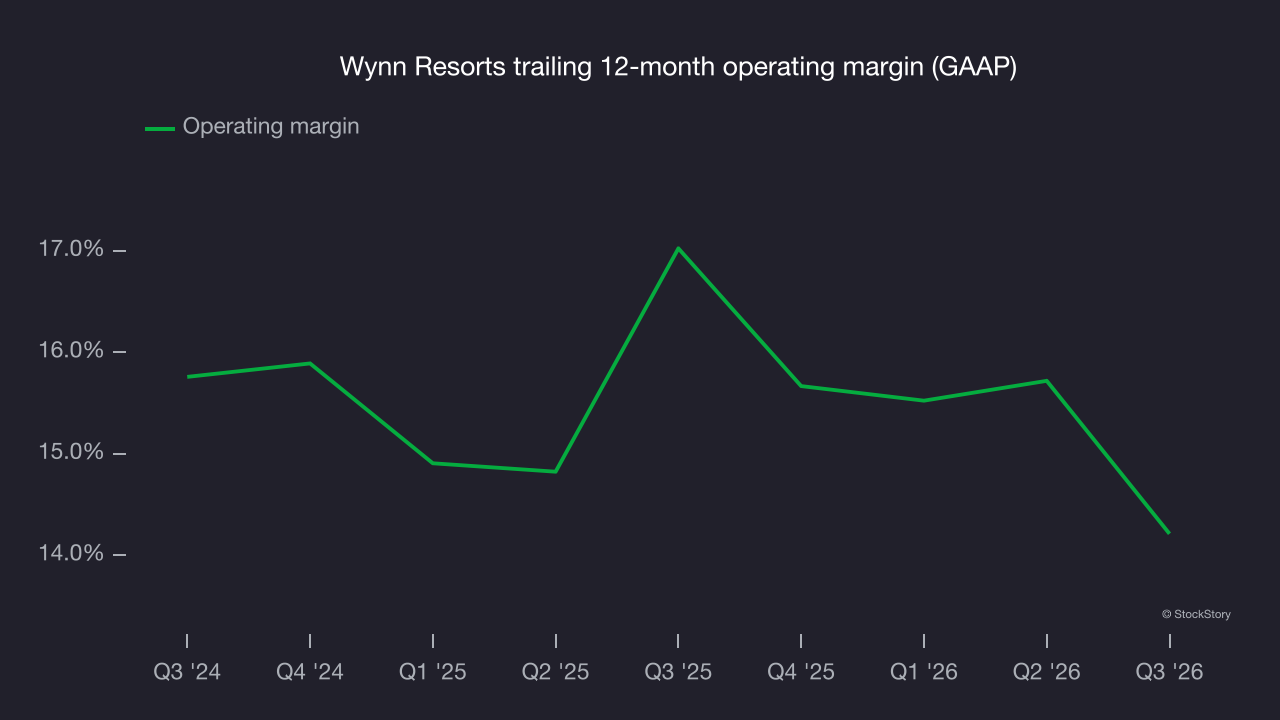
This quarter, Wynn Resorts generated an operating margin of 10.6%, down 6.4 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Wynn Resorts’s full-year EPS turned positive over the last five years. This is a positive development and marks a critical point for the company.
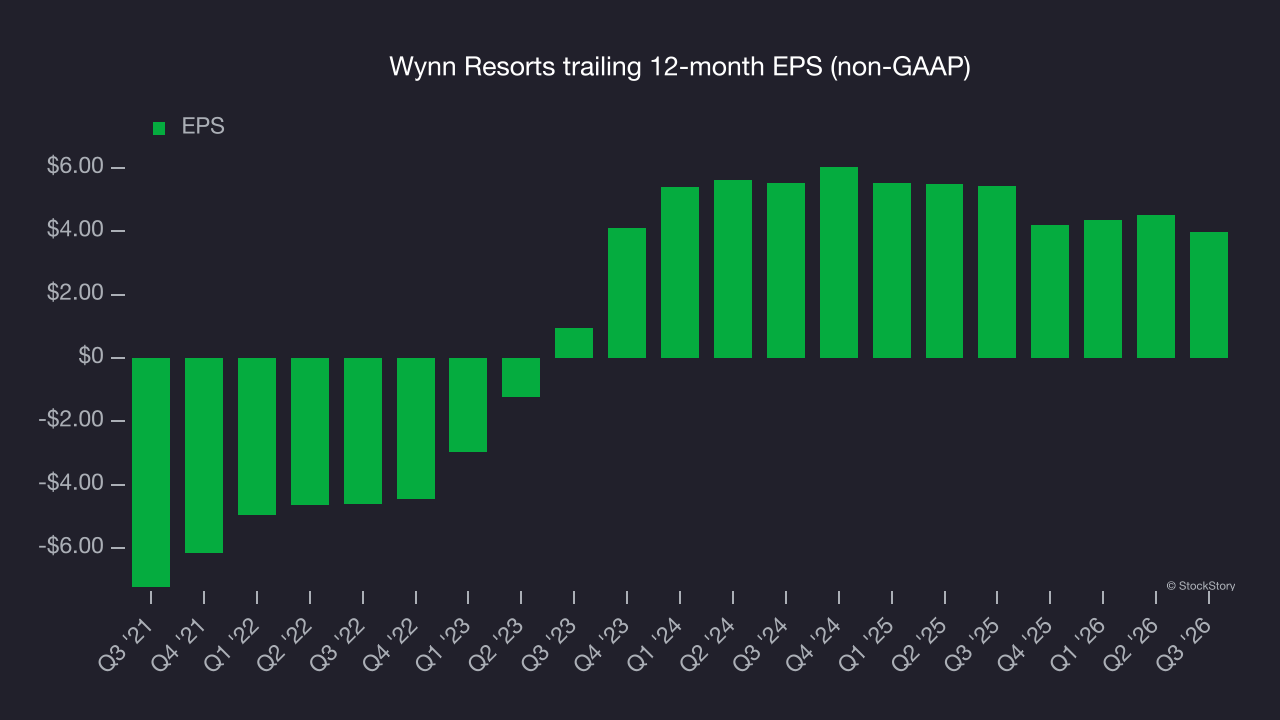
In Q3, Wynn Resorts reported adjusted EPS of $0.33, down from $0.86 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Wynn Resorts’s full-year EPS to grow 3.5% from $3.99 to $4.13, according to S&P.
Key takeaways from Wynn Resorts’s Q3 results
Wynn Resorts offered few positives in Q3: Both EPS and revenue fell short of Wall Street’s consensus estimates, making this a weaker quarter. Shares fell 4% to $76.10 immediately after the report.
Wynn Resorts’ latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so it’s worth examining whether the stock is a buy at the current price. That decision should take into account valuation, business quality and the latest earnings. For more on those factors, read our full research report here (it’s free).