Danaher currently trades at $204.89 per share and has shown little upside over the past six months, posting a middling return of 5%. The stock also fell short of the S&P 500’s 13.1% gain during that period.
Is now the time to buy Danaher, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Danaher Not Exciting?
We’re cautious about Danaher. Here are three reasons why DHR doesn’t excite us, plus one stock we’d rather own.
1. Slow Organic Growth Suggests Waning Demand In Core Business
We can better understand Research Tools & Consumables companies by analyzing their organic revenue. This metric gives visibility into Danaher’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Danaher’s organic revenue averaged 1.9% year-on-year growth. This performance was underwhelming and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 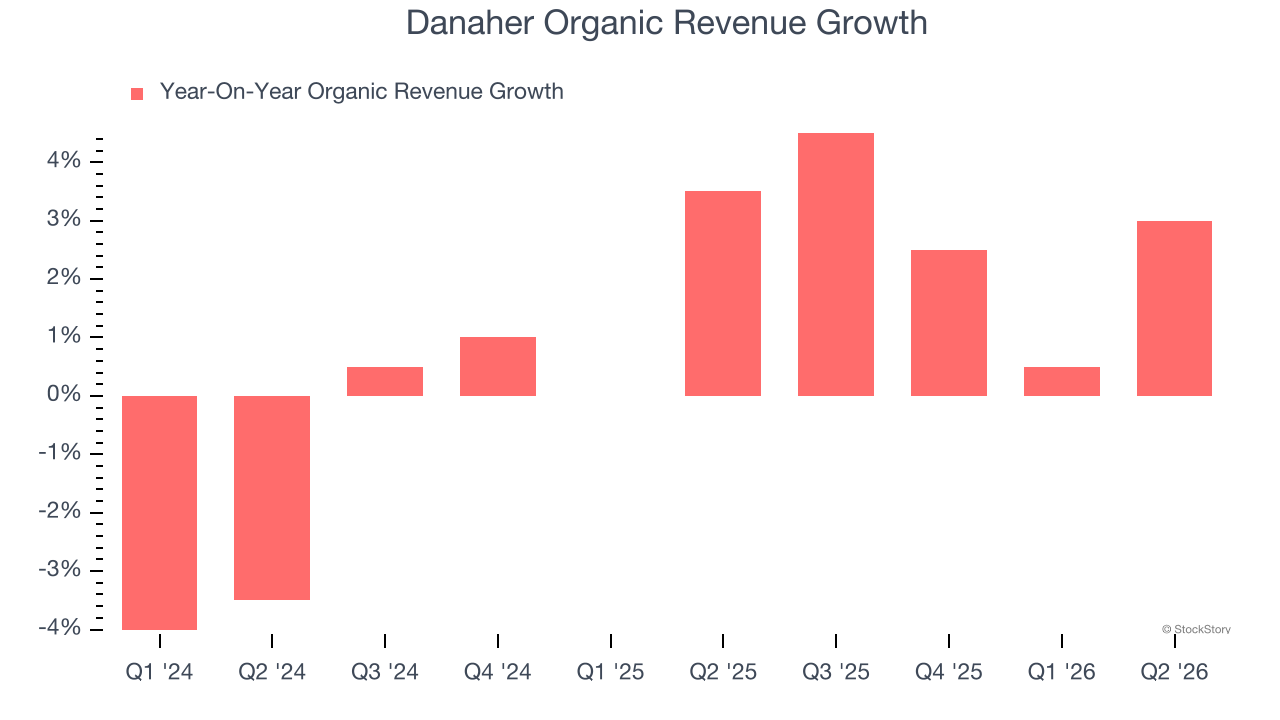
2. Shrinking Adjusted Operating Margin
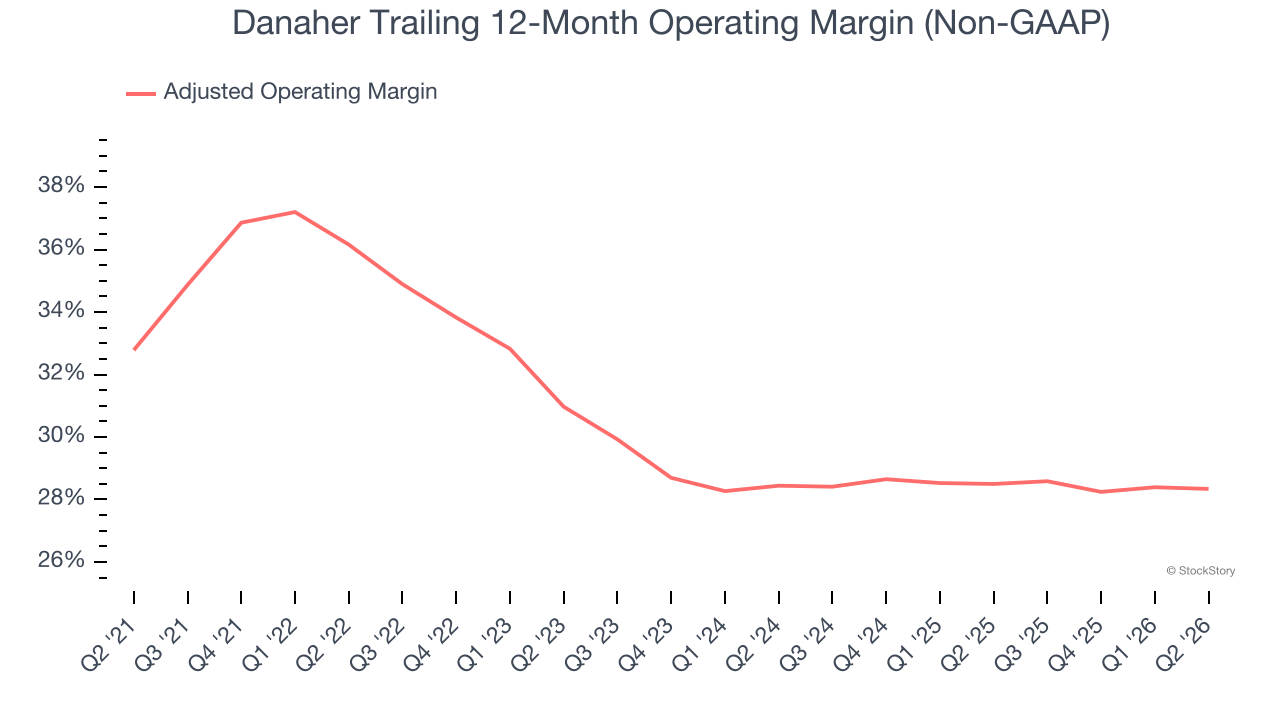
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt, and taxes.
Looking at the trend in its profitability, Danaher’s adjusted operating margin decreased by 7.8 percentage points over the last five years. Even though its historical margin was healthy, shareholders will want to see Danaher become more profitable in the future. Its adjusted operating margin for the trailing 12 months was 28.3%.
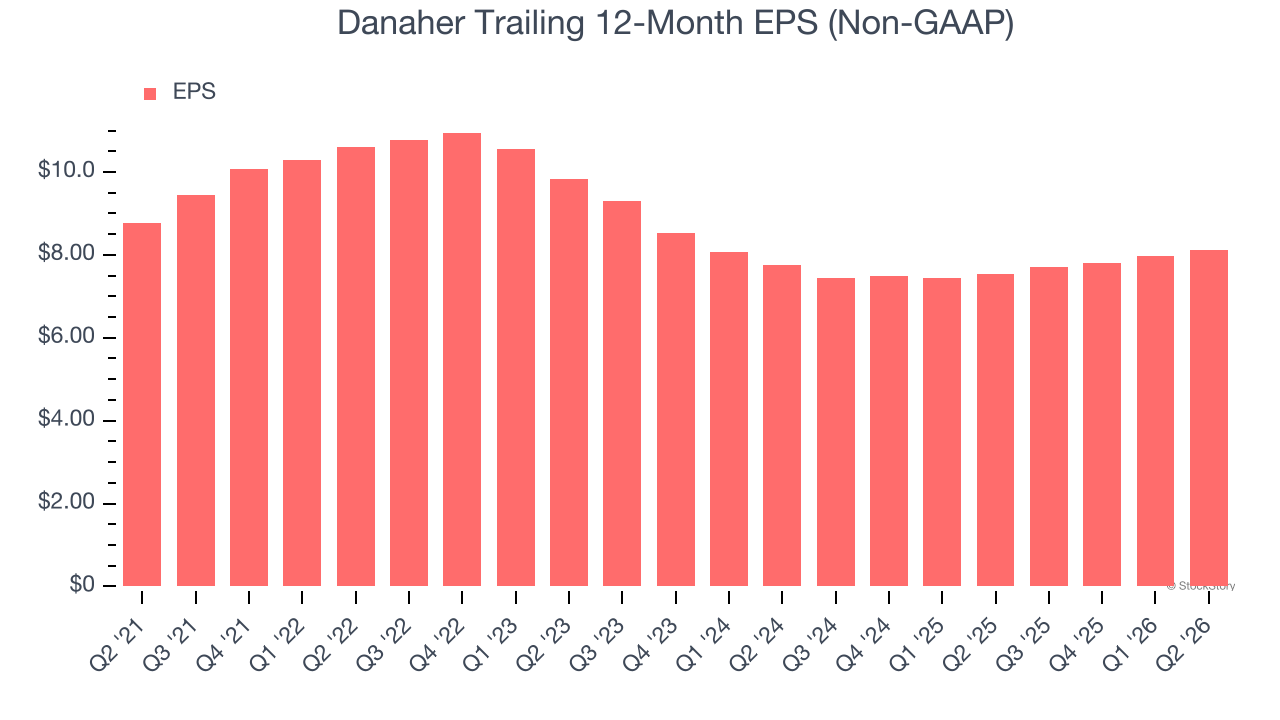
3. EPS Trending Down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Danaher, its EPS declined by 1.6% annually over the last five years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences.If the tide turns unexpectedly, Danaher’s low margin of safety could leave its stock price susceptible to large downswings.
Final Judgment
Danaher’s business quality ultimately falls short of our standards. With its shares lagging the market recently, the stock trades at 23.2× forward P/E (or $204.89 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. Let us point you toward one of Charlie Munger’s all-time favorite businesses.
Stocks We Like More Than Danaher
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.