Shareholders of The Marzetti Company would probably like to forget the past six months even happened. The stock dropped 32.5% and now trades at $103.28. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy The Marzetti Company, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is The Marzetti Company Not Exciting?
Even though the stock has become cheaper, we’re sitting this one out for now. Here are three reasons why there are better opportunities than MZTI, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
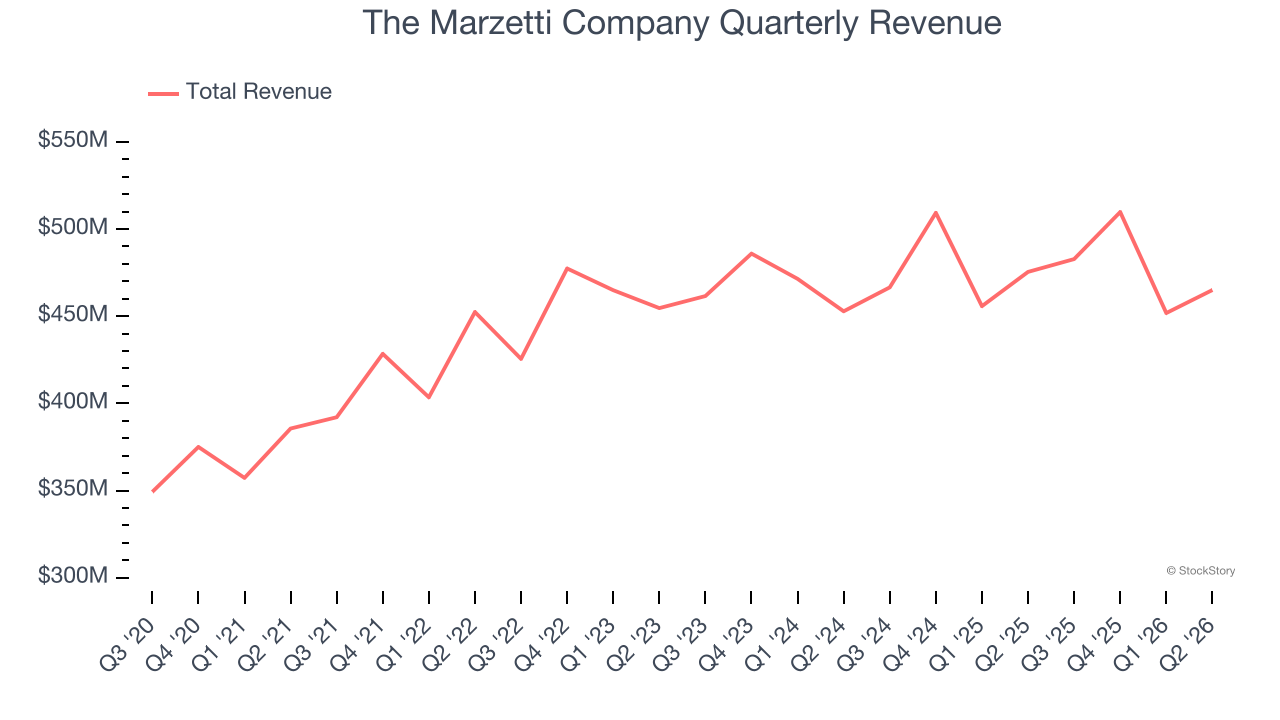
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last three years, The Marzetti Company grew its sales at a sluggish 1.6% compounded annual growth rate. This was below our standards.
2. Fewer Distribution Channels Limit Its Ceiling
With $1.91 billion in revenue over the past 12 months, The Marzetti Company is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
3. Low Gross Margin Reveals Weak Structural Profitability
At StockStory, we prefer high gross margin businesses because they indicate pricing power or differentiated products, giving the company a chance to generate higher operating profits.
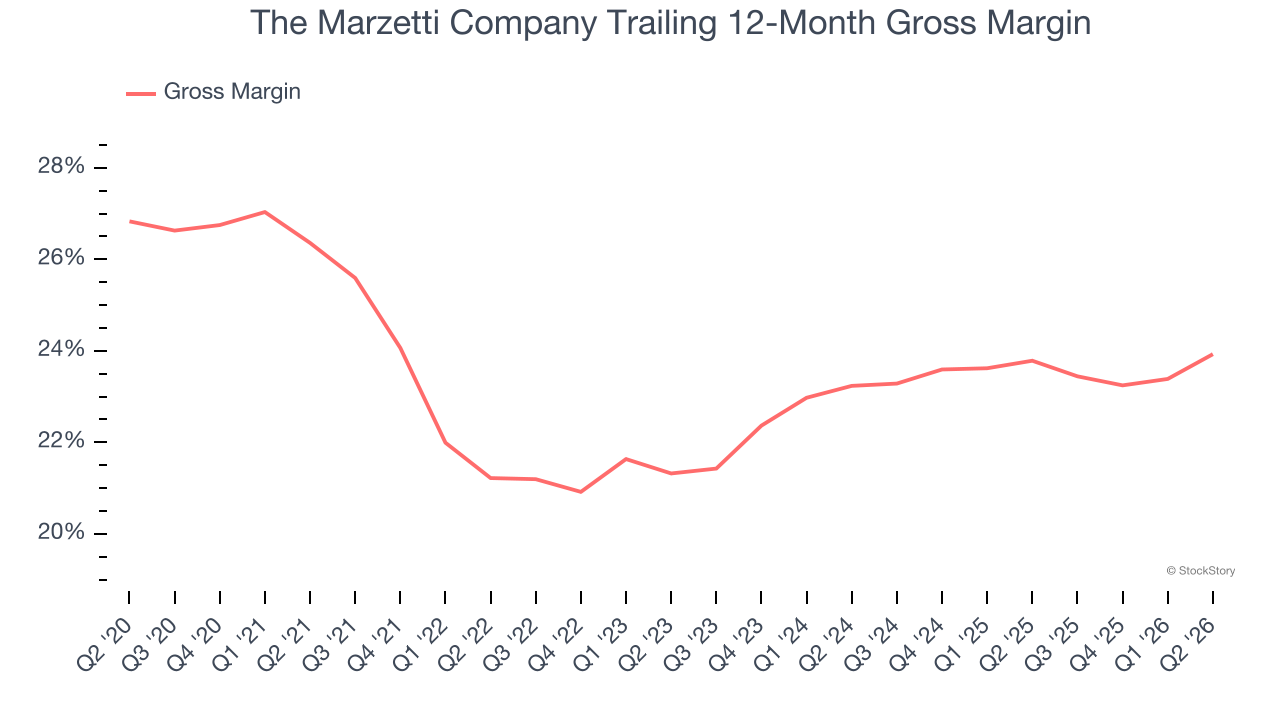
The Marzetti Company has bad unit economics for a consumer staples company, giving it less room to reinvest and develop new products. As you can see below, it averaged a 23.9% gross margin over the last two years. Said differently, for every $100 in revenue, a chunky $76.14 went towards paying for raw materials, production of goods, transportation, and distribution.
Final Judgment
The Marzetti Company isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 15.1× forward P/E (or $103.28 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better stocks to buy right now. Let us point you toward the most dominant software business in the world.
Stocks We Would Buy Instead of The Marzetti Company
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.