While the S&P 500 is up 12.7% since March 2026, Lake City Bank (currently trading at $60.54 per share) has lagged behind, posting a return of 6.7%. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in Lake City Bank, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Lake City Bank Not Exciting?
We’re cautious about Lake City Bank. Here are three reasons why LKFN doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions.
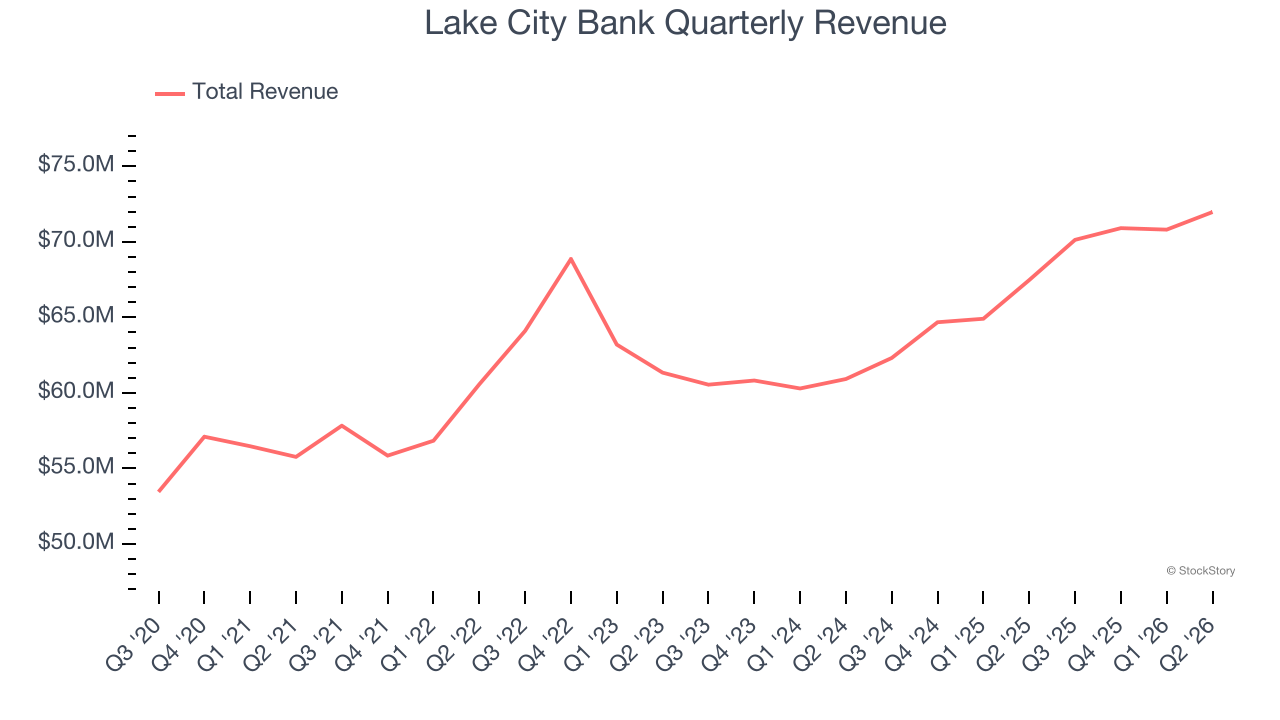
Regrettably, Lake City Bank’s revenue grew at a sluggish 5% compounded annual growth rate over the last five years. This fell short of our benchmark for the banking sector.
2. Net Interest Income Points to Soft Demand
While banks generate revenue from multiple sources, investors view net interest income as a cornerstone — its predictable, recurring characteristics stand in sharp contrast to the volatility of one-time fees.
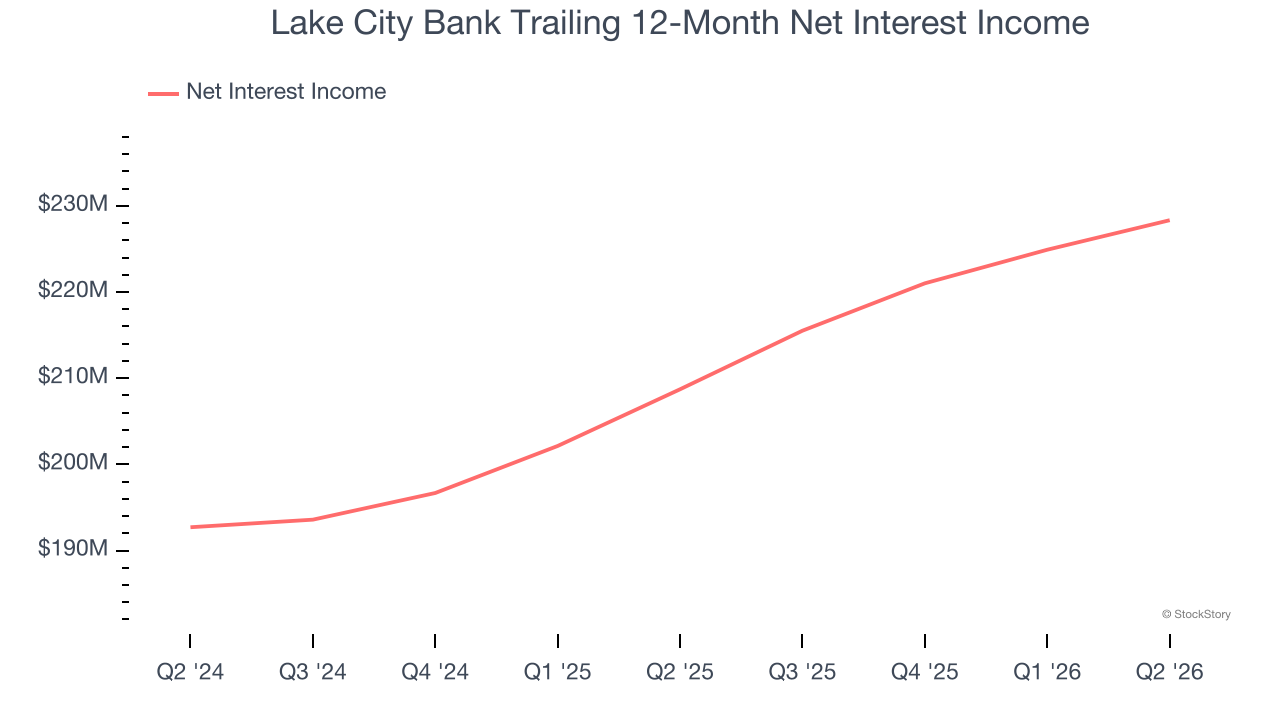
Lake City Bank’s net interest income has grown at a 5.8% annualized rate over the last five years, worse than the broader banking industry and in line with its total revenue. Its growth was driven by both an increase in its outstanding loans and net interest margin, which represents how much a bank earns in relation to its outstanding loan book.
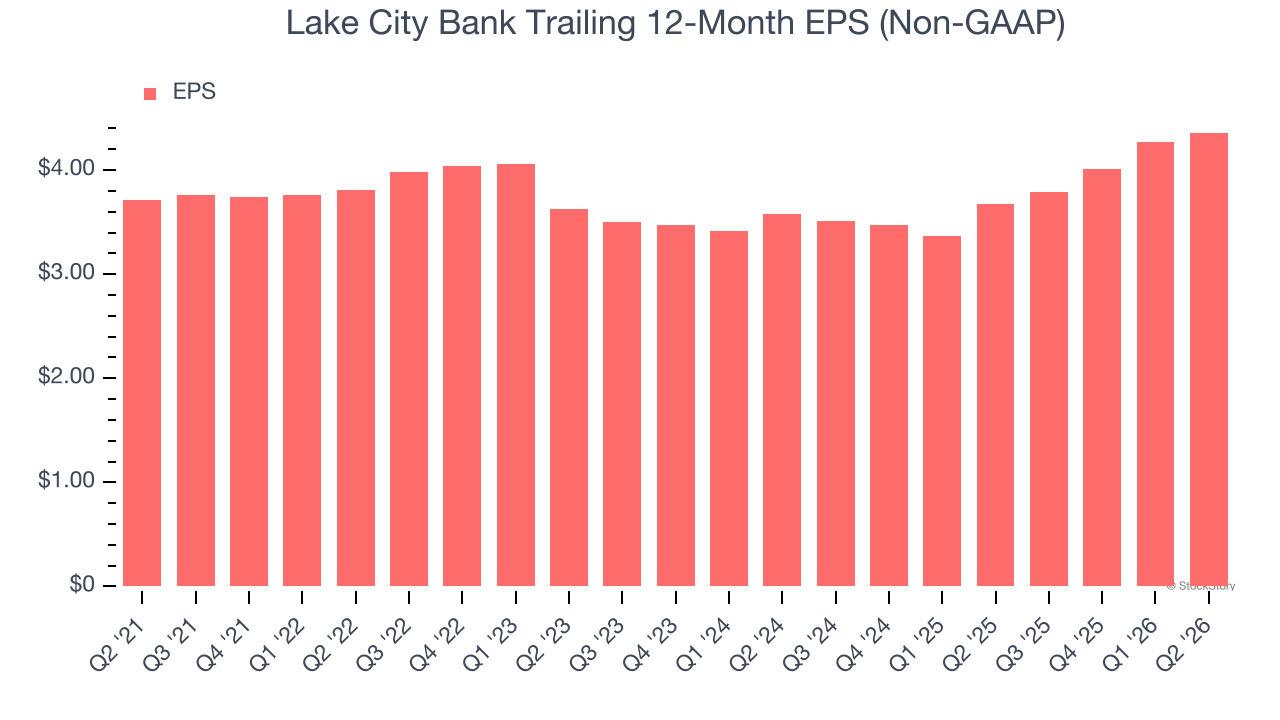
3. EPS Barely Growing
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Lake City Bank’s weak 3.3% annual EPS growth over the last five years aligns with its revenue performance. On the bright side, this tells us its incremental sales were profitable.
Final Judgment
Lake City Bank isn’t a terrible business, but it doesn’t pass our bar. With its shares trailing the market in recent months, the stock trades at 1.9× forward P/B (or $60.54 per share). This valuation tells us a lot of optimism is priced in - we think there are better opportunities elsewhere. Let us point you toward one of our top digital advertising picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.