Over the past six months, Costco’s stock price fell to $917.90. Shareholders have lost 8.4% of their capital, which is disappointing considering the S&P 500 has climbed by 14.2%. This may have investors wondering how to approach the situation.
Following the pullback, is now the time to buy COST? Find out in our full research report, it’s free.
Why Does Costco Spark Debate?
Designed to be a one-stop shop for the suburban consumer, Costco (NASDAQ: COST) is a membership-only retail chain that sells groceries, apparel, toys, and household items, often in bulk quantities.
Two Positive Attributes:
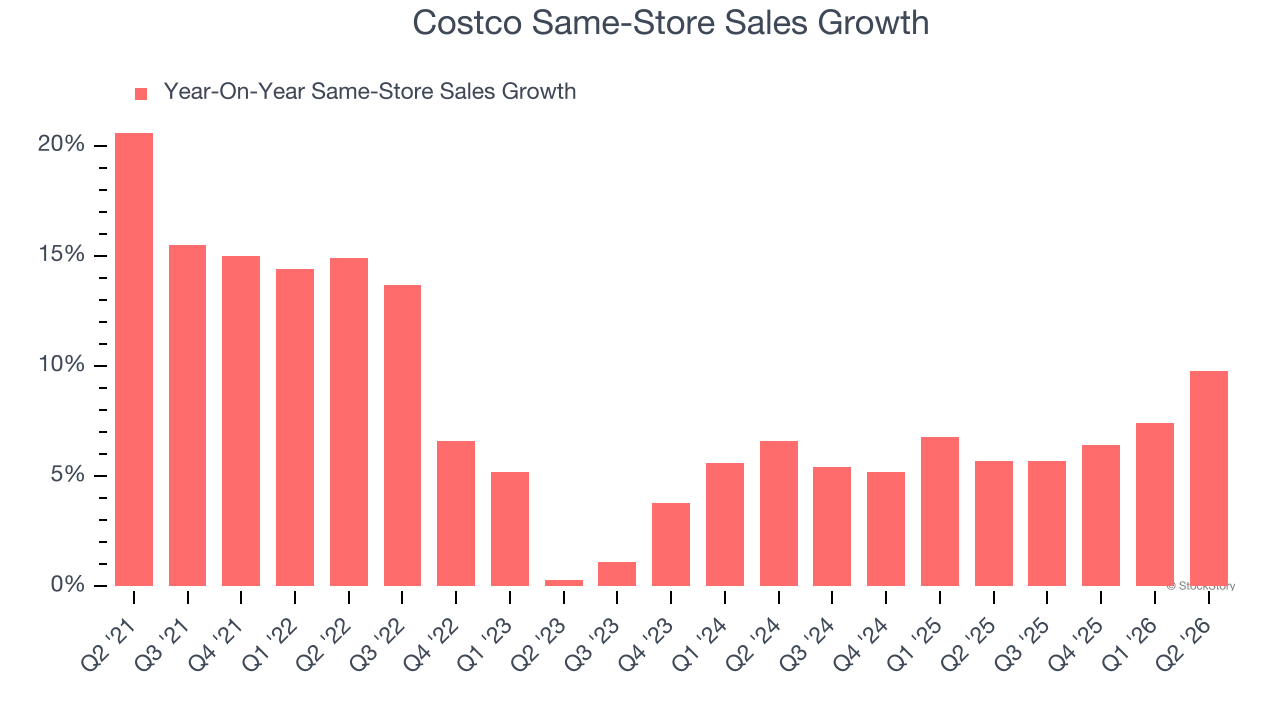
1. Surging Same-Store Sales Show Increasing Demand
Same-store sales is a key performance indicator used to measure organic growth at brick-and-mortar shops for at least a year.
Costco has been one of the most successful retailers over the last two years thanks to skyrocketing demand within its existing locations. On average, the company has posted exceptional year-on-year same-store sales growth of 6.6%.
2. Economies of Scale Give It Negotiating Leverage with Suppliers
With $293.6 billion in revenue over the past 12 months, Costco is a behemoth in the consumer retail sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because there is only so much real estate to build new stores, placing a ceiling on its growth. For Costco to boost its sales, it likely needs to adjust its prices or lean into foreign markets.
One Reason to Be Careful:
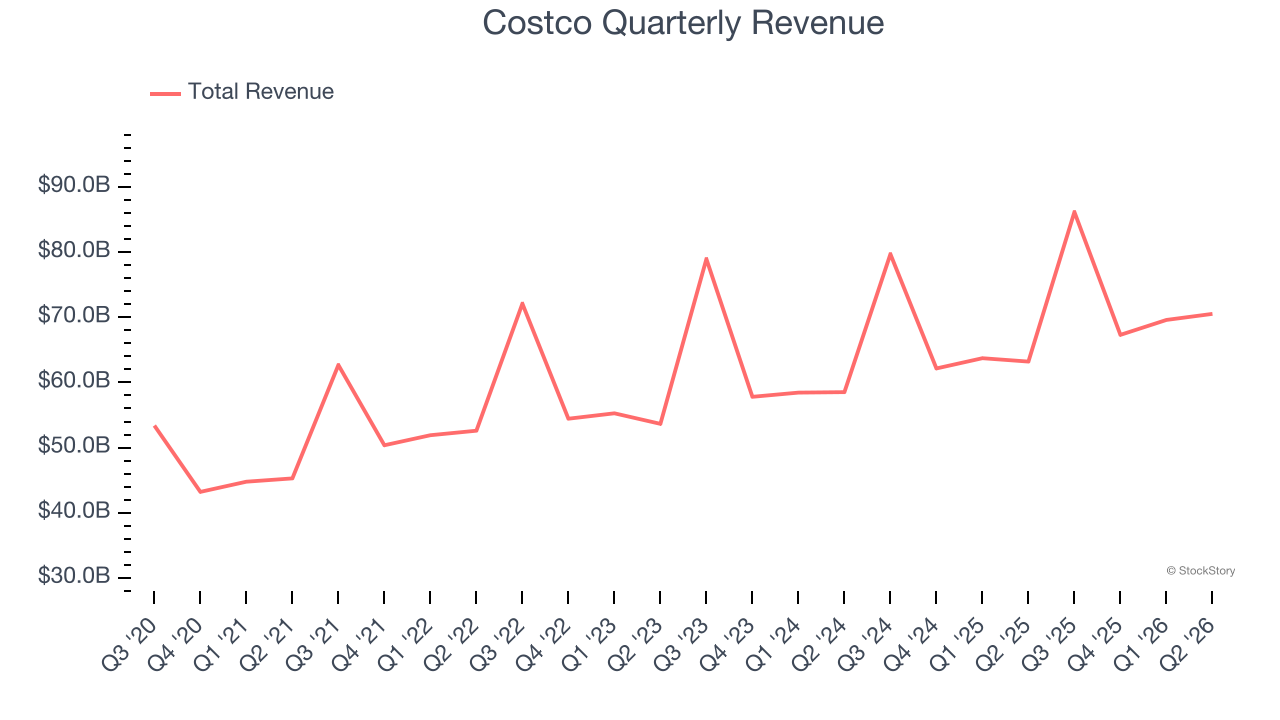
Long-Term Revenue Growth Disappoints
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, Costco’s 7.6% annualized revenue growth over the last three years was mediocre. This wasn’t a great result compared to the rest of the consumer retail sector, but there are still things to like about Costco.
Final Judgment
Costco’s positive characteristics outweigh the negatives. After the recent drawdown, the stock trades at 41.4× forward P/E (or $917.90 per share). Is now the right time to buy? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Costco
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.