Over the past six months, Commerce has been a great trade, beating the S&P 500 by 21.1%. Its stock price has climbed to $3.70, representing a healthy 35.3% increase. This run-up might have investors contemplating their next move.
Is there a buying opportunity in Commerce, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Commerce Will Underperform?
Despite the momentum, we’re cautious about Commerce. Here are three reasons why CMRC doesn’t excite us, plus one stock we’d rather own.
1. Weak Billings Point to Soft Demand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Commerce’s billings came in at $85.43 million in Q2, and over the last four quarters, its year-on-year growth averaged 3.1%. This performance was underwhelming and suggests that increasing competition is causing challenges in acquiring/retaining customers. 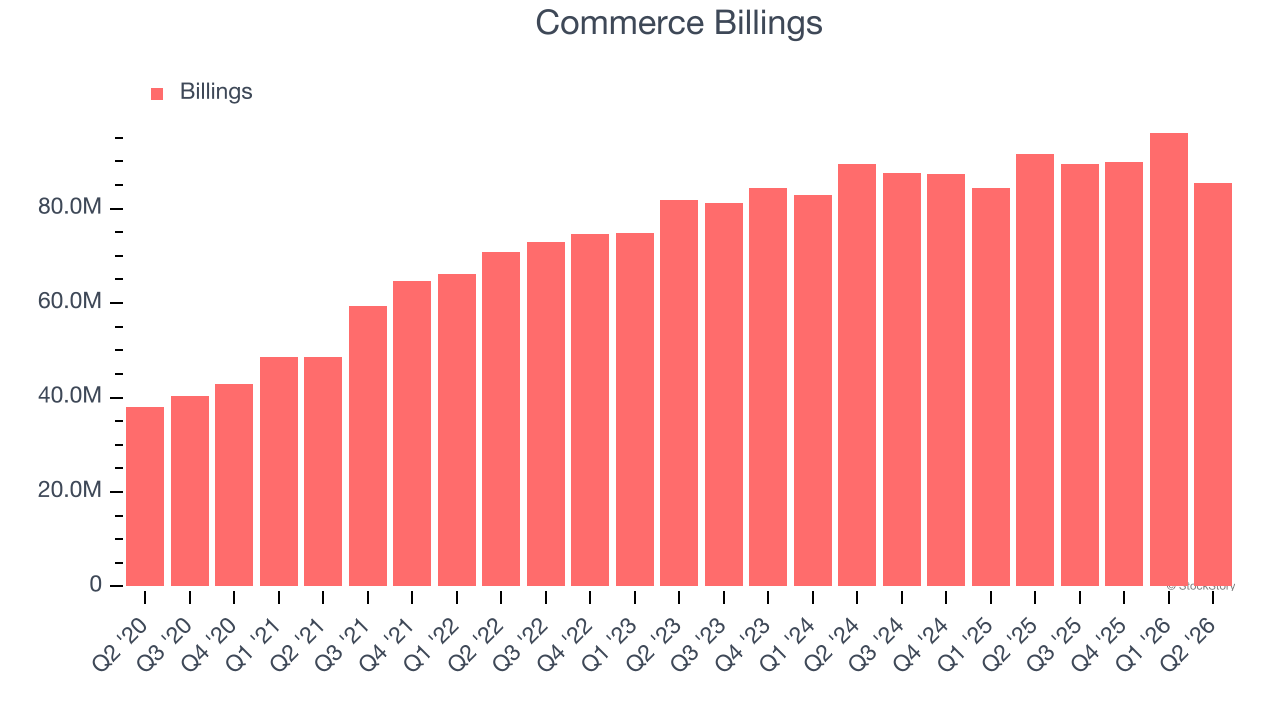
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Commerce’s revenue to drop by 3.2%, a decrease from its 14.2% annualized growth for the past five years. This projection doesn’t excite us and suggests its products and services will face some demand challenges.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
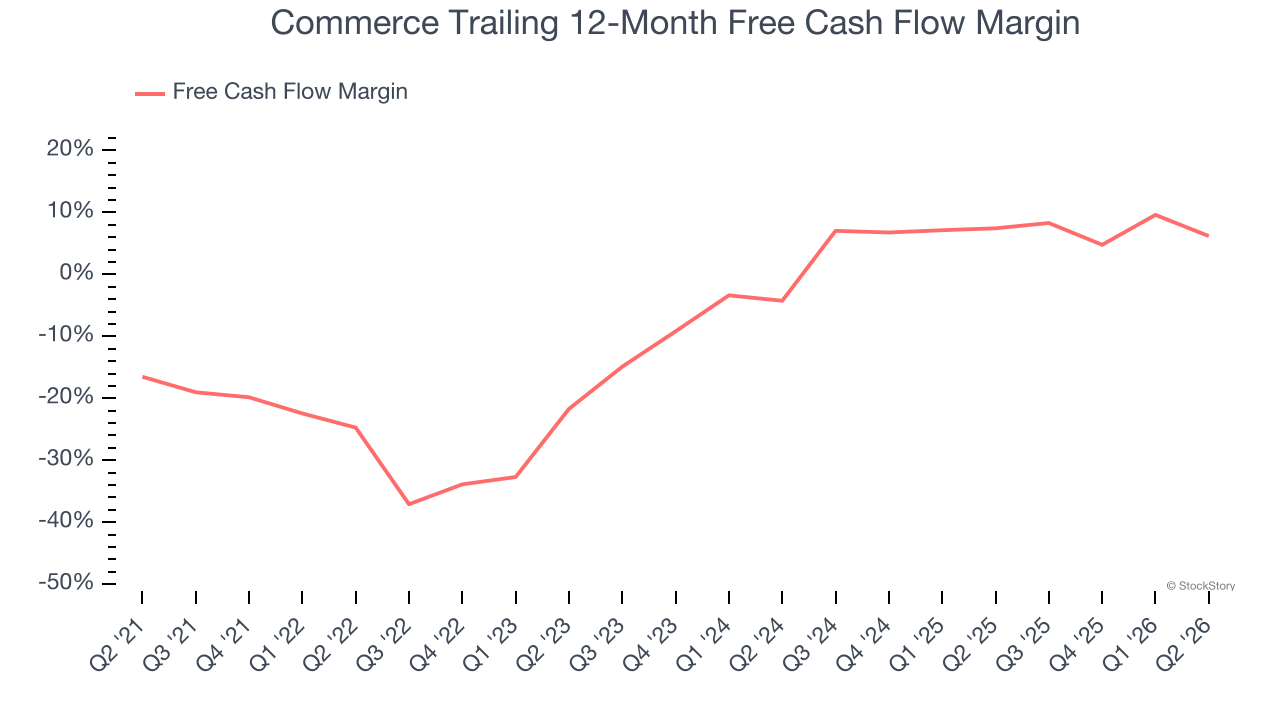
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Commerce has shown weak cash profitability relative to peers over the last year, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 6.2%, below what we’d expect for a software business.
Final Judgment
We see the value of companies addressing major business pain points, but in the case of Commerce, we’re out. With its shares outperforming the market lately, the stock trades at 0.9× forward price-to-sales (or $3.70 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are more exciting stocks to buy at the moment. We’d recommend looking at a top digital advertising platform riding the creator economy.
Stocks We Like More Than Commerce
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.