Donaldson currently trades at $87.94 per share and has shown little upside over the past six months, posting a middling return of 2.9%. The stock also fell short of the S&P 500’s 14.2% gain during that period.
Is now the time to buy Donaldson, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Donaldson Not Exciting?
We’re cautious about Donaldson. Here are three reasons why DCI doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
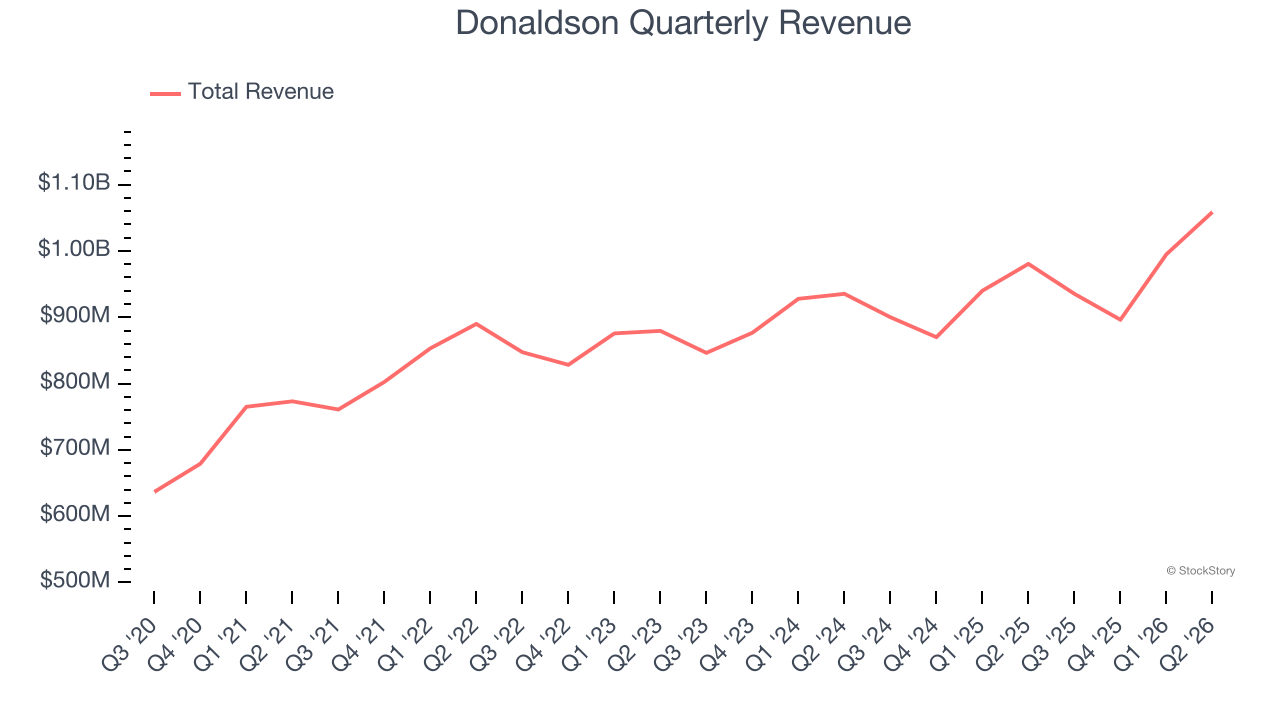
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Regrettably, Donaldson’s sales grew at a mediocre 6.4% compounded annual growth rate over the last five years. This fell short of our benchmark for the industrials sector.
2. Weak Constant Currency Growth Points to Soft Demand
Investors interested in Gas and Liquid Handling companies should track constant currency revenue in addition to reported revenue. This metric excludes currency movements, which are outside of Donaldson’s control and are not indicative of underlying demand.
Over the last two years, Donaldson’s constant currency revenue averaged 3% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 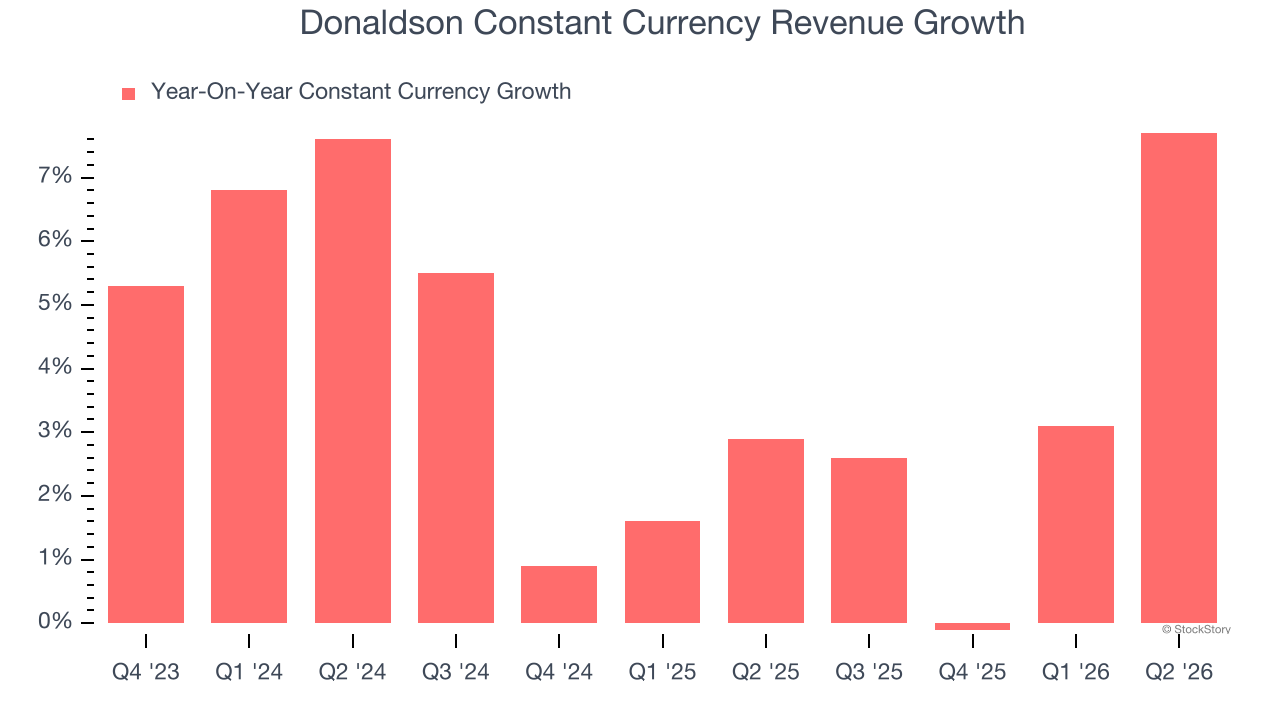
3. New Investments Fail to Bear Fruit as ROIC Declines
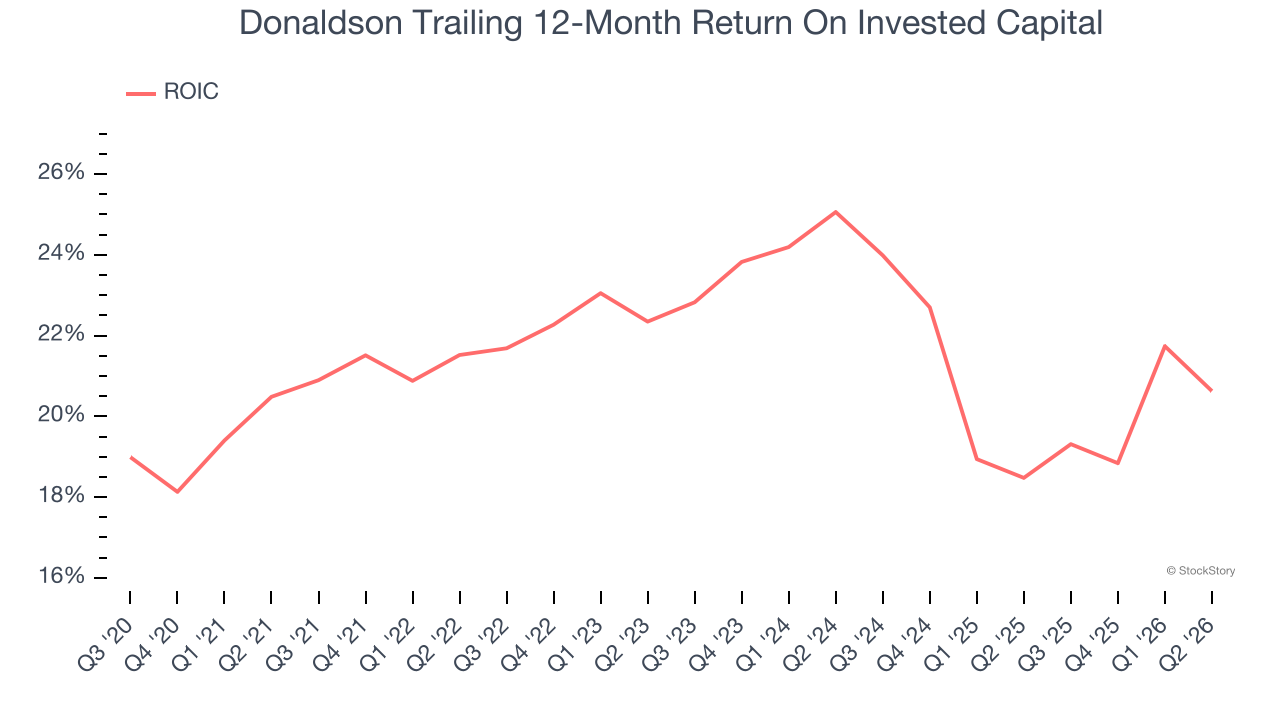
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Unfortunately, Donaldson’s ROIC averaged 2.4 percentage point decreases each year over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Donaldson isn’t a terrible business, but it doesn’t pass our quality test. With its shares underperforming the market lately, the stock trades at 20.7× forward P/E (or $87.94 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.