Over the past six months, BKV’s stock price fell to $23.84. Shareholders have lost 16.7% of their capital, which is disappointing considering the S&P 500 has climbed by 14.2%. This might have investors contemplating their next move.
Is now the time to buy BKV, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think BKV Will Underperform?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons you should be careful with BKV, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
The scale of a company’s revenue base is an important lens through which to view the topline, as it signals whether a producer has gone from a vulnerable commodity taker into a durable operating platform. Larger producers generate revenue across many wells, pads, takeaway routes, and geographies rather than relying on a single field or drilling program.
BKV’s $1.51 billion of revenue in the last year is pretty small for the industry, suggesting the company hasn’t hit a level of diversification where investors can sleep easy at night.
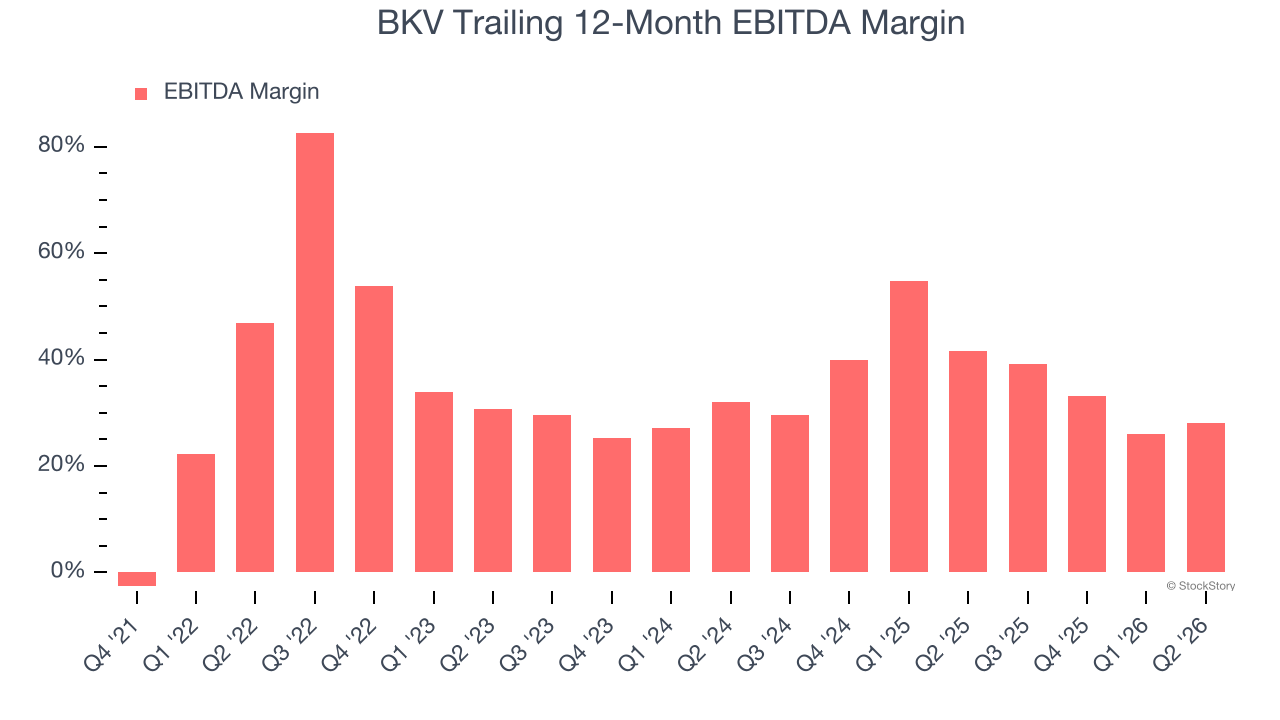
2. Shrinking EBITDA Margin
Adjusted EBITDA margin is an important measure of profitability for the sector and accounts for the gross margins and operating costs mentioned previously. Unlike operating margin, it is not distorted by accounting conventions around reserves, drilling costs, and assumptions on commodity consumption from the well or basin. Adjusted EBITDA highlights the economic reality of how much cash the rock produces before the capital structure (debt service) and the drilling budget (capex) are considered.
Analyzing the trend in its profitability, BKV’s EBITDA margin decreased by 18.8 percentage points over the last year. Even though its historical margin was healthy, shareholders will want to see BKV become more profitable in the future. Its EBITDA margin for the trailing 12 months was 28.1%.
3. Breakeven Free Cash Flow Limits Reinvestment Potential
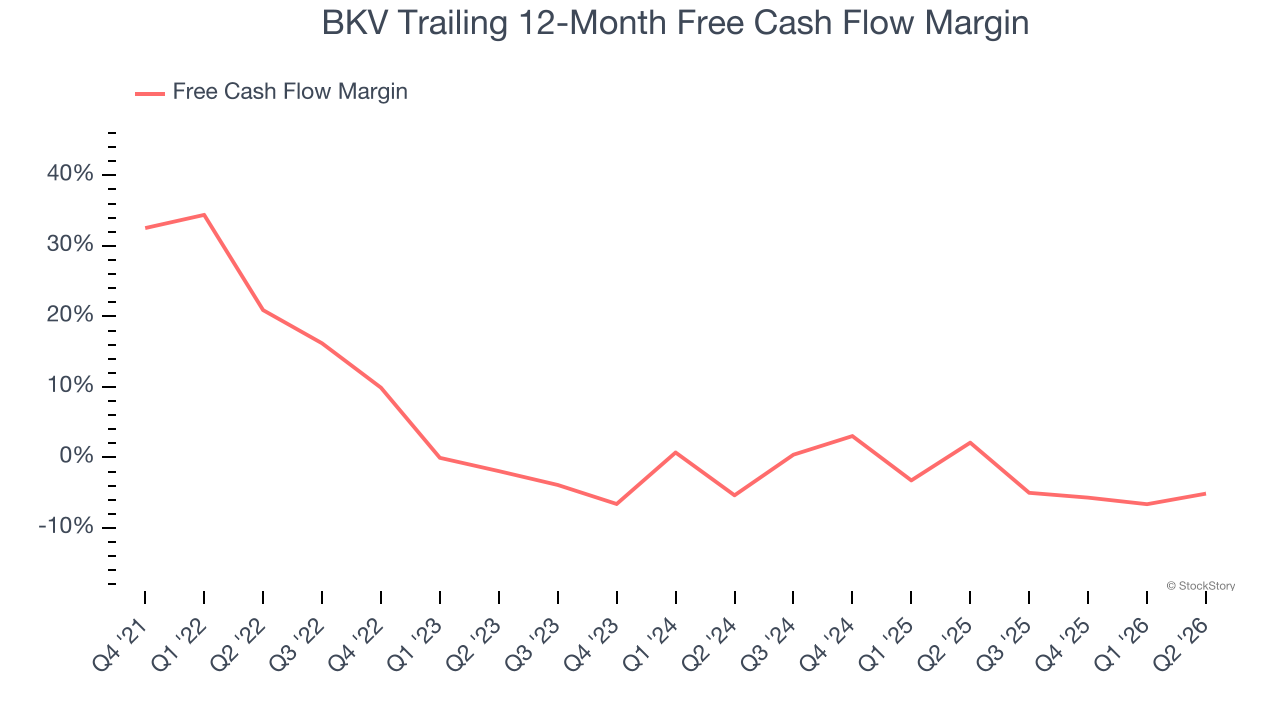
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
BKV broke even from a free cash flow perspective over the last five years, giving the company limited opportunities to return capital to shareholders.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of BKV, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 18.9× forward P/E (or $23.84 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better stocks to buy right now. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of BKV
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.