Since September 2021, the S&P 500 has delivered a total return of 70.6%. But one standout stock has more than doubled the market - over the past five years, Williams-Sonoma has surged 149% to $229.53 per share. Its momentum hasn’t stopped as it’s also gained 25.9% in the last six months thanks to its solid quarterly results, beating the S&P by 11.6%.
Is there a buying opportunity in Williams-Sonoma, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Williams-Sonoma Not Exciting?
We’re glad investors have benefited from the price increase, but we don’t have much confidence in Williams-Sonoma. Here are three reasons we avoid WSM, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
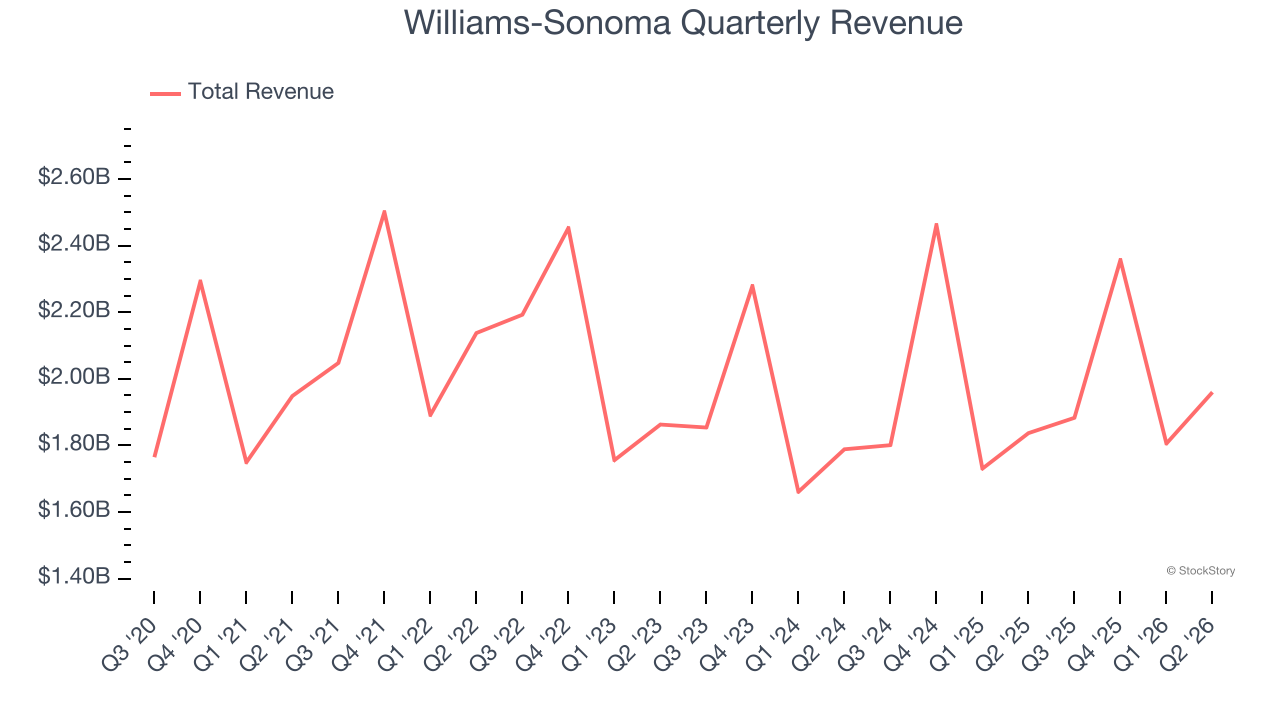
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Williams-Sonoma’s demand was weak over the last three years as its sales fell at a 1.1% annual rate. This was below our standards and is a sign of lacking business quality.
2. Stores Are Closing, a Headwind for Revenue
A retailer’s store count often determines how much revenue it can generate.
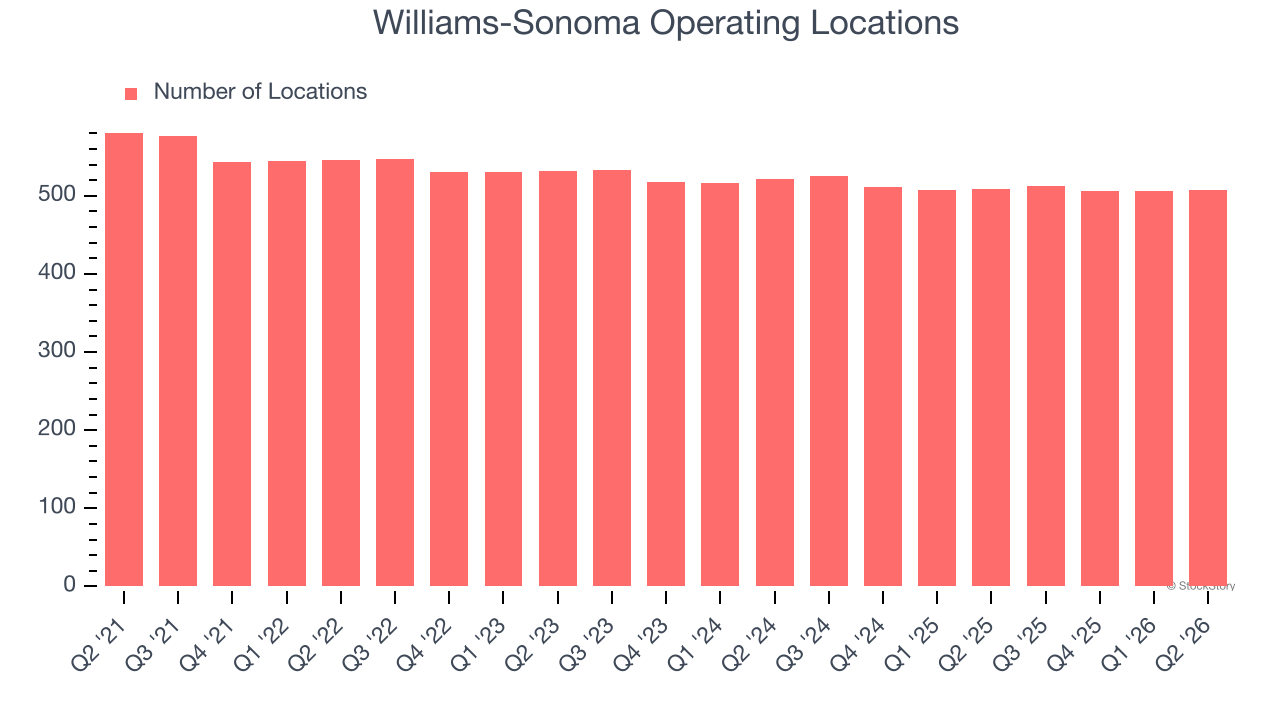
Williams-Sonoma listed 508 locations in the latest quarter and has generally closed its stores over the last two years, averaging 1.3% annual declines.
When a retailer shutters stores, it usually means that brick-and-mortar demand is less than supply, and it is responding by closing underperforming locations to improve profitability.
3. EPS Barely Growing
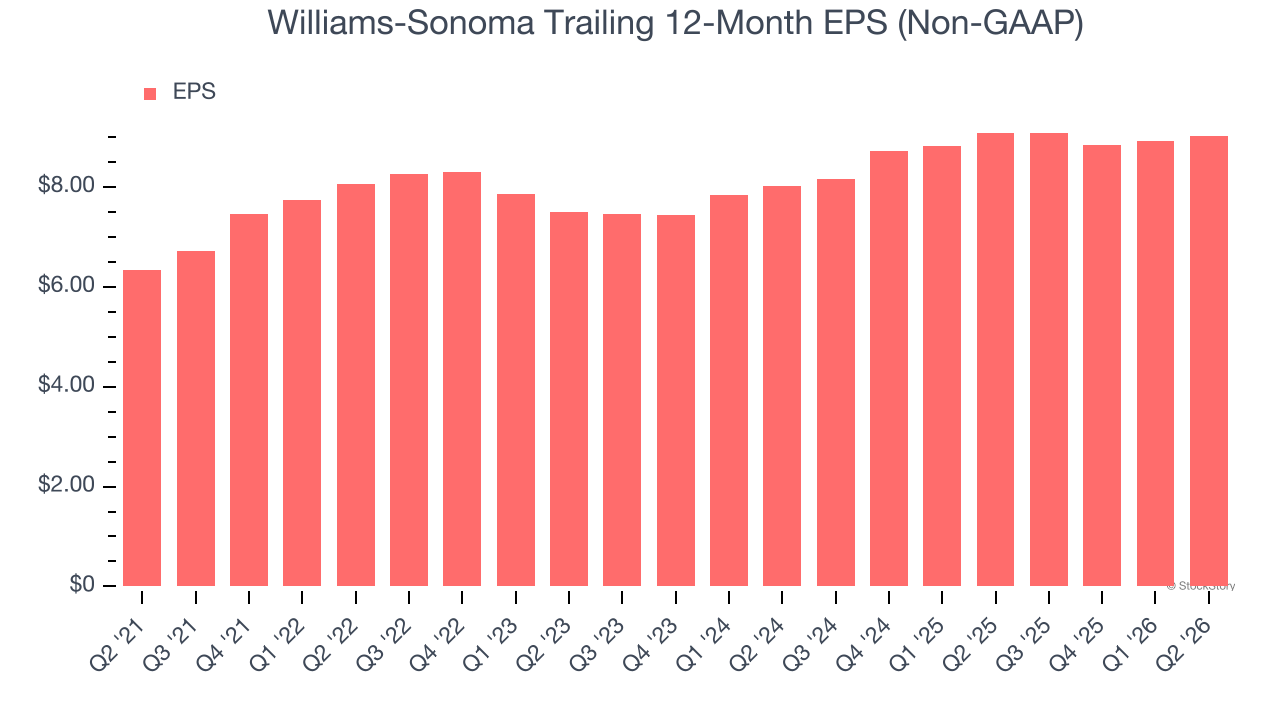
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Williams-Sonoma’s EPS grew at 6.4% compounded annual growth rate over the last three years. On the bright side, this performance was better than its 1.1% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
Final Judgment
Williams-Sonoma isn’t a terrible business, but it isn’t one of our picks. With its shares outperforming the market lately, the stock trades at 22.8× forward P/E (or $229.53 per share). Beauty is in the eye of the beholder, but we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. Let us point you toward the most entrenched endpoint security platform on the market.
Stocks We Would Buy Instead of Williams-Sonoma
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.