Over the past six months, Antero Resources’s shares (currently trading at $38.43) have posted a disappointing 6.3% loss, well below the S&P 500’s 14.2% gain. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Antero Resources, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Antero Resources Not Exciting?
Even though the stock has become cheaper, we’re passing on Antero Resources for now. Here are two reasons you should be careful with AR, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
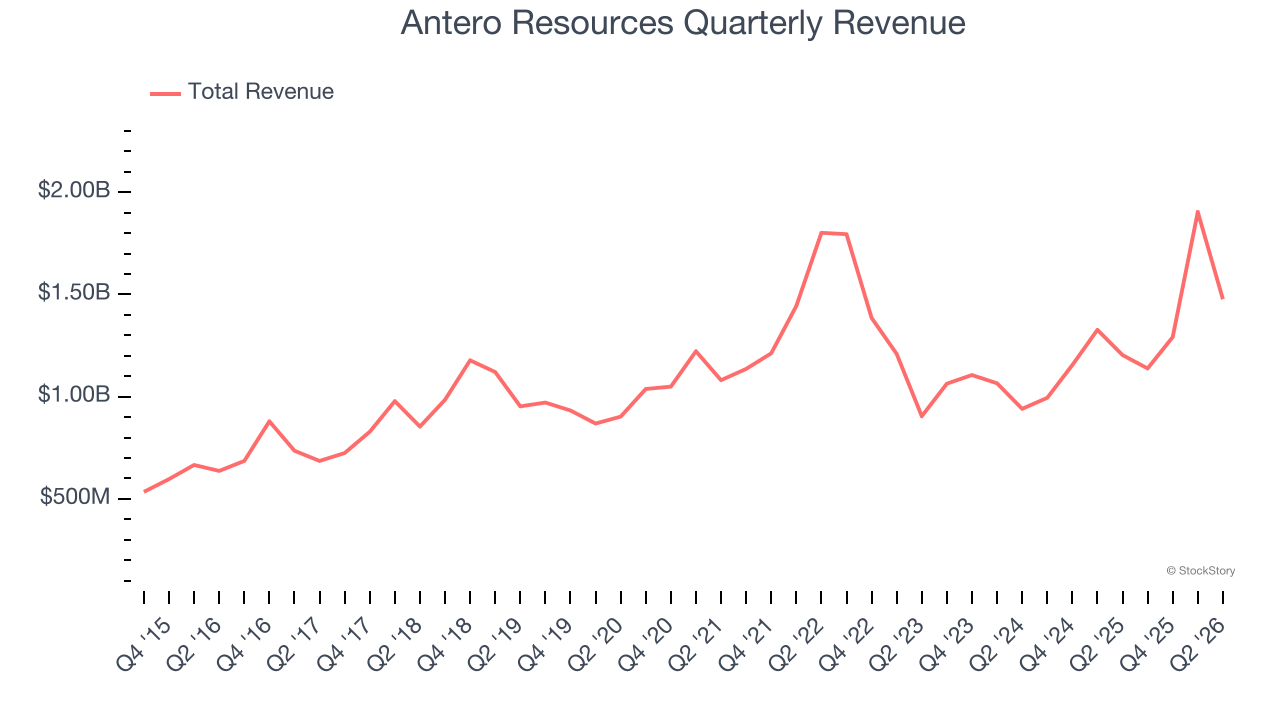
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Unfortunately, Antero Resources’s 5.8% annualized revenue growth over the last five years was sluggish. This was below our standard for the energy upstream and integrated energy sector.
2. Shrinking EBITDA Margin
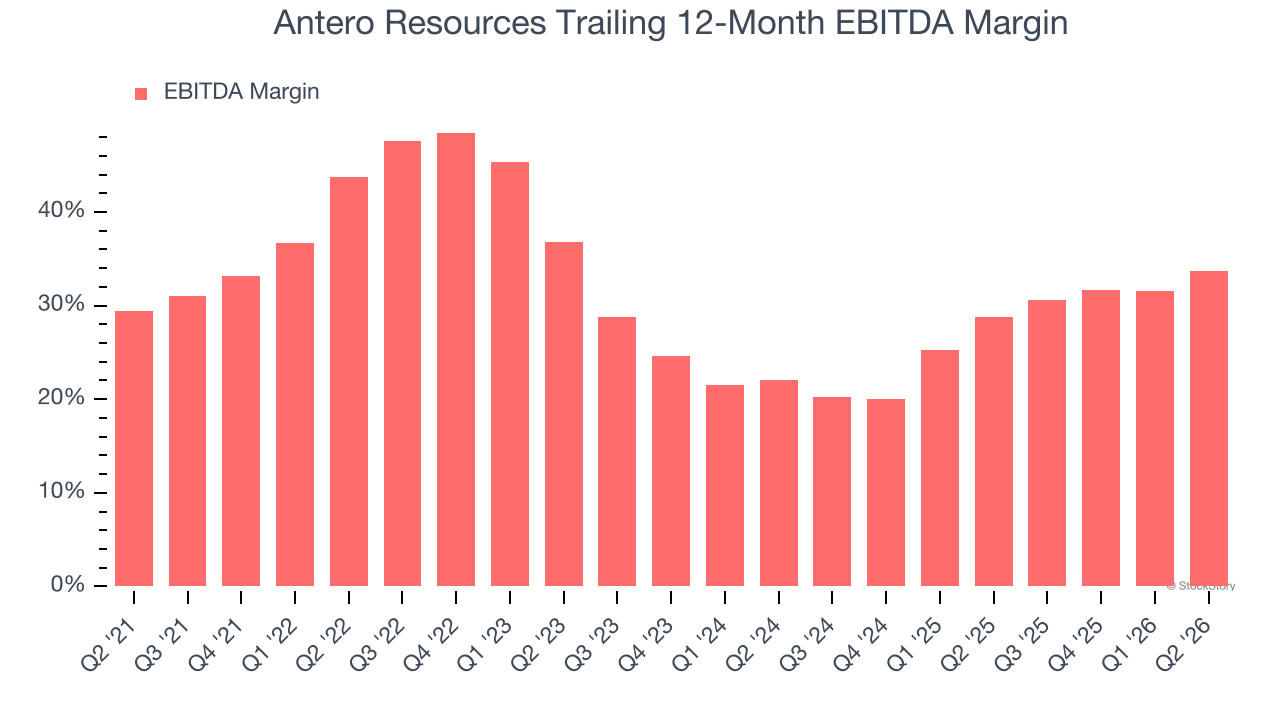
Adjusted EBITDA margin captures the true operating profitability of an energy producer by removing accounting noise around depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Looking at the trend in its profitability, Antero Resources’s EBITDA margin decreased by 10 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its EBITDA margin for the trailing 12 months was 33.7%.
Final Judgment
Antero Resources’s business quality ultimately falls short of our standards. After the recent drawdown, the stock trades at 9.3× forward P/E (or $38.43 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at our favorite semiconductor picks and shovels play.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.