As the Q2 earnings season wraps, let’s dig into this quarter’s best and worst performers in the oilfield services industry, including NOV (NYSE: NOV) and its peers.
Oilfield services companies provide equipment, technology, and services enabling exploration and production activities, including drilling, completion, well intervention, and reservoir evaluation. Their fortunes closely track upstream capital spending cycles. Tailwinds include increased drilling activity during favorable commodity environments, demand for efficiency-enhancing technologies, and growing offshore and unconventional resource development. Headwinds include significant revenue volatility tied to oil and gas price swings and producer spending discipline. Intense competition pressures pricing and margins, while the energy transition may structurally reduce long-term demand. Workforce availability and technological disruption require continuous adaptation.
The 25 oilfield services stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 4.6%.
Thankfully, share prices of the companies have been resilient as they are up 6.5% on average since the latest earnings results.
NOV (NYSE: NOV)
With roots stretching back to 1862 when it began making equipment for early oil fields, NOV (NYSE: NOV) manufactures drilling rigs, drill bits, pumps, and other equipment used to drill oil and gas wells.
NOV reported revenues of $2.13 billion, down 2.5% year on year. This print exceeded analysts’ expectations by 2.4%. Overall, it was a stunning quarter for the company with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
“NOV’s second quarter results reflect outstanding execution by our team in a market that is demonstrating significantly improved underlying industry fundamentals,” said Jose Bayardo, Chairman, President, and CEO.
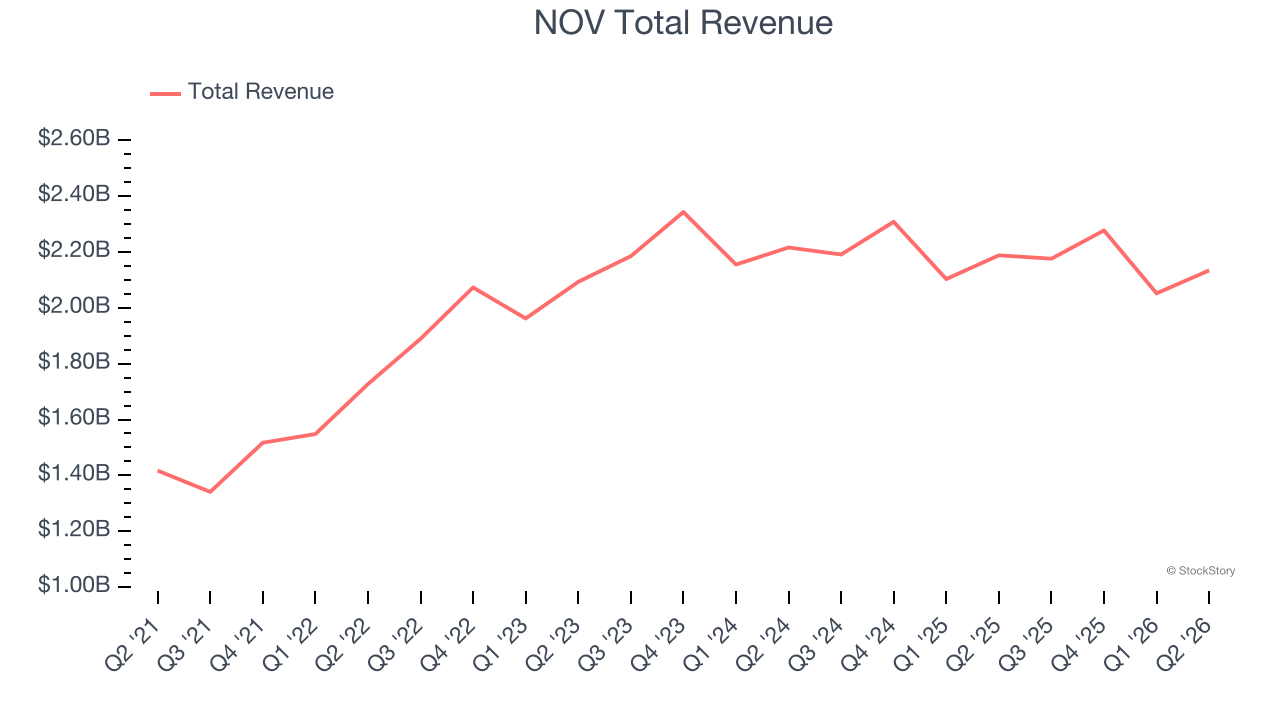
Interestingly, the stock is up 3.4% since reporting and currently trades at $20.49.
Is now the time to buy NOV? Access our full analysis of the earnings results here, it’s free.
Best Q2: Valaris (NYSE: VAL)
Operating the world's largest fleet of offshore drilling rigs across six continents, Valaris (NYSE: VAL) provides offshore drilling rigs and crews to oil and gas companies exploring and producing in deep waters and shallow seas.
Valaris reported revenues of $539.2 million, down 12.4% year on year, outperforming analysts’ expectations by 8%. The business had an incredible quarter with a beat of analysts’ EPS estimates.
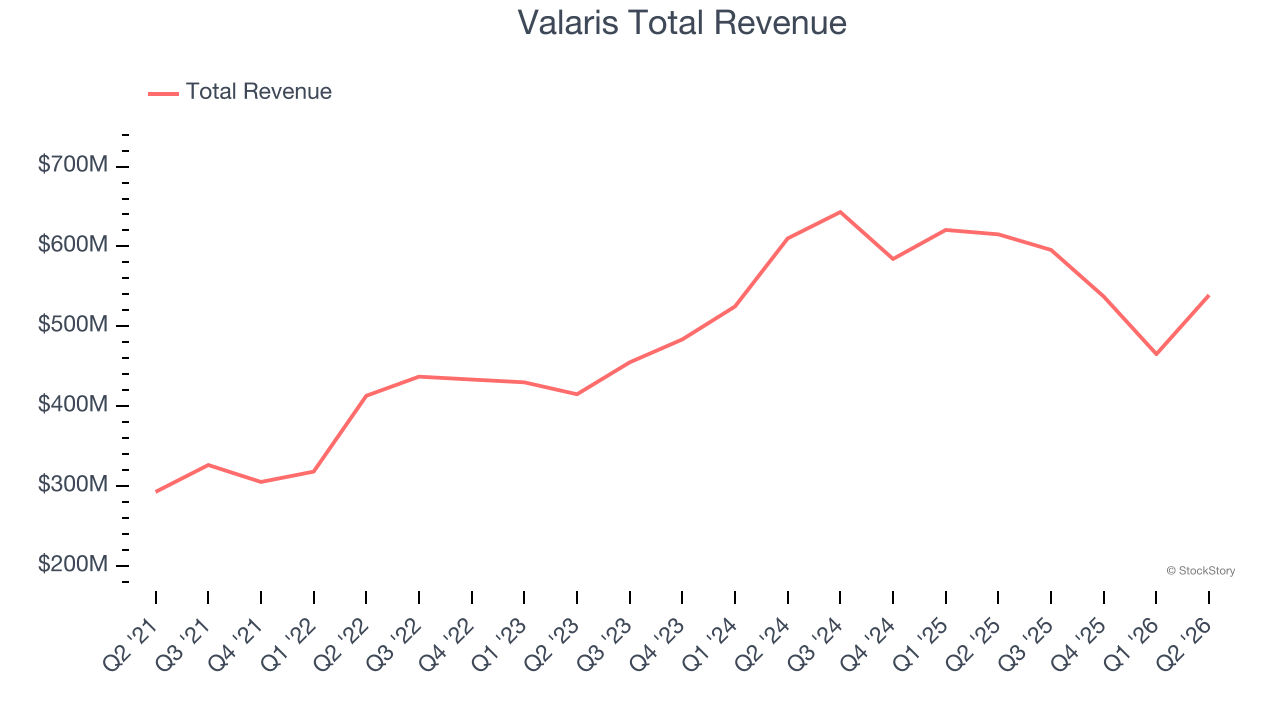
The market seems happy with the results as the stock is up 5.6% since reporting. It currently trades at $81.26.
Is now the time to buy Valaris? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: ProPetro (NYSE: PUMP)
Operating exclusively in the Permian Basin—one of America's most prolific oil-producing regions—ProPetro (NYSE: PUMP) provides hydraulic fracturing services that pump high-pressure fluid and sand into oil wells to release trapped hydrocarbons.
ProPetro reported revenues of $305.8 million, down 6.2% year on year, falling short of analysts’ expectations by 1.6%. It was a disappointing quarter as it posted a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
As expected, the stock is down 1.3% since the results and currently trades at $10.52.
Read our full analysis of ProPetro’s results here.
RPC (NYSE: RES)
Operating primarily in the Permian Basin with 10 hydraulic fracturing fleets, RPC (NYSE: RES) provides specialized services and equipment like hydraulic fracturing, coiled tubing, and cementing to help oil and gas companies complete and maintain wells.
RPC reported revenues of $460.9 million, up 9.5% year on year. This result surpassed analysts’ expectations by 1.1%. It was a stunning quarter as it also recorded a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
The stock is up 19.4% since reporting and currently trades at $6.12.
Read our full, actionable report on RPC here, it’s free.
Helmerich & Payne (NYSE: HP)
Operating the largest fleet of super-spec rigs in North America with technology that can drill horizontal wells over two miles long, Helmerich & Payne (NYSE: HP) provides drilling rigs and crews to oil and gas companies that need wells drilled to extract hydrocarbons from underground.
Helmerich & Payne reported revenues of $1.03 billion, flat year on year. This print beat analysts’ expectations by 5.4%. Overall, it was a strong quarter as it also put up a solid beat of analysts’ EBITDA estimates.
The stock is up 28.1% since reporting and currently trades at $42.63.
Read our full, actionable report on Helmerich & Payne here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 6 Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.