As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the semiconductor manufacturing industry, including IPG Photonics (NASDAQ: IPGP) and its peers.
The semiconductor industry is driven by demand for advanced electronic products like smartphones, PCs, servers, and data storage. The need for technologies like artificial intelligence, 5G networks, and smart cars is also creating the next wave of growth for the industry. Keeping up with this dynamism requires new tools that can design, fabricate, and test chips at ever smaller sizes and more complex architectures, creating a dire need for semiconductor capital manufacturing equipment.
The 14 semiconductor manufacturing stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 3.5% while next quarter’s revenue guidance was 6.5% above.
While some semiconductor manufacturing stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 4.2% since the latest earnings results.
IPG Photonics (NASDAQ: IPGP)
Both a designer and manufacturer of its products, IPG Photonics (NASDAQ: IPGP) is a provider of high-performance fiber lasers used for cutting, welding, and processing raw materials.
IPG Photonics reported revenues of $278.6 million, up 11.1% year on year. This print was in line with analysts’ expectations, and overall, it was a strong quarter for the company with a beat of analysts’ EPS estimates and a solid beat of analysts’ operating income estimates.
“We delivered our third consecutive quarter of double-digit year-over-year revenue growth, with revenue above the midpoint of our guidance and adjusted gross margin and adjusted EPS above our expectations,” said Dr. Mark Gitin, Chief Executive Officer of IPG Photonics.
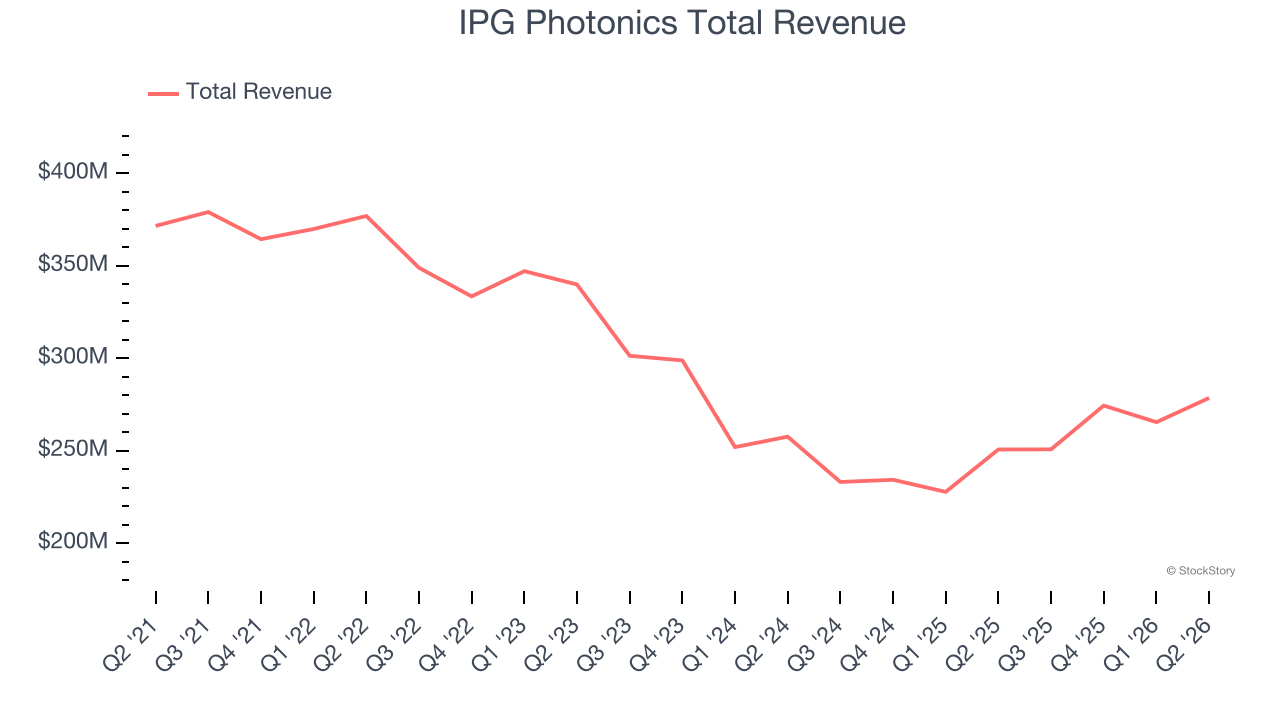
IPG Photonics delivered the weakest performance against analyst estimates in the group. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 11.8% since reporting and currently trades at $76.88.
Is now the time to buy IPG Photonics? Access our full analysis of the earnings results here, it’s free.
Best Q2: Kulicke and Soffa (NASDAQ: KLIC)
Headquartered in Singapore, Kulicke & Soffa (NASDAQ: KLIC) is a provider of production equipment and tools used to assemble semiconductor devices
Kulicke and Soffa reported revenues of $330.4 million, up 123% year on year, outperforming analysts’ expectations by 5.7%. The business had a stunning quarter with a significant improvement in its inventory levels and a beat of analysts’ EPS estimates.
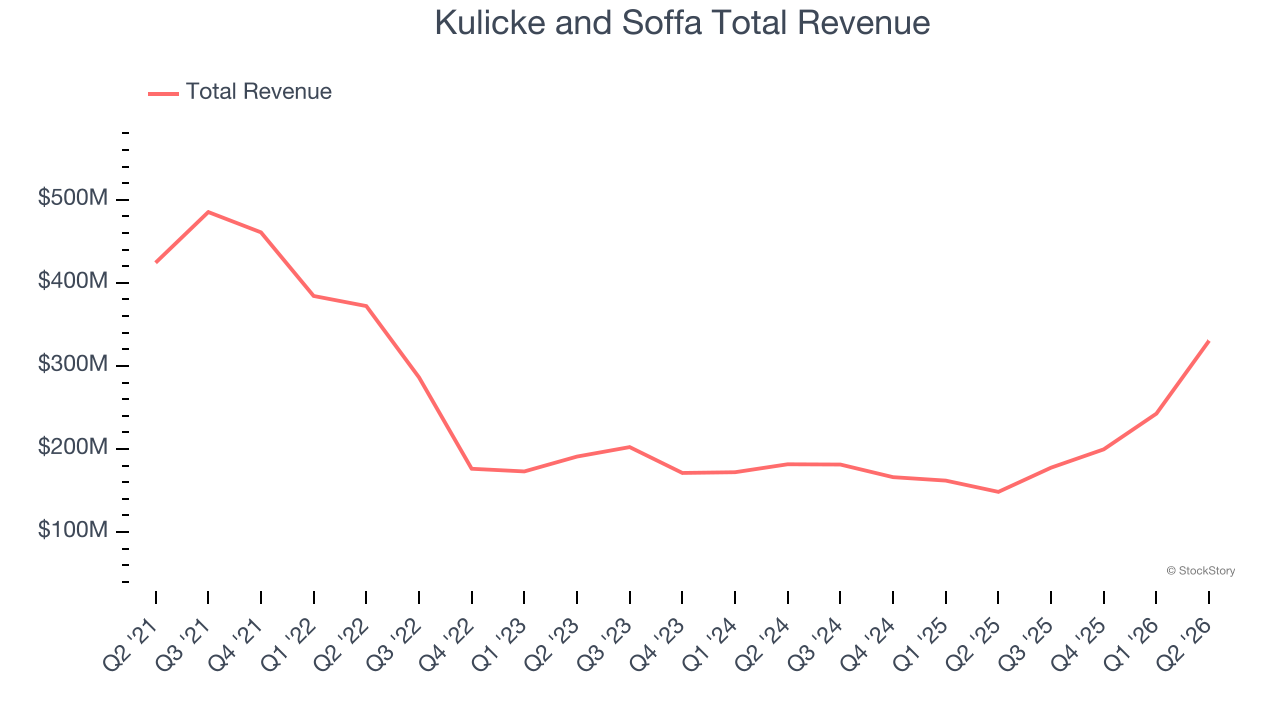
Kulicke and Soffa delivered the fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 12.9% since reporting. It currently trades at $81.77.
Is now the time to buy Kulicke and Soffa? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: KLA Corporation (NASDAQ: KLAC)
Formed by the 1997 merger of the two leading semiconductor yield management companies, KLA Corporation (NASDAQ: KLAC) is the leading supplier of equipment used to measure and inspect semiconductor chips.
KLA Corporation reported revenues of $3.66 billion, up 15.2% year on year, exceeding analysts’ expectations by 1.3%. It may have had the worst quarter among its peers, but its results were still good as it also locked in a beat of analysts’ EPS estimates and a decent beat of analysts’ operating income estimates.
As expected, the stock is down 10.5% since the results and currently trades at $170.75.
Read our full analysis of KLA Corporation’s results here.
FormFactor (NASDAQ: FORM)
With customers across the foundry and fabless markets, FormFactor (NASDAQ: FORM) is a US-based provider of test and measurement technologies for semiconductors.
FormFactor reported revenues of $258.2 million, up 31.9% year on year. This print surpassed analysts’ expectations by 7.6%. Overall, it was a stunning quarter as it also produced a beat of analysts’ EPS estimates and an impressive beat of analysts’ operating income estimates.
The stock is up 27.7% since reporting and currently trades at $106.55.
Read our full, actionable report on FormFactor here, it’s free.
Semtech (NASDAQ: SMTC)
A public company since the late 1960s, Semtech (NASDAQ: SMTC) is a provider of analog and mixed-signal semiconductors used for Internet of Things systems and cloud connectivity.
Semtech reported revenues of $341.9 million, up 32.7% year on year. This number topped analysts’ expectations by 4%. It was a stunning quarter as it also logged a significant improvement in its inventory levels and a beat of analysts’ EPS estimates.
The stock is up 16% since reporting and currently trades at $147.98.
Read our full, actionable report on Semtech here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.