Homebuilder Lennar (NYSE: LEN) missed Wall Street’s revenue expectations in Q3 CY2026, with sales falling 8.7% year on year to $8.05 billion. Its GAAP profit of $1.19 per share was 7.6% below analysts’ consensus estimates.
Is now the time to buy Lennar? Find out by accessing our full research report, it’s free.
Lennar (LEN) Q3 CY2026 Highlights:
- Revenue: $8.05 billion vs analyst estimates of $8.31 billion (8.7% year-on-year decline, 3.2% miss)
- EPS (GAAP): $1.19 vs analyst expectations of $1.29 (7.6% miss)
- Operating Margin: 5.5%, down from 7.9% in the same quarter last year
- Backlog: $6.3 billion at quarter end, down 4.5% year on year
- Market Capitalization: $19.24 billion
Stuart Miller, Executive Chairman, Chief Executive Officer and President of Lennar, said, "Our third quarter 2026 results reflect consistent focus on our operating strategy of maintaining volume and production while navigating a challenging economic environment. While our earnings of $1.19 per share were below expectations, they reflect the nature of the environment in which we are operating, which has deteriorated since our last earnings call."
Company Overview
One of the largest homebuilders in America, Lennar (NYSE: LEN) is known for constructing affordable, move-up, and retirement homes across a range of markets and communities.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Lennar grew its sales at a tepid 4.6% compounded annual growth rate. This was below our standard for the industrials sector and is a tough starting point for our analysis.
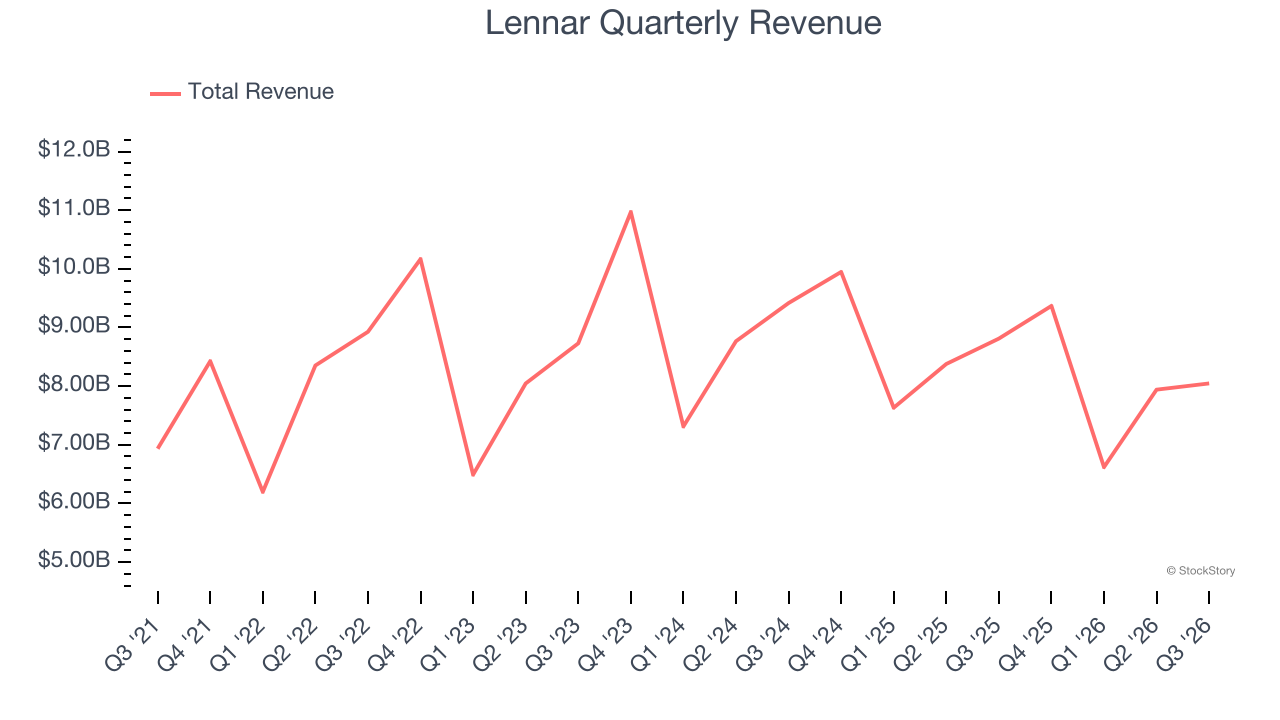
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Lennar’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 6.4% annually. Lennar isn’t alone in its struggles as the Home Builders industry experienced a cyclical downturn, with many similar businesses observing lower sales at this time. 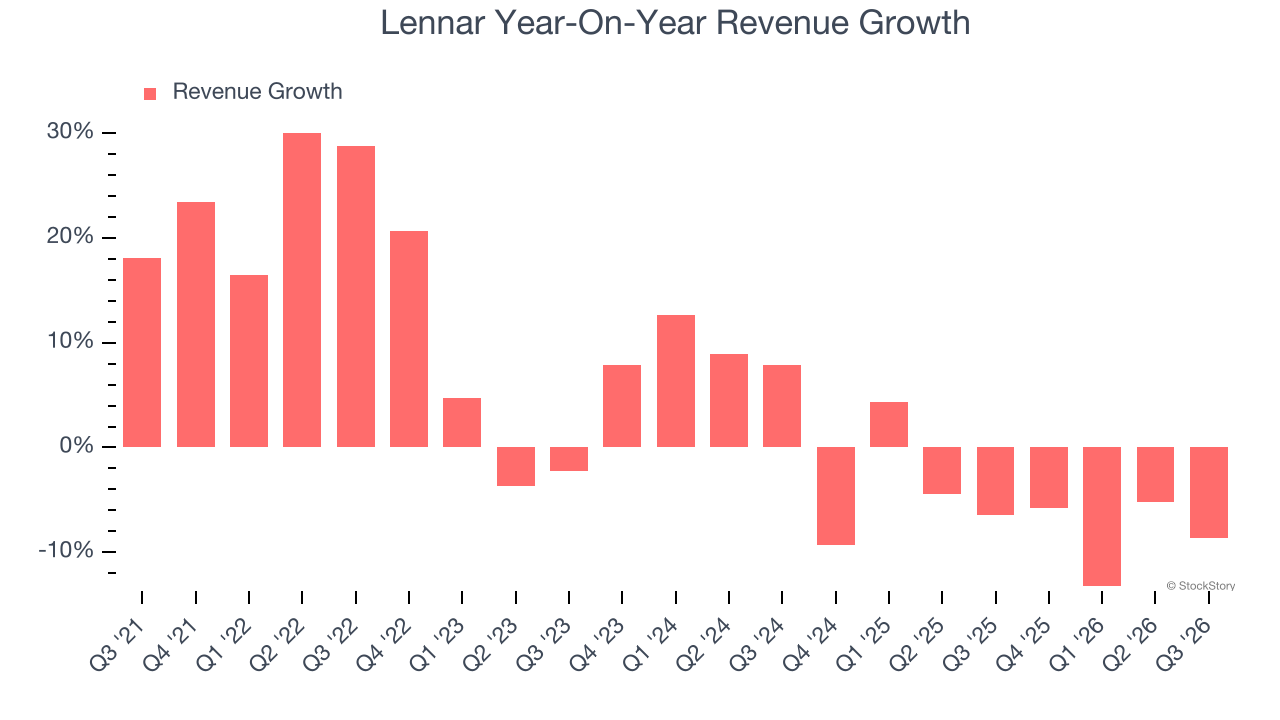
We can dig further into the company’s revenue dynamics by analyzing its backlog, or the value of its outstanding orders that have not yet been executed or delivered. Lennar’s backlog reached $6.3 billion in the latest quarter and averaged 8.6% year-on-year declines over the last two years. Because this number is lower than its revenue growth, we can see the company hasn’t secured enough new orders to maintain its growth rate in the future. 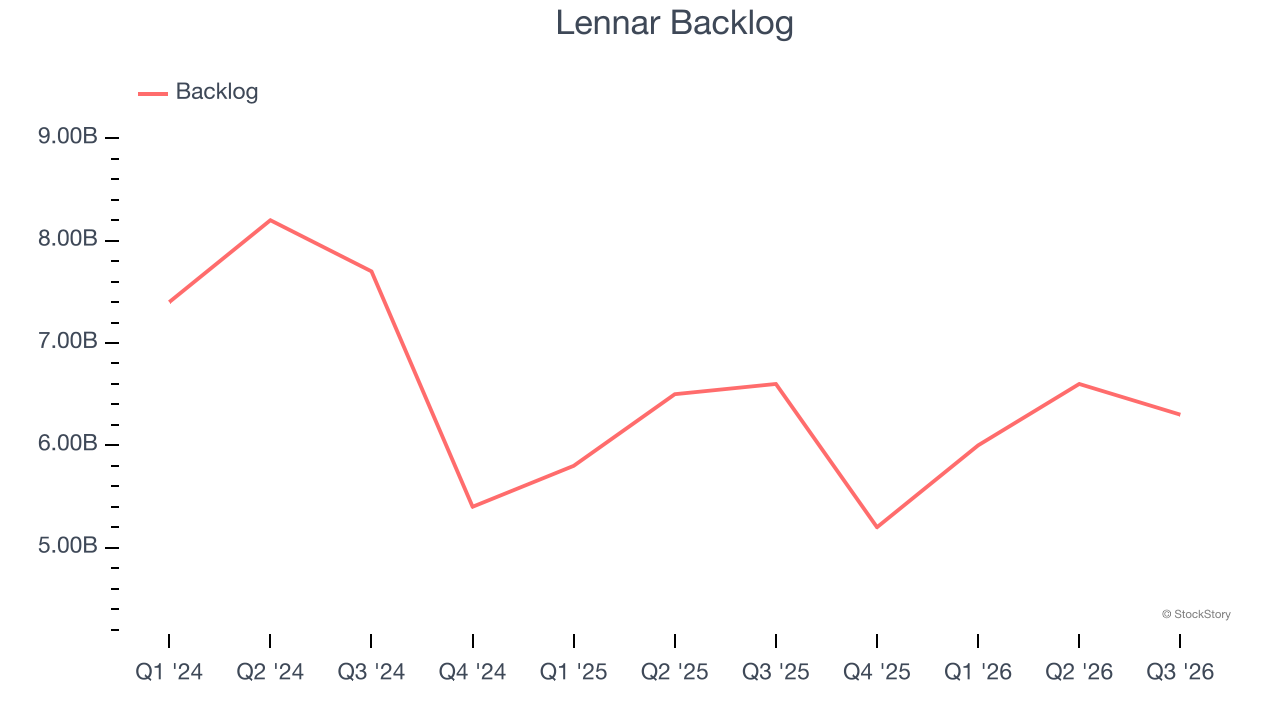
This quarter, Lennar missed Wall Street’s estimates and reported a rather uninspiring 8.7% year-on-year revenue decline, generating $8.05 billion of revenue.
Looking ahead, sell-side analysts expect revenue to grow 3.9% over the next 12 months. While this projection implies its newer products and services will catalyze better top-line performance, it is still below the sector average.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating Margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Lennar has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, boasting an average operating margin of 13.3%. This result was particularly impressive because of its low gross margin, which is mostly a factor of what it sells and takes huge shifts to move meaningfully. Companies have more control over their operating margins, and it’s a show of well-managed operations if they’re high when gross margins are low.
Looking at the trend in its profitability, Lennar’s operating margin decreased by 15.4 percentage points over the last five years. Many Home Builders companies also saw their margins fall (along with revenue, as mentioned above) because the cycle turned in the wrong direction. We hope Lennar can emerge from this a stronger company, as the silver lining of a downturn is that market share can be won and efficiencies found.
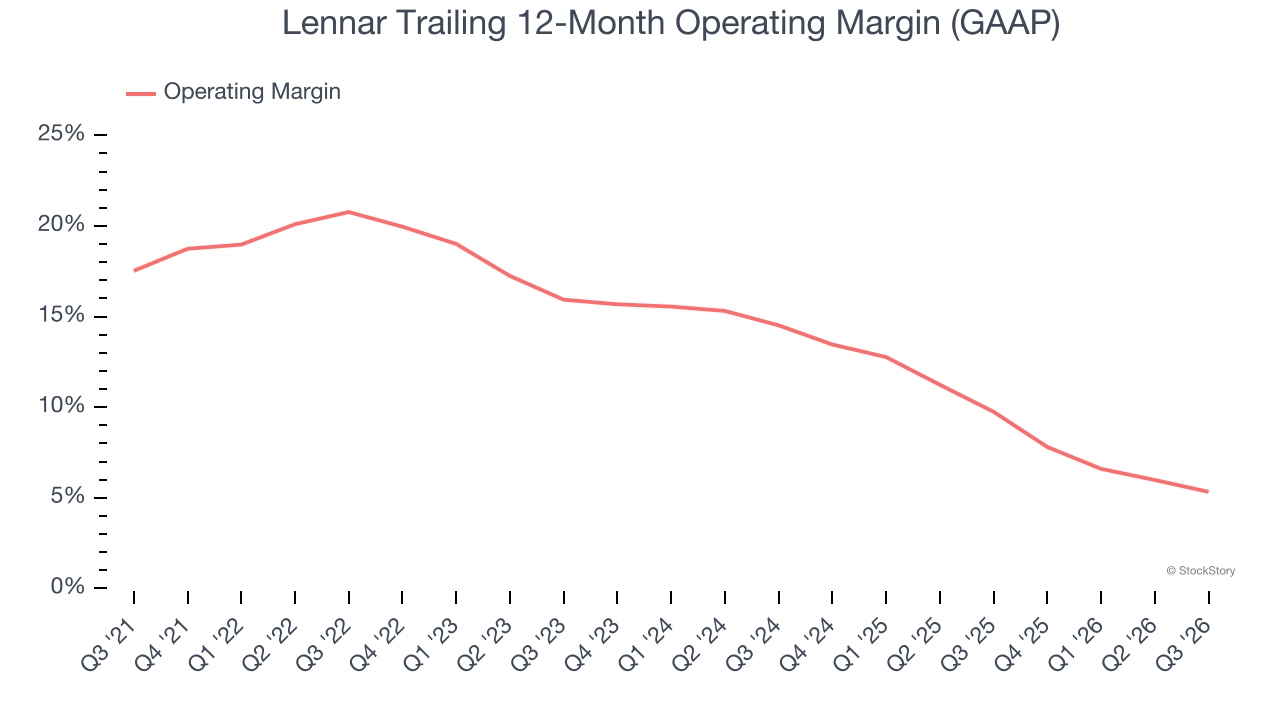
This quarter, Lennar generated an operating margin profit margin of 5.5%, down 2.4 percentage points year on year. Conversely, its gross margin actually rose, so we can assume its recent inefficiencies were driven by increased operating expenses like marketing, R&D, and administrative overhead.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Sadly for Lennar, its EPS declined by 16.8% annually over the last five years while its revenue grew by 4.6%. This tells us the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
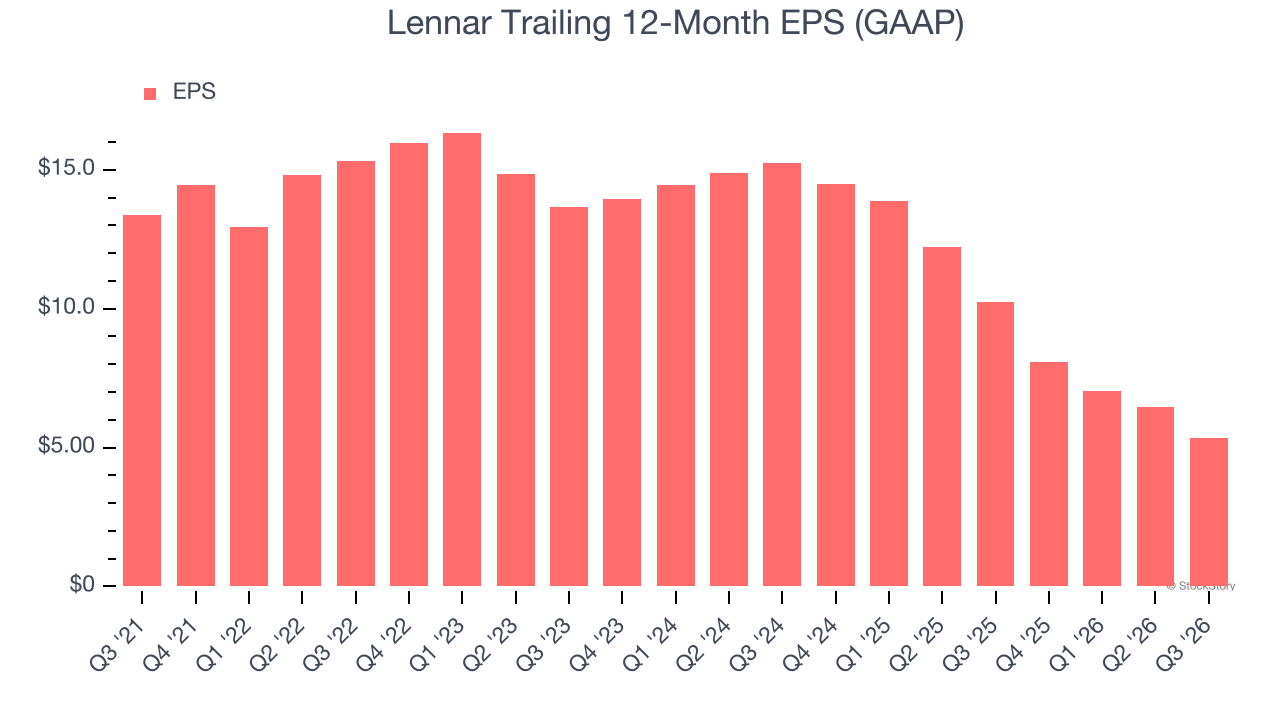
Diving into the nuances of Lennar’s earnings can give us a better understanding of its performance. As we mentioned earlier, Lennar’s operating margin declined by 15.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Lennar, its two-year annual EPS declines of 40.9% show it’s continued to underperform. These results were bad no matter how you slice the data.
In Q3, Lennar reported EPS of $1.19, down from $2.31 in the same quarter last year. This print missed analysts’ estimates. Over the next 12 months, Wall Street expects Lennar’s full-year EPS to grow 12.1% from $5.34 to $5.98.
Key Takeaways from Lennar’s Q3 Results
We struggled to find many positives in these results. Its revenue missed and its EPS fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock traded down 2.5% to $76.28 immediately following the results.
Lennar’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so let’s explore whether the stock is a buy at the current price. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).