Champion Homes has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 13.3% to $85.71 per share while the index has gained 16.9%.
Is there a buying opportunity in Champion Homes, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Champion Homes Not Exciting?
We’re cautious about Champion Homes. Here are three reasons why there are better opportunities than SKY, plus one stock we’d rather own.
1. Weak Sales Volumes Indicate Waning Demand
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Home Builders company because there’s a ceiling to what customers will pay.
Champion Homes’s units sold came in at 7,089 in the latest quarter, and over the last two years, averaged 2.3% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 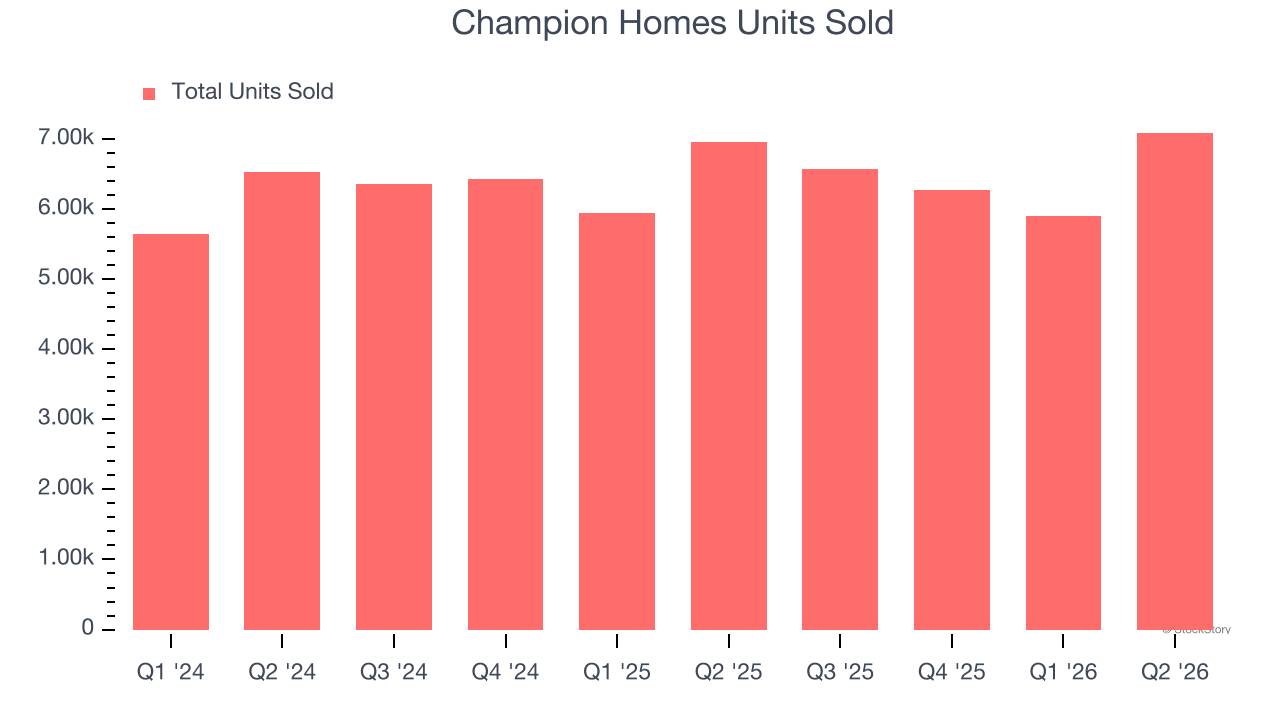
2. Shrinking Operating Margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
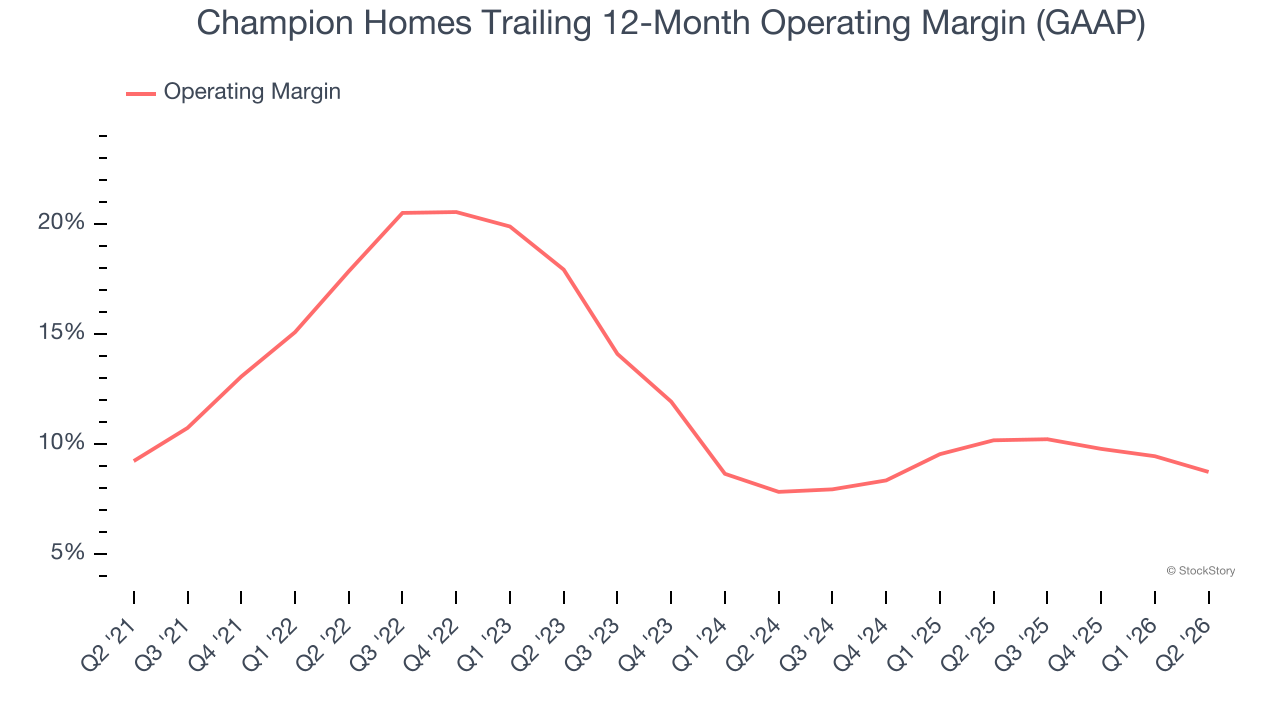
Analyzing the trend in its profitability, Champion Homes’s operating margin decreased by 9.1 percentage points over the last five years. Many Home Builders companies also saw their margins fall (along with revenue, as mentioned above) because the cycle turned in the wrong direction. We hope Champion Homes can emerge from this a stronger company, as the silver lining of a downturn is that market share can be won and efficiencies found. Its operating margin for the trailing 12 months was 8.7%.
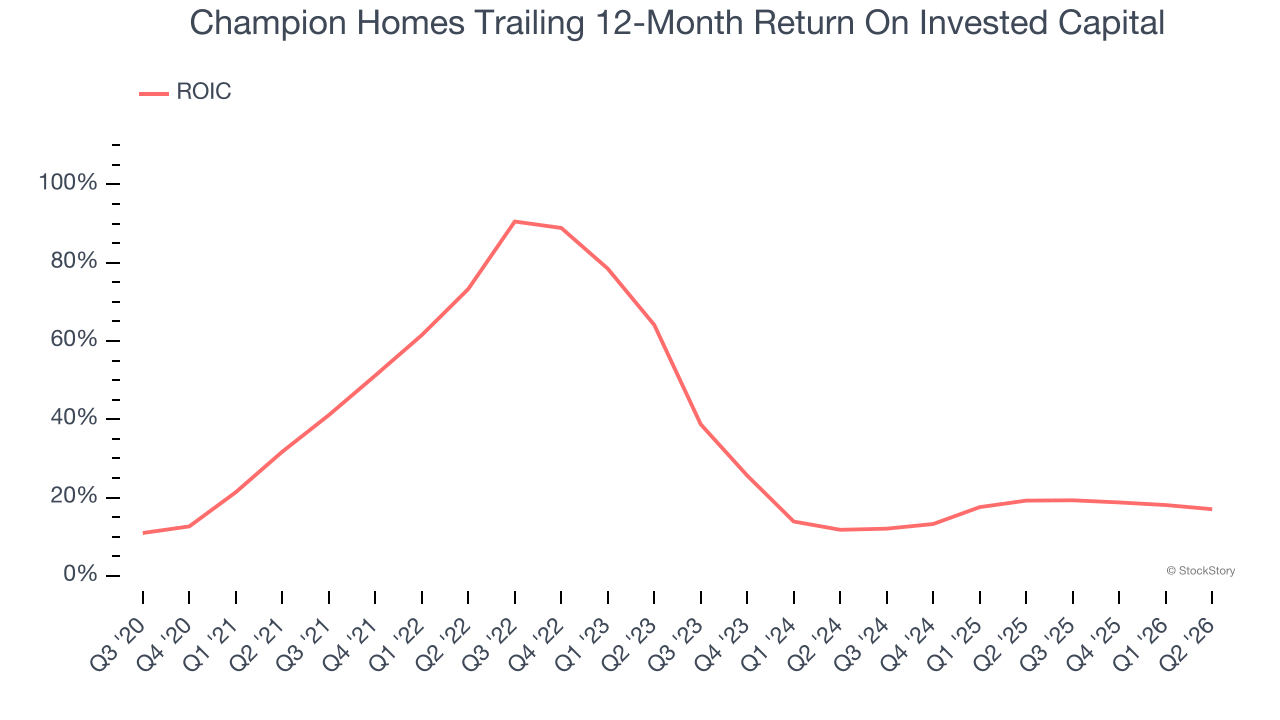
3. New Investments Fail to Bear Fruit as ROIC Declines
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Over the last few years, Champion Homes’s ROIC has unfortunately decreased significantly. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Champion Homes isn’t a terrible business, but it isn’t one of our picks. That said, the stock currently trades at 23.1× forward P/E (or $85.71 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. Let us point you toward one of our top digital advertising picks.
Stocks We Like More Than Champion Homes
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.