Over the last six months, Ollie’s shares have sunk to $82.75, producing a disappointing 9.1% loss - a stark contrast to the S&P 500’s 16.9% gain. This may have investors wondering how to approach the situation.
Is now the time to buy Ollie's, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Ollie's Not Exciting?
Despite the more favorable entry price, we’re sitting this one out for now. Here are three reasons you should be careful with OLLI, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
With $2.79 billion in revenue over the past 12 months, Ollie's is a small retailer, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with suppliers. On the bright side, it can grow faster because it has more white space to build new stores.
2. Operating Margin in Limbo
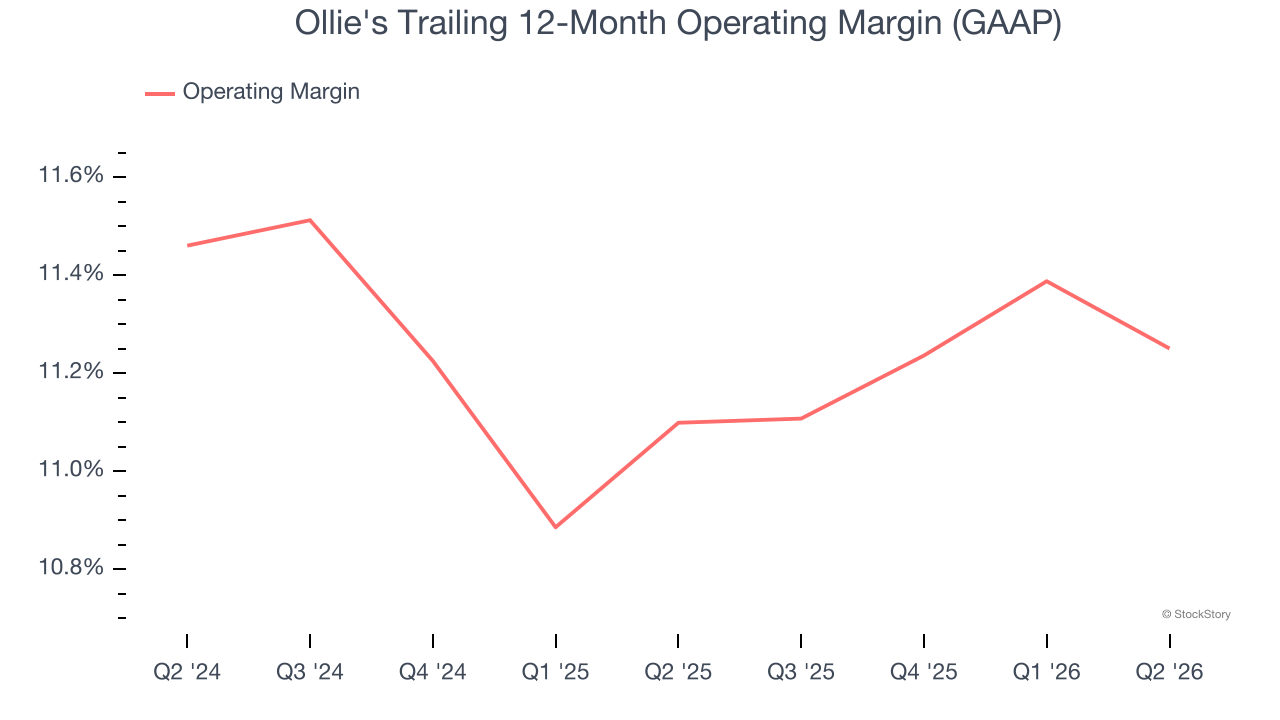
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Analyzing the trend in its profitability, Ollie’s operating margin might have fluctuated slightly but has generally stayed the same over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 11.3%.
3. Previous Growth Initiatives Haven’t Impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Ollie's historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 9.1%, somewhat low compared to the best consumer retail companies that consistently pump out 30%+.
Final Judgment
Ollie's isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 18.1× forward P/E (or $82.75 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward the most dominant software business in the world.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.