Bausch + Lomb currently trades at $16.69 per share and has shown little upside over the past six months, posting a middling return of 0.6%. The stock also fell short of the S&P 500’s 9.7% gain during that period.
Is there a buying opportunity in Bausch + Lomb, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Bausch + Lomb Not Exciting?
We’re cautious about Bausch + Lomb. Here are three reasons why there are better opportunities than BLCO, plus one stock we’d rather own.
1. EPS Trending Down
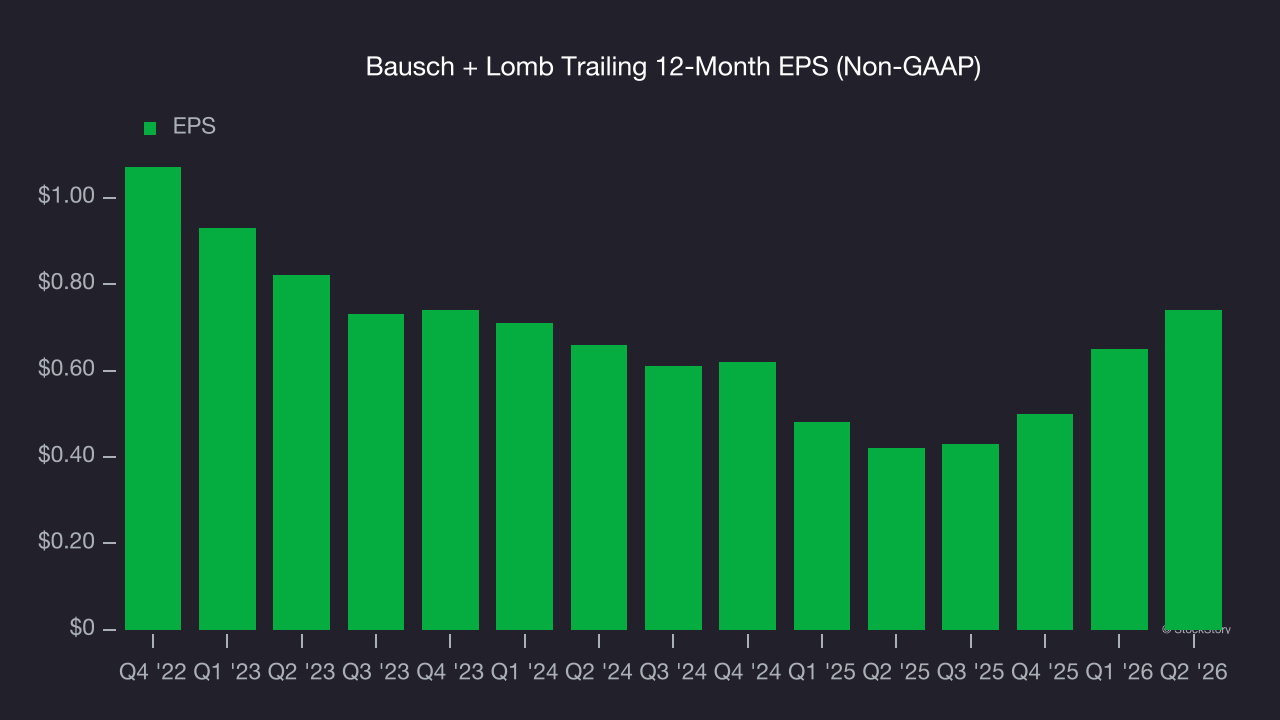
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Bausch + Lomb’s full-year EPS dropped 93.7%, or 18% annually, over the last four years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Bausch + Lomb’s low margin of safety could leave its stock price susceptible to large downswings.
2. Free Cash Flow Margin Dropping
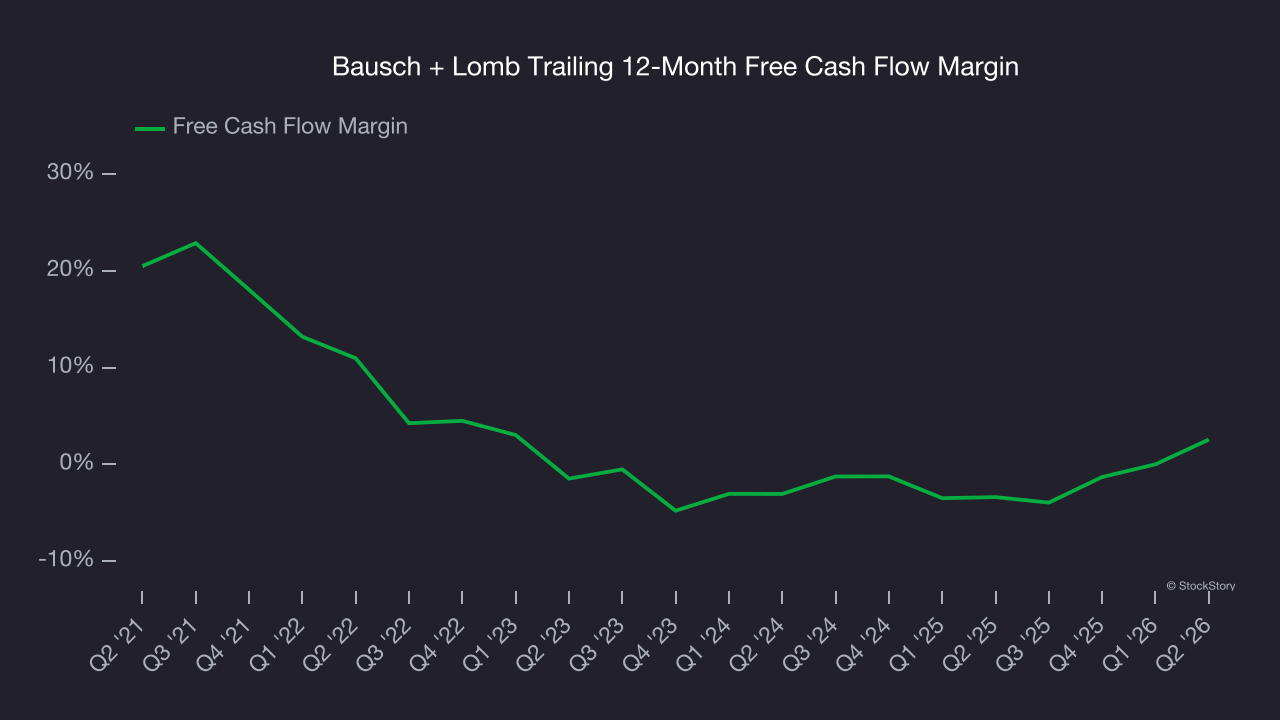
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, Bausch + Lomb’s margin dropped by 8.4 percentage points over the last five years. It may have ticked higher more recently, but shareholders are likely hoping for its margin to at least revert to its historical level. Almost any movement in the wrong direction is undesirable because of its already low cash conversion. If the longer-term trend returns, it could signal it’s becoming a more capital-intensive business. Bausch + Lomb’s free cash flow margin for the trailing 12 months was 2.6%.
3. Previous Growth Initiatives Haven’t Impressed
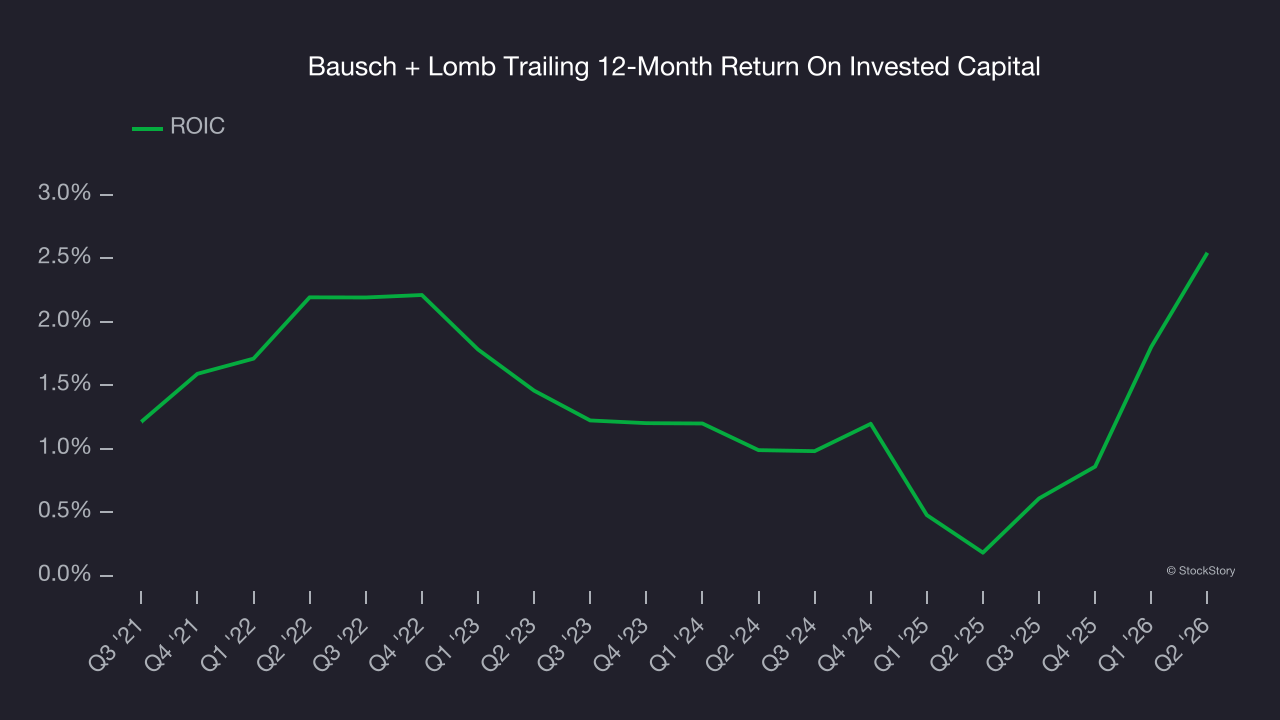
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Bausch + Lomb historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 1.5%, lower than the typical cost of capital (how much it costs to raise money) for healthcare companies.
Final Judgment
Bausch + Lomb’s business quality ultimately falls short of our standards. With its shares trailing the market in recent months, the stock trades at 15.9× forward P/E (or $16.69 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of Bausch + Lomb
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.