Regional banking company Zions Bancorporation (NASDAQ: ZION) missed Wall Street’s revenue expectations in Q3 2026 as sales only rose 1.7% year on year to $887 million. Its GAAP profit of $1.78 per share was 7.2% above analysts’ consensus estimates.
Is now the time to buy Zions Bancorporation? Find out by accessing our full research report, it’s free.
Zions Bancorporation (ZION) Q3 2026 Highlights:
- Net Interest Income: $684 million vs analyst estimates of $693 million (1.8% year-on-year growth, 1.3% miss)
- Net Interest Margin: 3.2% vs analyst estimates of 3.3% (5.5 basis point miss)
- Revenue: $887 million vs analyst estimates of $895.9 million (1.7% year-on-year growth, 1% miss)
- Efficiency Ratio: 61.9% vs analyst estimates of 62% (14.8 basis point beat)
- EPS (GAAP): $1.78 vs analyst estimates of $1.66 (7.2% beat)
- Tangible Book Value per Share: $43.50 vs analyst estimates of $45.81 (12.6% year-on-year growth, 5% miss)
- Market Capitalization: $9.25 billion
Company Overview
Founded in 1873 during Utah's pioneer era and named after Mount Zion in the Bible, Zions Bancorporation (NASDAQ: ZION) operates seven regional banks across the Western United States, providing commercial, retail, and wealth management services to over a million customers.
Sales Growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Over the last five years, Zions Bancorporation grew its revenue at a sluggish 4.4% compounded annual growth rate. This was below our standard for the banking sector and is a tough starting point for our analysis.
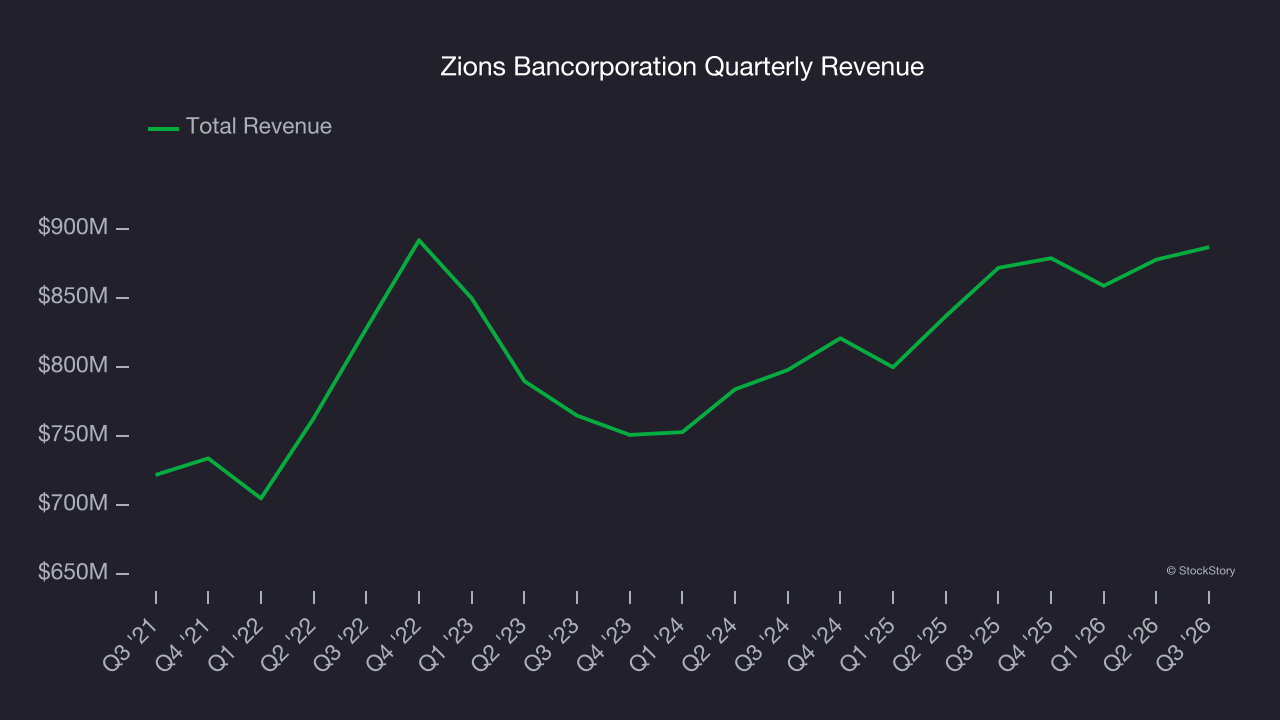
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Zions Bancorporation’s annualized revenue growth of 6.5% over the last two years is above its five-year trend, which is encouraging. 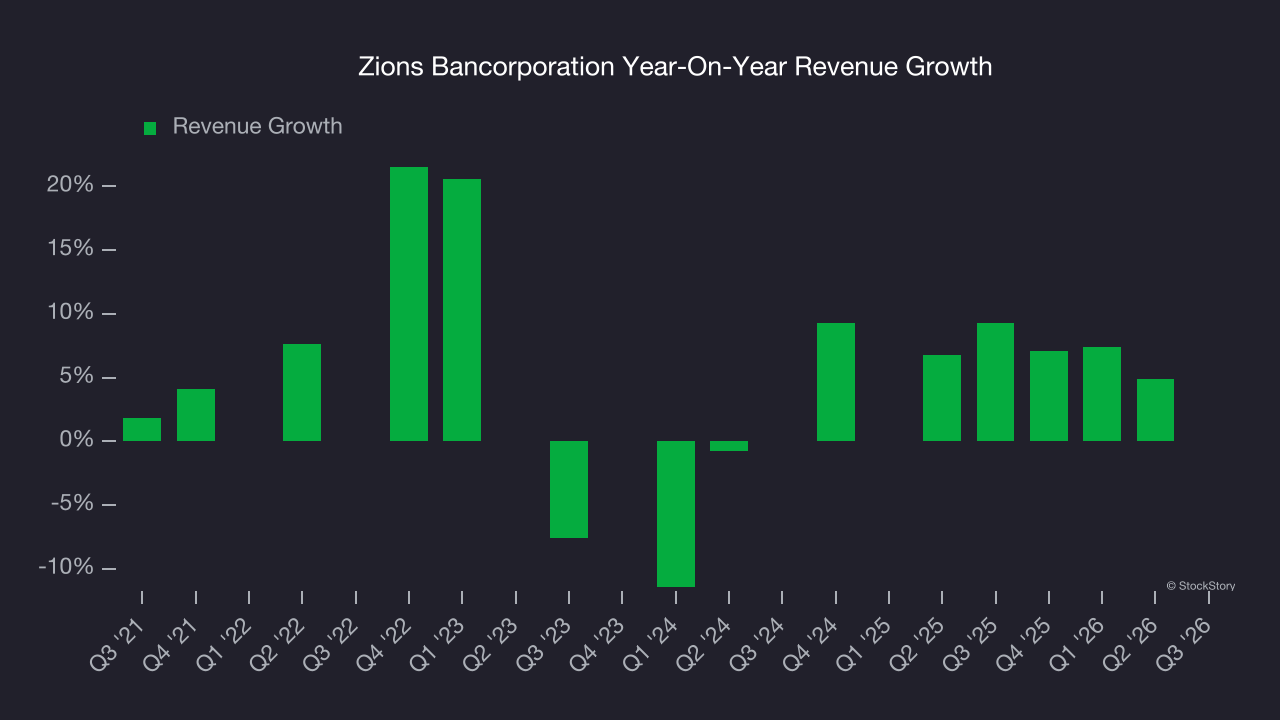 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Zions Bancorporation’s revenue grew by 1.7% year on year to $887 million, falling short of Wall Street’s estimates.
Net interest income made up 89.8% of the company’s total revenue during the last five years, meaning Zions Bancorporation barely relies on non-interest income to drive its overall growth.
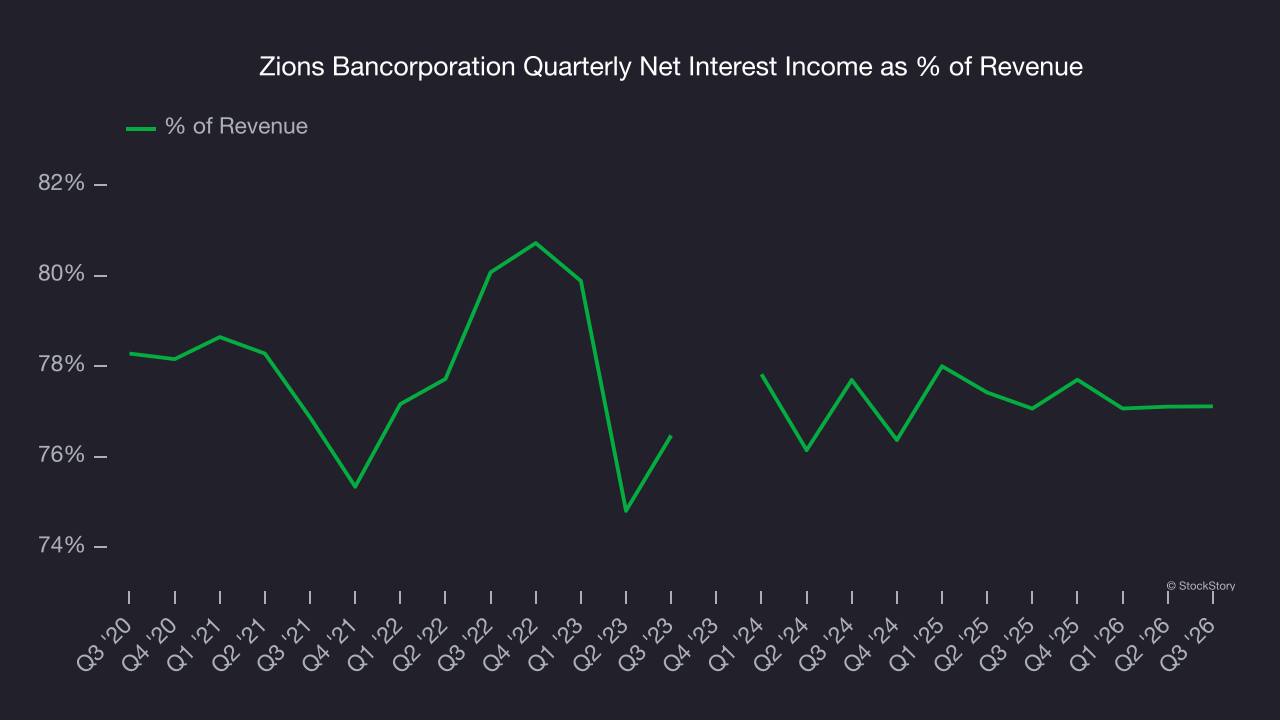 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
Our experience and research show the market cares primarily about a bank’s net interest income growth as non-interest income is considered a lower-quality and non-recurring revenue source.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Tangible Book Value Per Share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. On the other hand, EPS is often distorted by mergers and flexible loan loss accounting. TBVPS provides clearer performance insights.
Zions Bancorporation’s TBVPS grew at a sluggish 1.5% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 14.6% annually over the last two years from $33.12 to $43.50 per share.
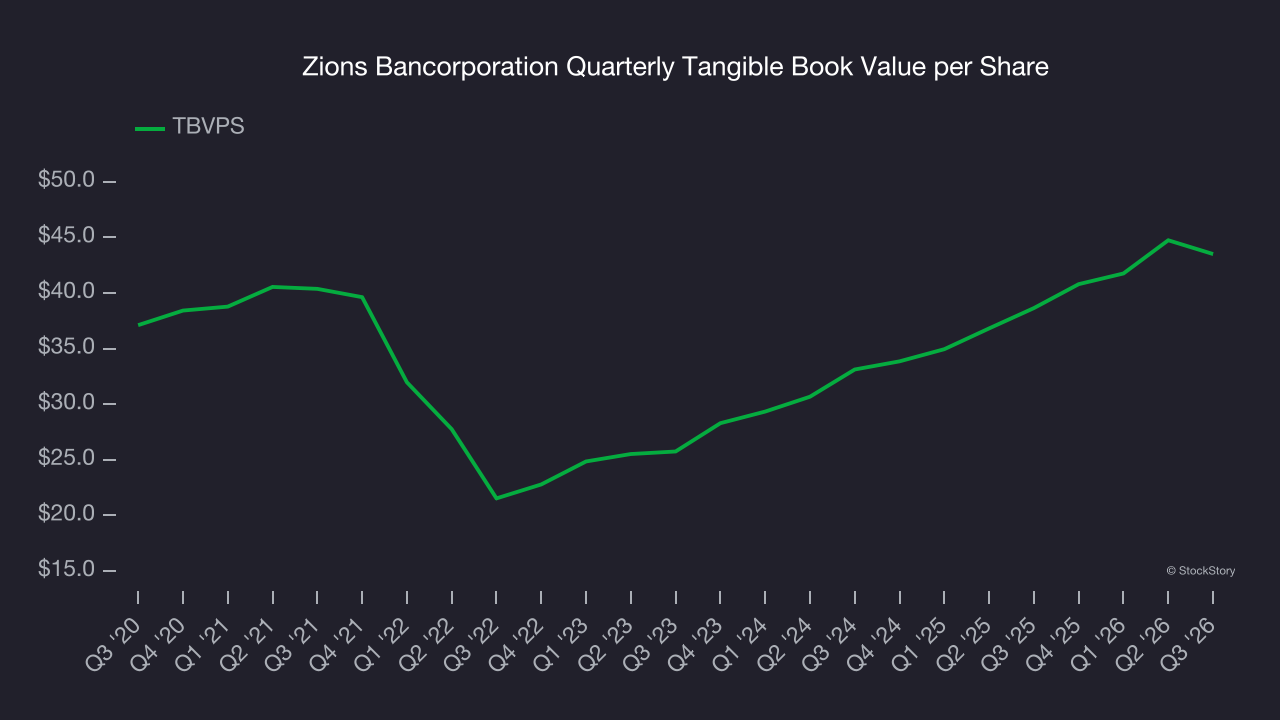
Over the next 12 months, Consensus estimates call for Zions Bancorporation’s TBVPS to grow by 17.5% to $51.11, top-notch growth rate.
Key Takeaways from Zions Bancorporation’s Q3 Results
It was good to see Zions Bancorporation beat analysts’ EPS expectations this quarter. On the other hand, its tangible book value per share missed and its net interest income fell slightly short of Wall Street’s estimates. Overall, this was a mixed quarter. The stock traded up 1.2% to $63.88 immediately following the results.
So should you invest in Zions Bancorporation right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).