Global payments company American Express (NYSE: AXP) met Wall Street’s revenue expectations in Q3 2026, with revenue up 17.1% year on year to $20.06 billion. Its GAAP profit of $5.42 per share was 20.4% above analysts’ consensus estimates.
For more on American Express, read our free full research report.
American Express (AXP) Q3 2026 highlights:
- Volume: $517.9 billion vs analysts’ consensus estimates of $519.5 billion (8.1% year-on-year growth, in line)
- Revenue: $20.06 billion vs analysts’ consensus estimates of $20.12 billion (17.1% year-on-year growth, in line)
- Pre-tax Profit: $4.53 billion (22.6% margin)
- EPS (GAAP): $5.42 vs analysts’ consensus estimates of $4.50 (20.4% beat)
- Market Capitalization: $219.6 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. American Express’s 12.4% annualized revenue growth over the last five years was solid. Its growth beat the average financials company and shows its offerings resonate with customers.
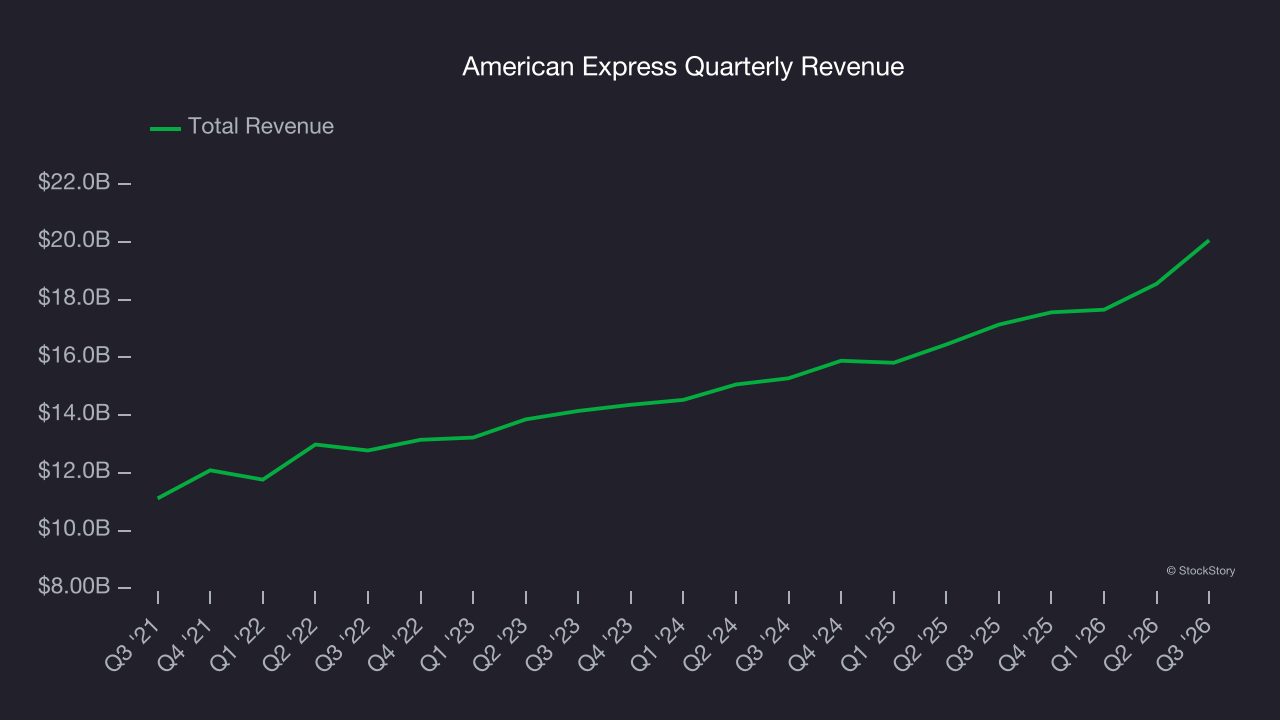
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. American Express’s annualized revenue growth of 11.6% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 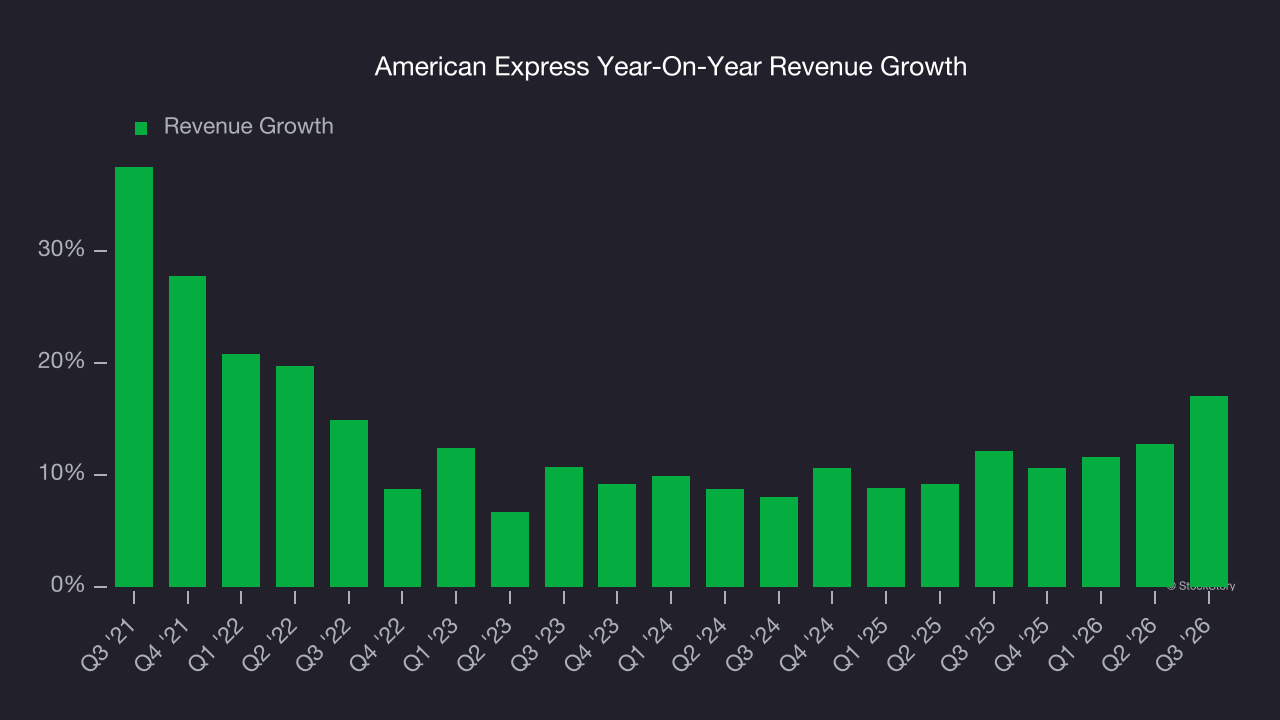
This quarter, American Express’s year-on-year revenue growth was 17.1%, and its $20.06 billion of revenue was in line with Wall Street’s consensus estimates.
Volume
Transaction volume and loan originations represent the core activity metrics that drive revenue growth across the financial services landscape. This overall volume serves as the primary engine of a firm’s top-line performance.
American Express’s volumes have grown at an annual rate of 11% over the last five years, a step above the broader financials industry but slower than its total revenue. Over the last two years, its volume growth decelerated to 8.1% annually.
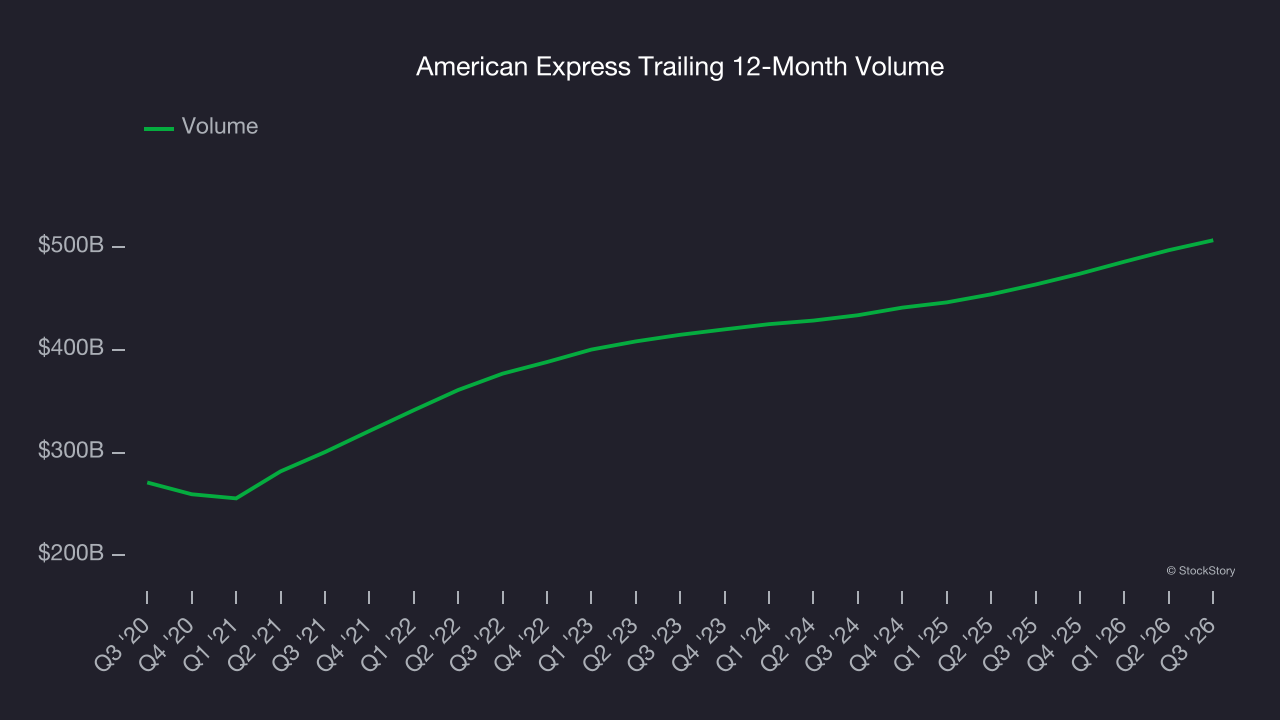
In Q3, American Express’s volumes totaled $517.9 billion, meeting analysts’ consensus estimates. Volume rose 8.1% from the same quarter last year.
Key takeaways from American Express’s Q3 results
American Express delivered a solid quarter, with EPS beating analysts’ consensus estimates. Transaction volumes, however, were only in line with expectations. The results had some clear positives, but investors were likely hoping for more: Shares edged lower 1.6% to $319.65 immediately after the report.
Should you invest in American Express right now? The latest quarter is only one factor in assessing longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. For more on American Express, read the full research report here (it’s free).