Automotive safety systems provider Autoliv (NYSE: ALV) missed Wall Street’s revenue expectations in Q3 2026, with revenue flat year on year at $2.69 billion. Its non-GAAP profit of $2.19 per share was 1.9% below analysts’ consensus estimates.
For more on Autoliv, read our full research report for free.
Autoliv (ALV) Q3 2026 highlights:
- Revenue: $2.69 billion vs analysts' consensus estimates of $2.72 billion (flat year on year, 0.9% miss)
- Adjusted EPS: $2.19 vs analysts' consensus estimates of $2.23 (1.9% miss)
- Operating Margin: 9.4%, in line with the same quarter last year
- Free Cash Flow Margin: 4.6%, down from 5.7% in the same quarter last year
- Market Capitalization: $8.71 billion
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can report a good quarter or two, but many enduring ones grow for years. Over the last five years, Autoliv’s revenue grew at a tepid 5.1% compound annual rate. This fell short of our benchmark for the industrials sector.
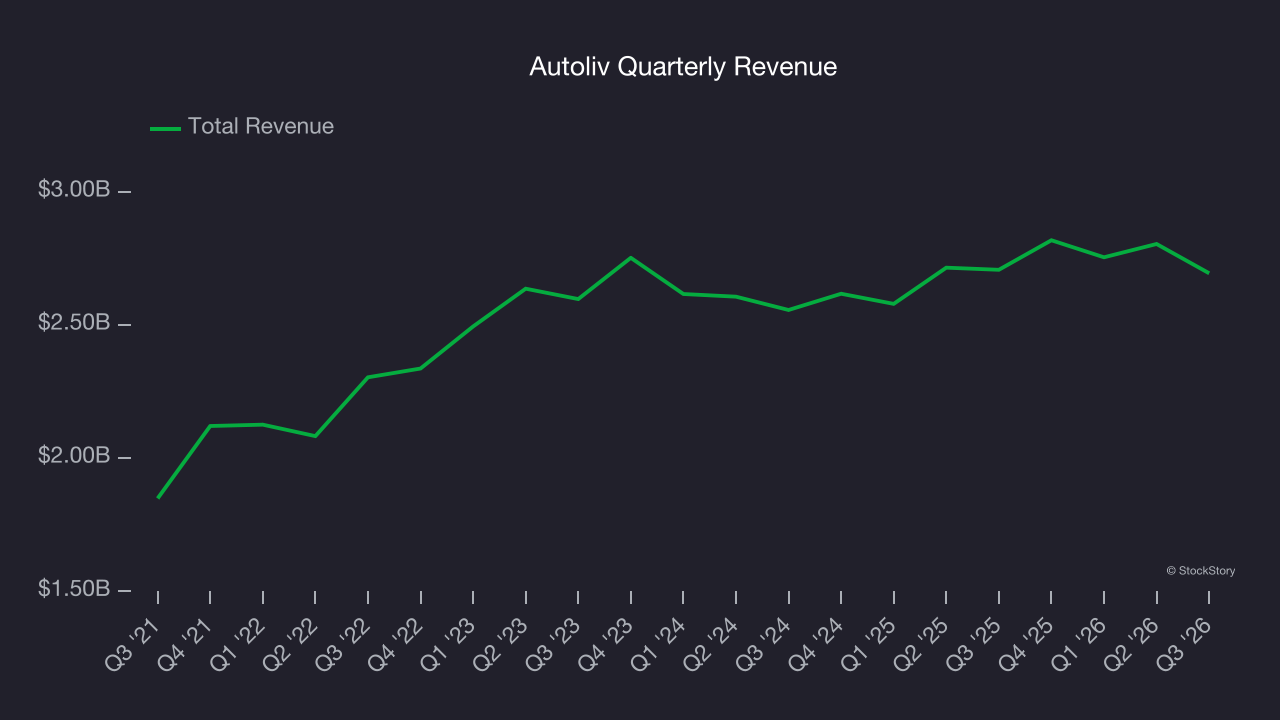
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Autoliv’s recent performance shows its demand has slowed as its annualized revenue growth of 2.5% over the last two years was below its five-year trend. Decelerating revenue growth in the sector is a concern, as it could signal changing consumer tastes aided by low switching costs. 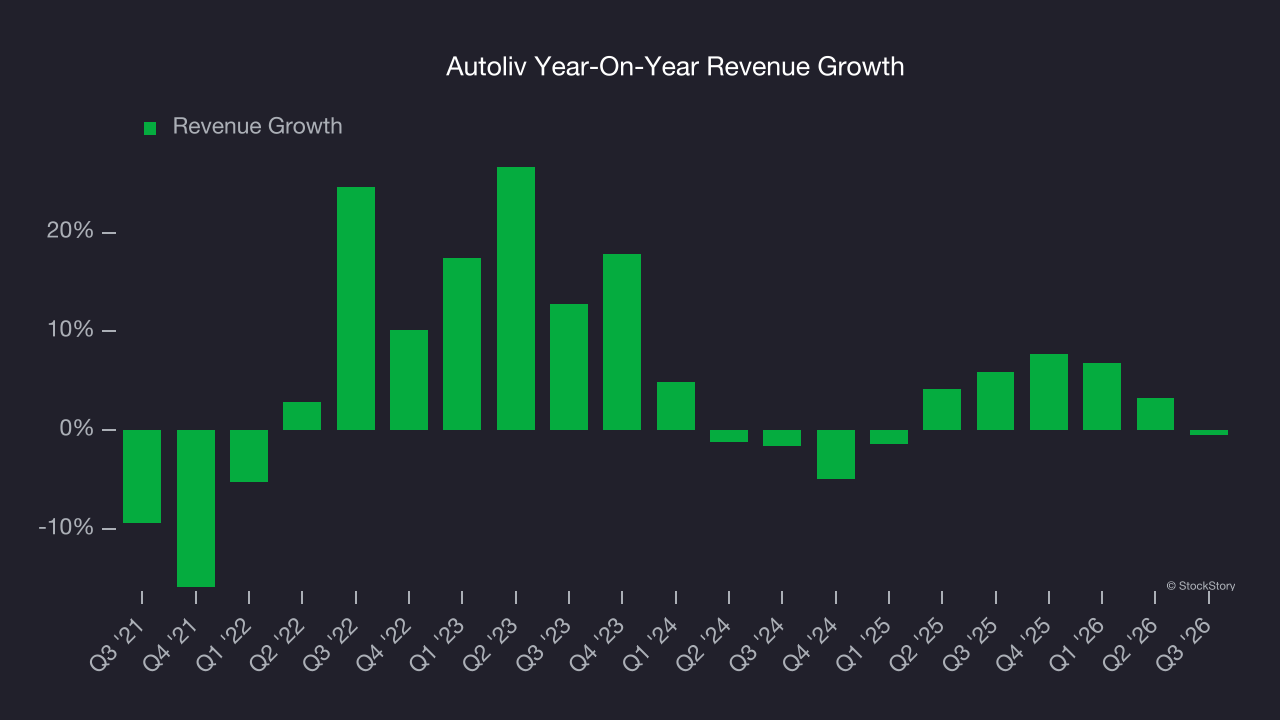
This quarter, Autoliv’s $2.69 billion of revenue was flat year on year, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 7.9% over the next 12 months according to S&P, an improvement versus the last two years. This projection is above the sector average and implies its newer products and services will drive better revenue performance.
Operating margin
Operating margin is one of the best measures of profitability because it shows how much money a company retains after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
Autoliv has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 8.4%, higher than the broader industrials sector.
Autoliv’s operating margin rose by 2.1 percentage points over the last five years, as its revenue growth provided operating leverage. The expansion was notable, especially considering most automobile manufacturing peers saw their margins decline.
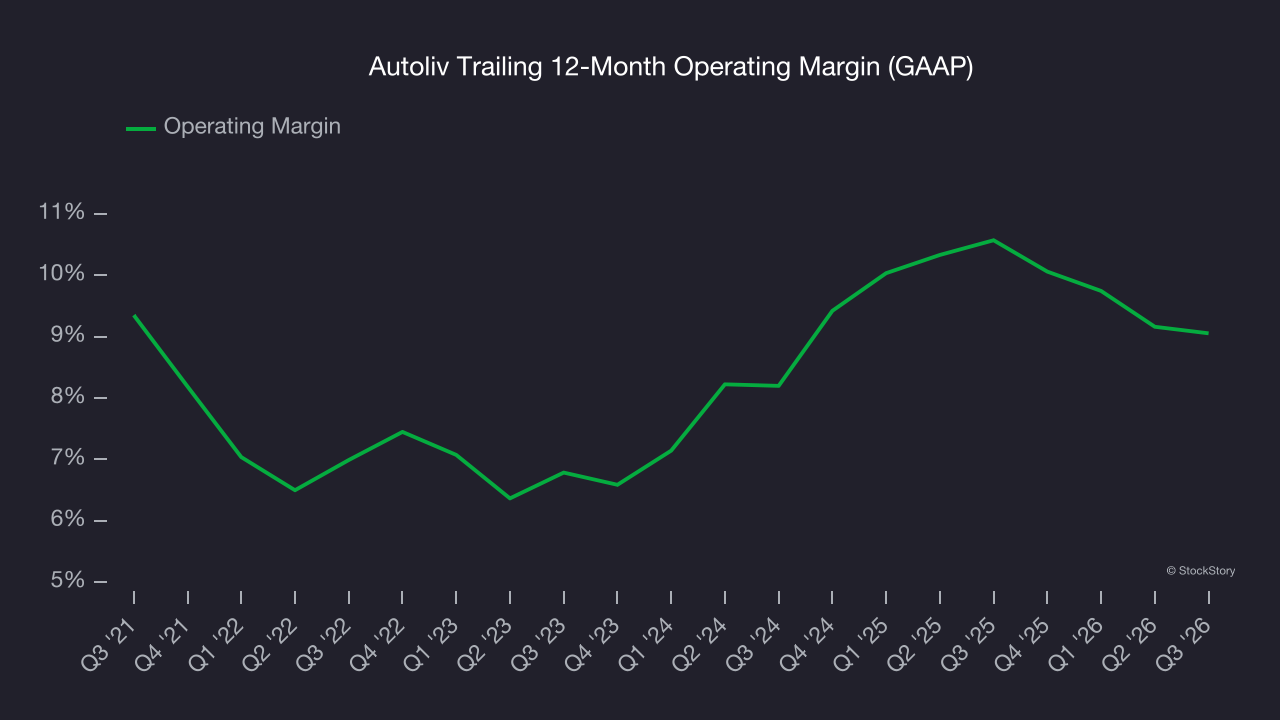
This quarter, Autoliv generated an operating margin of 9.4%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Autoliv’s EPS grew at a 10.8% compound annual rate over the last five years, higher than its 5.1% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
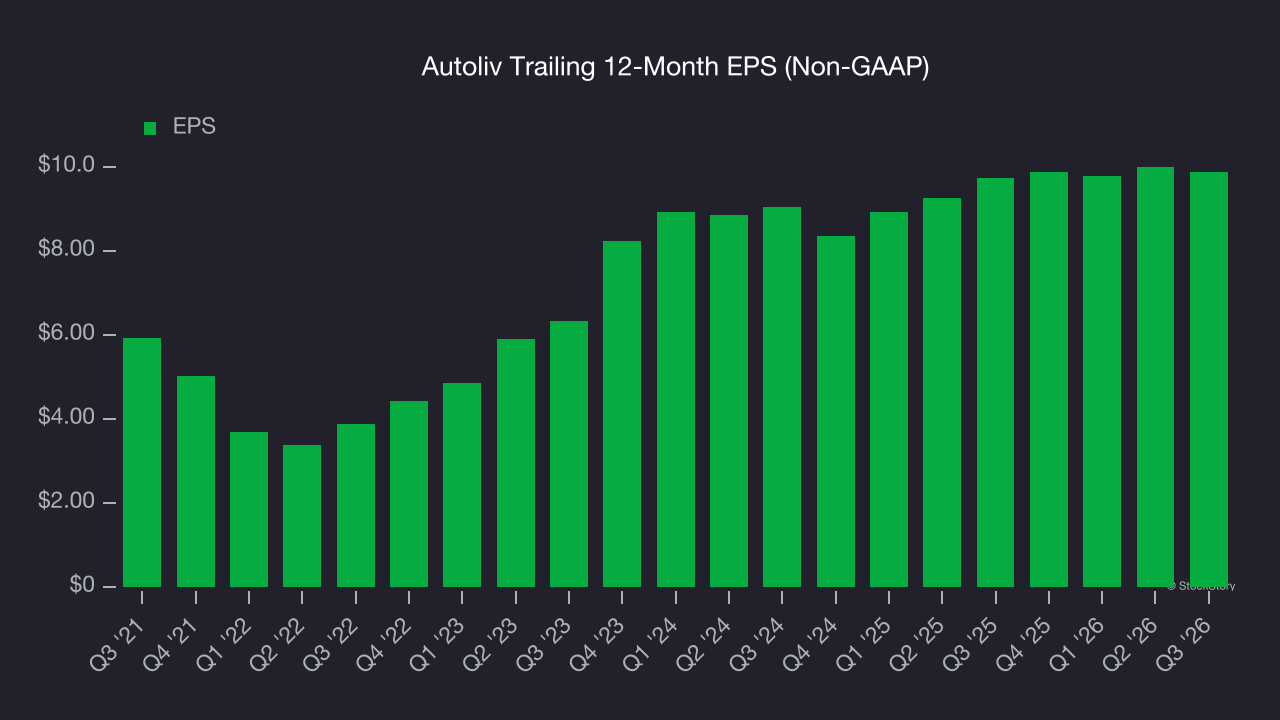
A closer look at Autoliv’s earnings helps explain its performance. As mentioned earlier, Autoliv’s operating margin was flat this quarter but expanded by 2.1 percentage points over the last five years. In addition, its share count shrank by 16.9%. These are positive signs for shareholders because improving profitability and share buybacks help EPS grow faster than revenue. 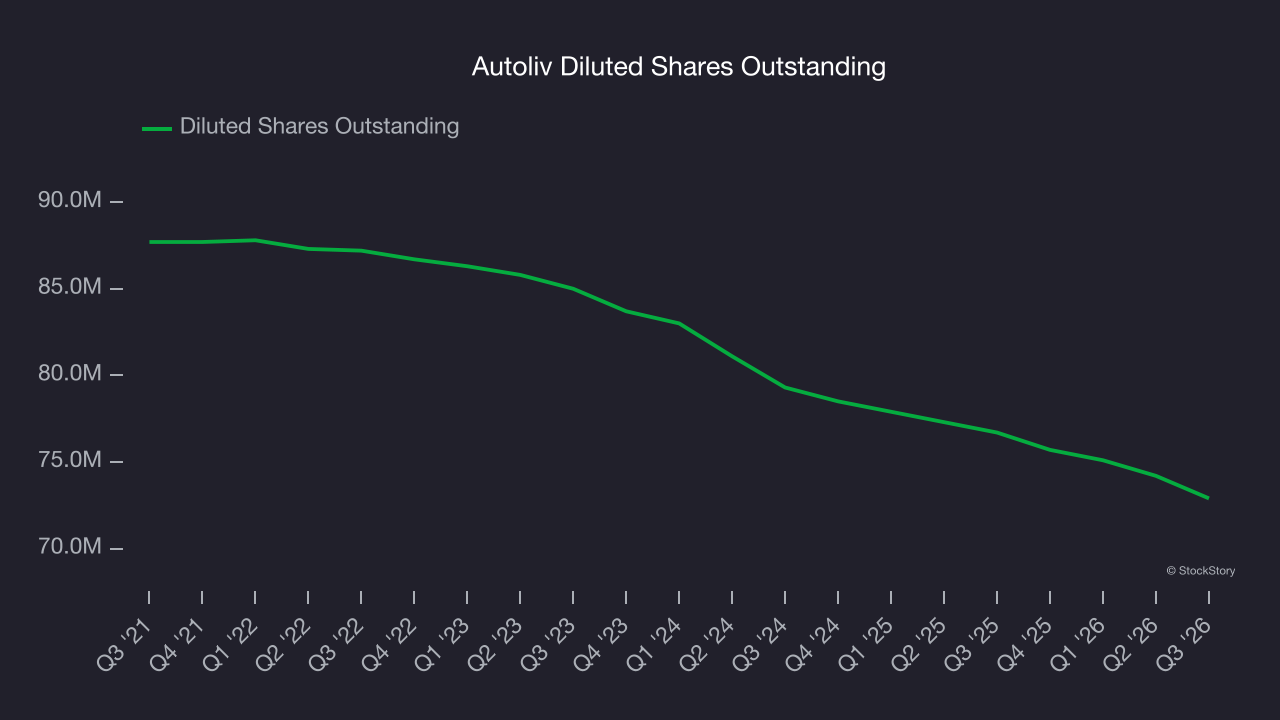
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
Autoliv’s two-year annual EPS growth of 4.5% was lower than its five-year trend. Faster growth would be a positive development.
In Q3, Autoliv reported adjusted EPS of $2.19, down from $2.32 in the same quarter last year. This result slightly missed analysts’ consensus estimates, but long-term adjusted EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects Autoliv’s full-year EPS to grow 10.1% from $9.86 to $10.85 according to S&P.
Key takeaways from Autoliv’s Q3 results
Autoliv’s Q3 offered few positives: revenue narrowly missed Wall Street’s consensus estimates, and EPS also fell short. The softer quarter was followed by a 5.2% tumble in the stock to $112.64 immediately after the release.
Autoliv had a disappointing quarter, but does that create a buying opportunity at the current price? The latest quarter matters, but longer-term fundamentals and valuation matter much more when deciding whether the stock is a buy. For more on Autoliv, read the full research report here (it’s free).