Gorman-Rupp (NYSE: GRC), which manufactures and sells pumps globally, reported revenue ahead of Wall Street’s expectations in Q3 2026, as revenue rose 11.8% year on year to $193.3 million. Its non-GAAP profit of $0.86 per share was 22.3% above analysts’ consensus estimates.
For more on Gorman-Rupp, read our free full research report.
Gorman-Rupp (GRC) Q3 2026 highlights:
- Revenue: $193.3 million vs analysts’ consensus estimates of $181.6 million (11.8% year-on-year growth, 6.4% beat)
- Adjusted EPS: $0.86 vs analysts’ consensus estimates of $0.70 (22.3% beat)
- Adjusted EBITDA: $41.8 million vs analysts’ consensus estimates of $36.01 million (21.6% margin, 16.1% beat)
- Operating Margin: 17.5%, up from 13.9% in the same quarter last year
- Free Cash Flow Margin: 23.6%, up from 20.7% in the same quarter last year
- Backlog: $236.8 million at quarter end, up 1.1% year on year
- Market Capitalization: $1.85 billion
Scott A. King, President and CEO, commented, “We are very pleased with our third-quarter results, which included record net sales, gross margin, and earnings per share. This marks the third consecutive quarter with record earnings per share and the second consecutive quarter with record sales. Our sales growth was broad-based with all of our markets showing growth over the same quarter last year. Our margins remained strong as increased volumes drove leverage on labor, overhead and SG&A expenses. These operating improvements, together with lower interest expense, contributed to record earnings and strong cash generation. Solid operating cash flow allowed us to reduce total debt by $58.0 million during the first nine months of the year while also continuing to invest in the business. Incoming orders and backlog remain healthy, and our diverse markets and strong financial position provide a solid foundation as we enter the fourth quarter.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Gorman-Rupp’s revenue grew at a 14.5% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
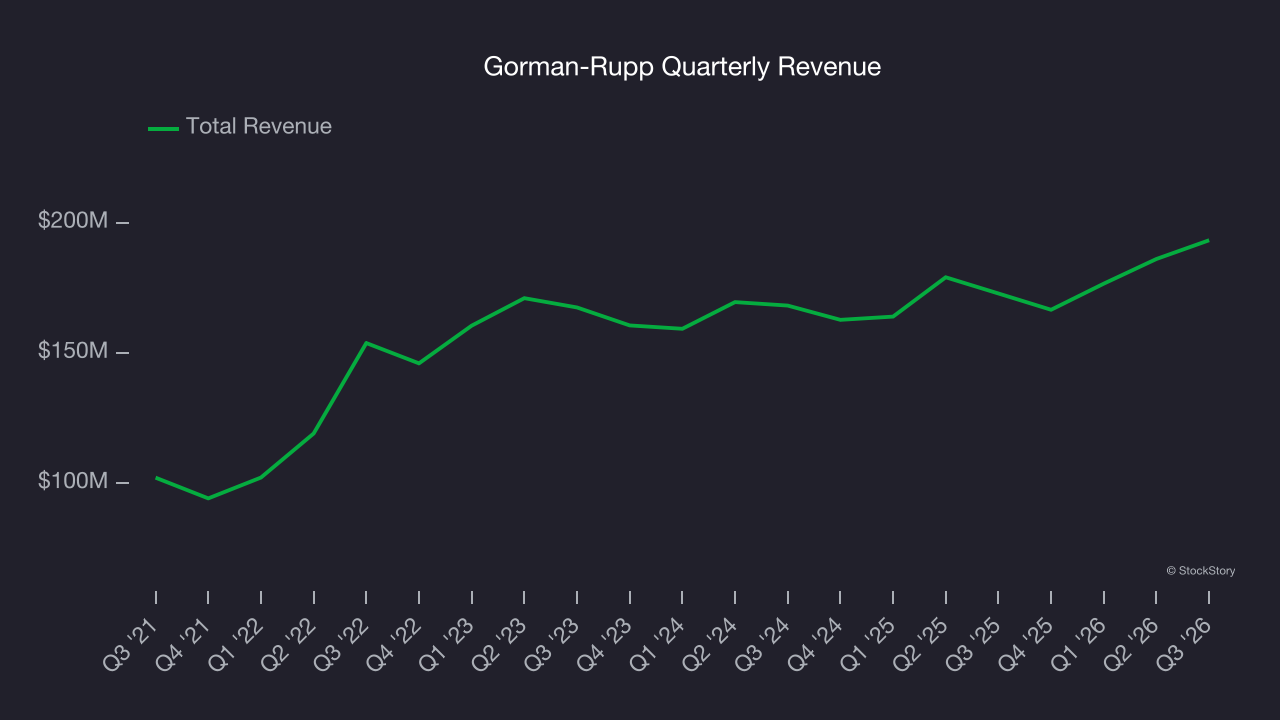
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Gorman-Rupp’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 4.8% over the last two years was well below its five-year trend. 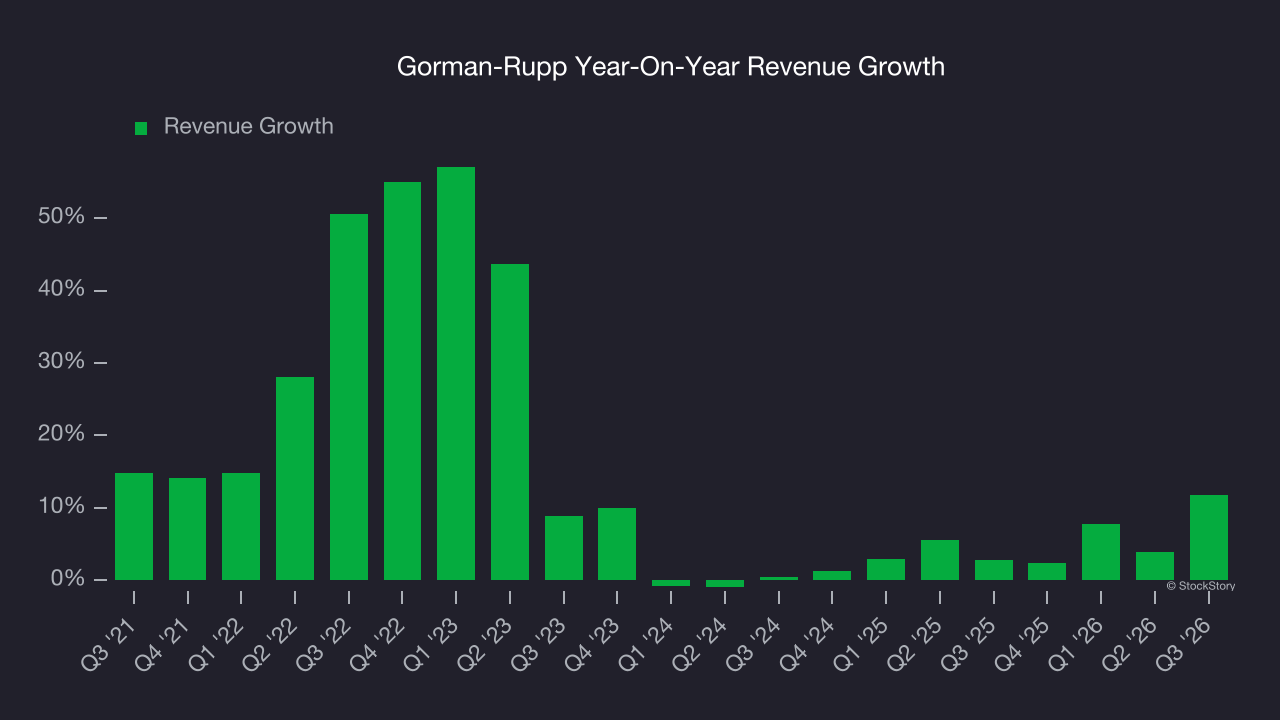
A closer look at the company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, provides more detail on its revenue dynamics. Gorman-Rupp’s backlog reached $236.8 million in the latest quarter and averaged 10.6% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating that the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for Gorman-Rupp’s products and services but raises concerns about capacity constraints. 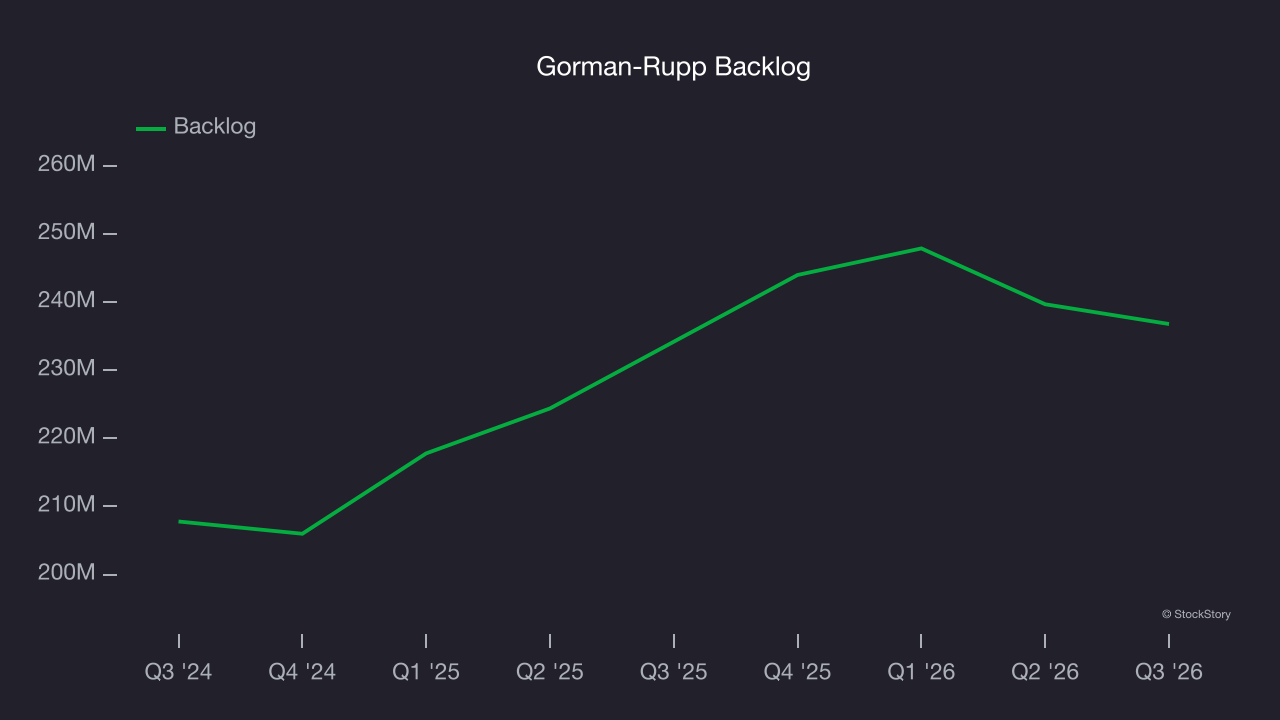
This quarter, Gorman-Rupp reported year-on-year revenue growth of 11.8%, and its $193.3 million of revenue exceeded Wall Street’s consensus estimates by 6.4%.
Looking ahead, sell-side analysts expect revenue to grow 4.8% over the next 12 months according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not lead to better top-line performance yet. On the positive side, the company is tracking well in other measures of financial health.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Gorman-Rupp has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 13.2%. This result was particularly notable given its low gross margin, which is mostly a factor of what it sells and requires substantial shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins despite low gross margins indicate well-managed operations.
Analyzing the trend in its profitability, Gorman-Rupp’s operating margin rose by 6.9 percentage points over the last five years, as its revenue growth provided operating leverage.
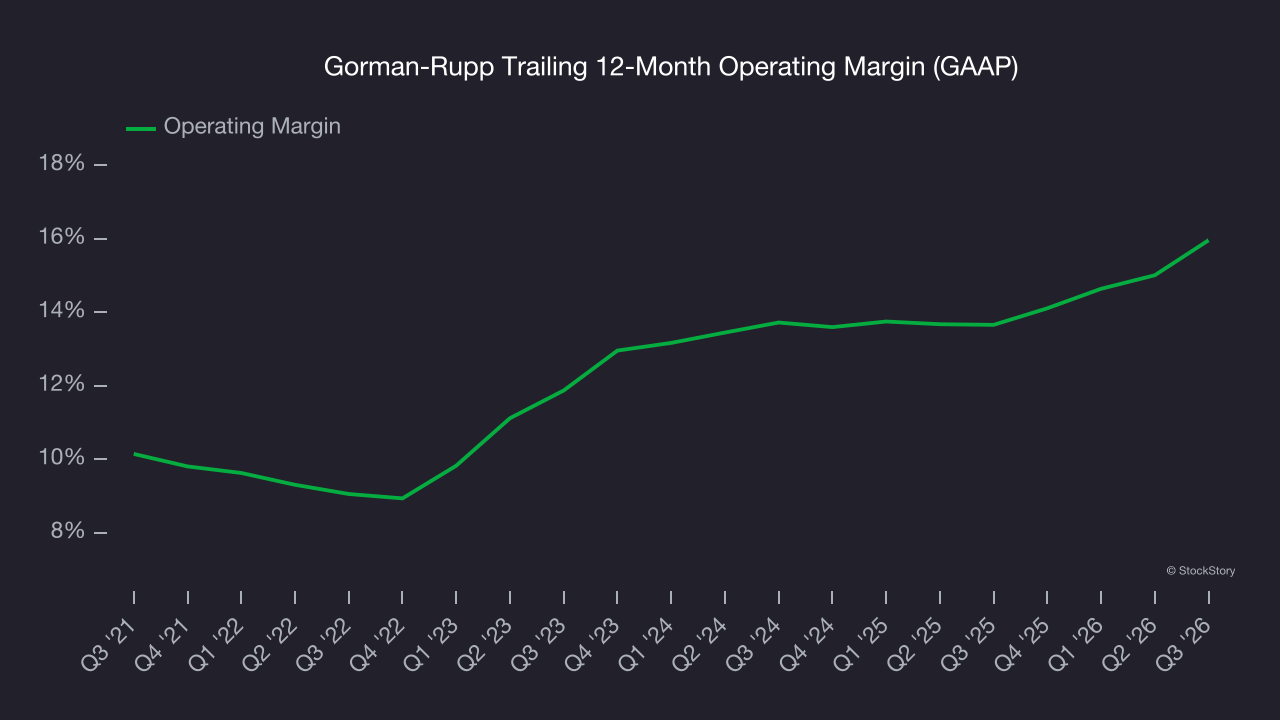
In Q3, Gorman-Rupp generated an operating margin of 17.5%, up 3.7 percentage points year on year. The increase was a positive sign, and the larger gain in operating margin than in gross margin suggests it managed expenses such as marketing, R&D and administrative overhead more efficiently.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Gorman-Rupp’s EPS grew at a 17.8% compounded annual growth rate over the last five years, higher than its 14.5% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
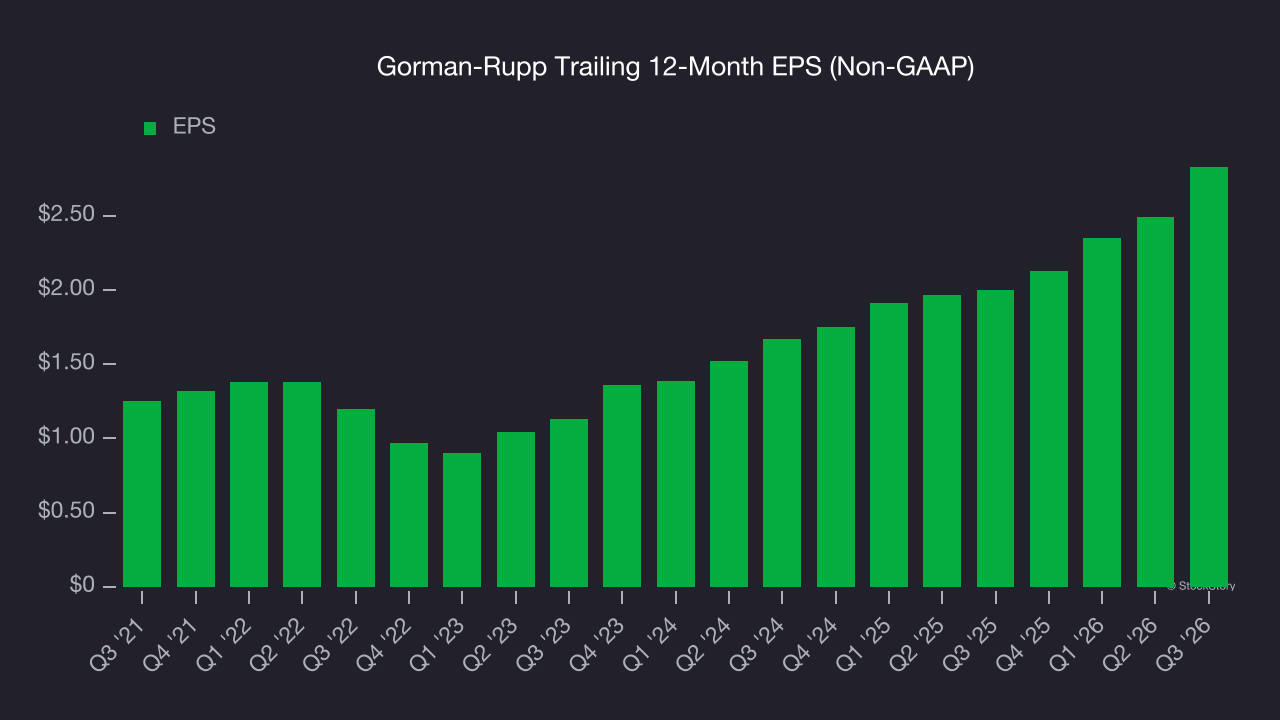
A closer look at Gorman-Rupp’s earnings quality helps explain the drivers of its performance. As mentioned earlier, Gorman-Rupp’s operating margin expanded by 6.9 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but reveal less about a company’s fundamentals.
As with revenue, shorter-term EPS trends can reveal changes in the business.
For Gorman-Rupp, its two-year annual EPS growth of 30.2% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Gorman-Rupp reported adjusted EPS of $0.86, up from $0.52 in the same quarter last year. EPS came in well above analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Gorman-Rupp’s full-year EPS to grow 8.7% from $2.83 to $3.07 according to S&P.
Key takeaways from Gorman-Rupp’s Q3 results
Gorman-Rupp delivered a solid quarter, with EBITDA and revenue both beating Wall Street’s consensus estimates by wide margins. Shares surged 5.4% to $73.94 immediately after the results.
Gorman-Rupp had a positive quarter, but one earnings result doesn’t necessarily make the stock a buy. That decision also requires considering its valuation and business quality alongside the latest quarter. For more on those factors, read the full research report here (it’s free).