Commercial banking company Preferred Bank (NASDAQ: PFBC) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 4.4% year on year to $71.7 million. Its GAAP profit of $2.73 per share was 1.6% above analysts’ consensus estimates.
For more on Preferred Bank, read the full research report for free.
Preferred Bank (PFBC) Q3 2026 highlights:
- Net Interest Income: $66.71 million vs analysts’ consensus estimates of $68.92 million (6.4% year-on-year decline, 3.2% miss)
- Net Interest Margin: 3.5% vs analysts’ consensus estimates of 3.6% (6.8 basis point miss)
- Revenue: $71.7 million vs analysts’ consensus estimates of $73.09 million (4.4% year-on-year decline, 1.9% miss)
- Efficiency Ratio: 30.9% vs analysts’ consensus estimates of 32.4% (145.3 basis point beat)
- EPS (GAAP): $2.73 vs analysts’ consensus estimates of $2.69 (1.6% beat)
- Tangible Book Value per Share: $66.85 vs analysts’ consensus estimates of $68.68 (6.4% year-on-year growth, 2.7% miss)
- Market Capitalization: $1.25 billion
Revenue growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management and trading operations provide additional income. Unfortunately, Preferred Bank’s 9.1% annualized revenue growth over the last five years was mediocre. This fell short of the benchmark for the banking sector and provides a weak baseline.
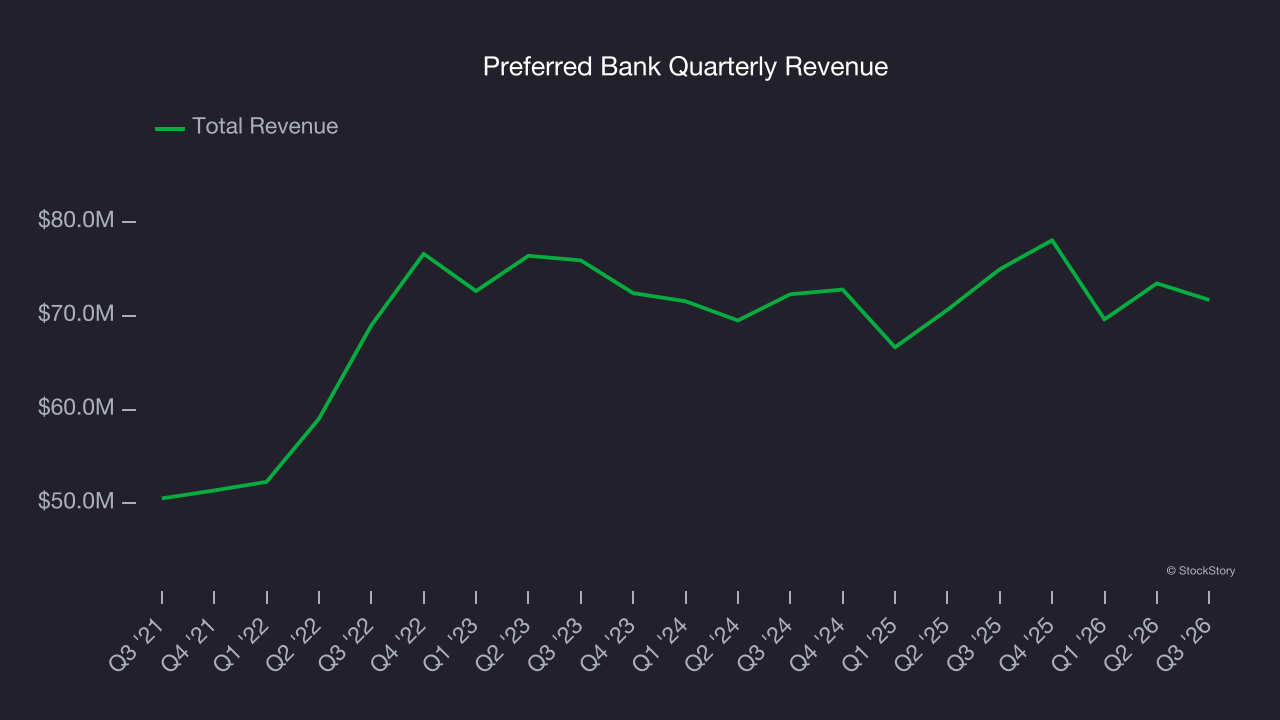
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Preferred Bank’s recent performance shows its demand has slowed as its annualized revenue growth of 1.2% over the last two years was below its five-year trend. Slowing revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 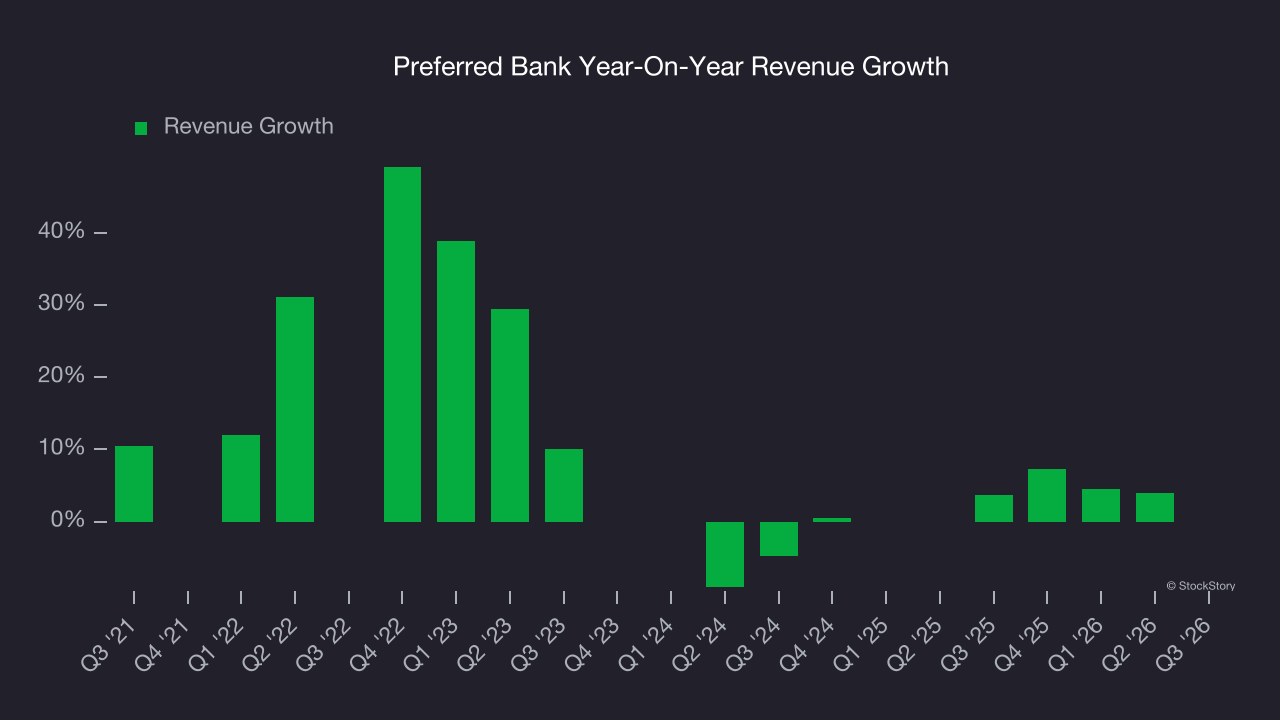 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Preferred Bank missed Wall Street’s consensus estimates and reported a disappointing 4.4% year-on-year revenue decline, generating $71.7 million of revenue.
Net interest income made up 95.3% of the company’s total revenue during the last five years, meaning Preferred Bank depends heavily on its lending activities because non-interest income contributes little.
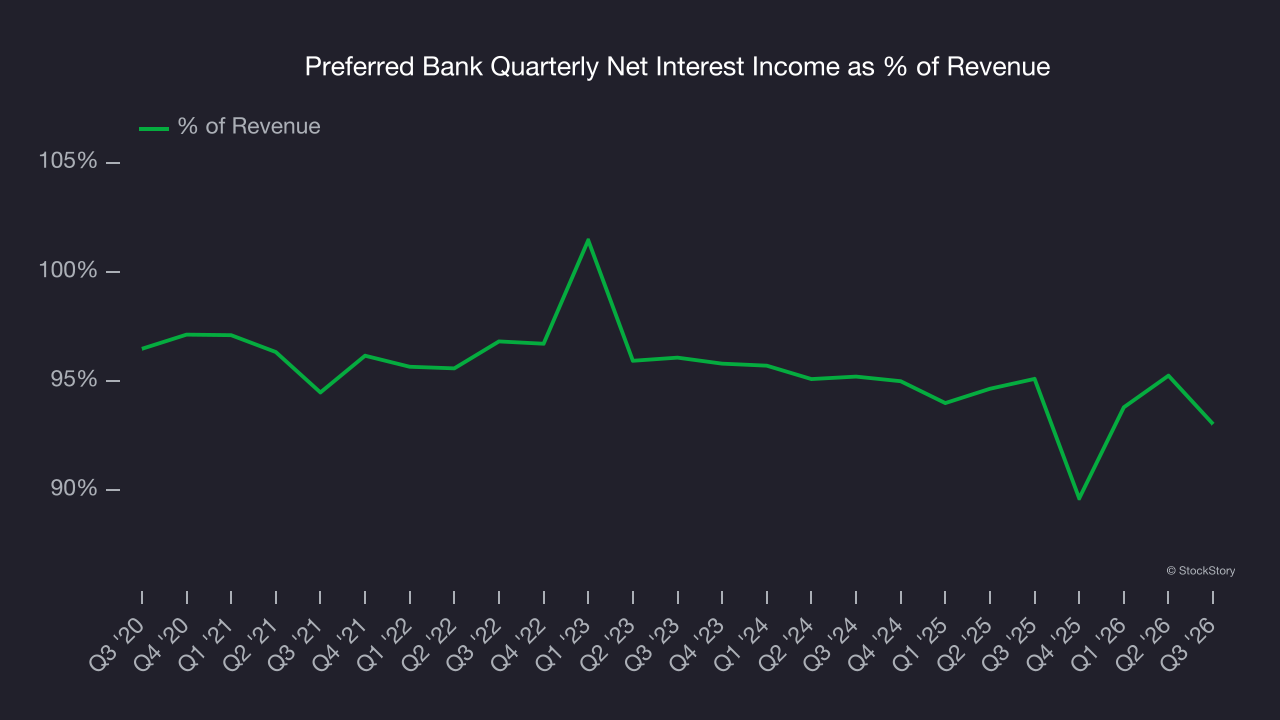
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone – its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
Tangible book value per share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
When analyzing banks, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates genuine per-share value by removing intangible assets of debatable liquidation worth. EPS can become murky due to acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists financial engineering manipulation.
Preferred Bank’s TBVPS grew at an annual rate of 11.8% over the last five years. However, TBVPS growth has recently slowed to 8.7% annually over the last two years (from $56.54 to $66.85 per share).
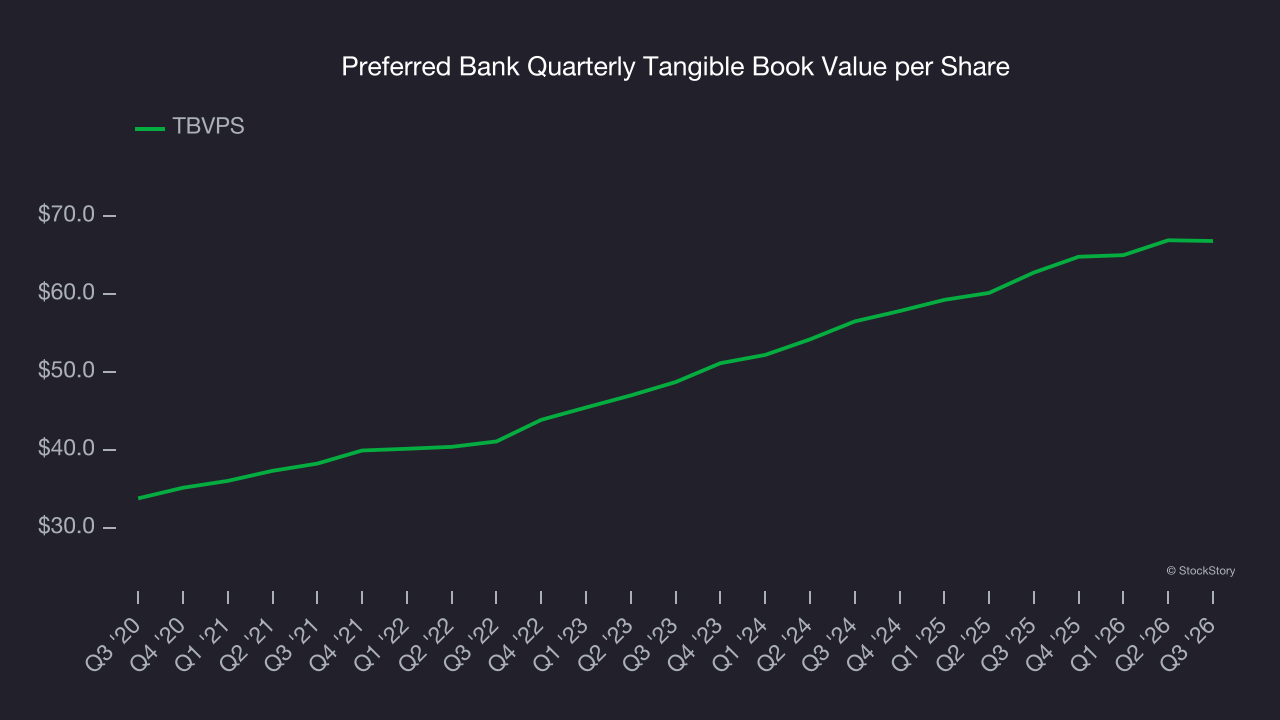
Over the next 12 months, consensus estimates call for Preferred Bank’s TBVPS to grow by 13.9% to $76.15, a decent growth rate.
Key takeaways from Preferred Bank’s Q3 results
Preferred Bank’s third quarter offered few positives: both net interest income and revenue fell short of Wall Street’s consensus estimates. It was a disappointing quarter overall. Shares remained flat at $108.62 immediately after the results.
If you’re considering an investment in Preferred Bank, look at the bigger picture of valuation, business quality and the latest earnings. For more on those factors, read our full research report here (it’s free).