Rail transportation company Greenbrier (NYSE: GBX) fell short of the market’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026), with revenue falling 22.2% year on year to $591 million. On the other hand, the company’s full-year revenue guidance of $3 billion at the midpoint came in 11.9% above analysts’ consensus estimates. Its GAAP profit of $0.27 per share was 67.9% below analysts’ consensus estimates.
For more on Greenbrier, read our free full research report.
Greenbrier (GBX) Q3 CY2026 highlights:
- Revenue $591 million vs S&P analysts’ consensus estimates of $605.2 million (22.2% year-on-year decline, 2.4% miss)
- EPS (GAAP) $0.27 vs analysts’ consensus estimates of $0.84 (67.9% miss)
- Adjusted EBITDA $72.3 million vs analysts’ consensus estimates of $77.34 million (12.2% margin, 6.5% miss)
- GAAP EPS guidance $3.25 at the midpoint for fiscal 2027, missing analysts’ consensus estimates by 10.3%
- Operating margin 4.3%, down from 9.5% in the same quarter last year
- Market capitalization $1.18 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Unfortunately, Greenbrier’s 7.1% annualized revenue growth over the last five years was mediocre. This fell short of the benchmark for the industrials sector.
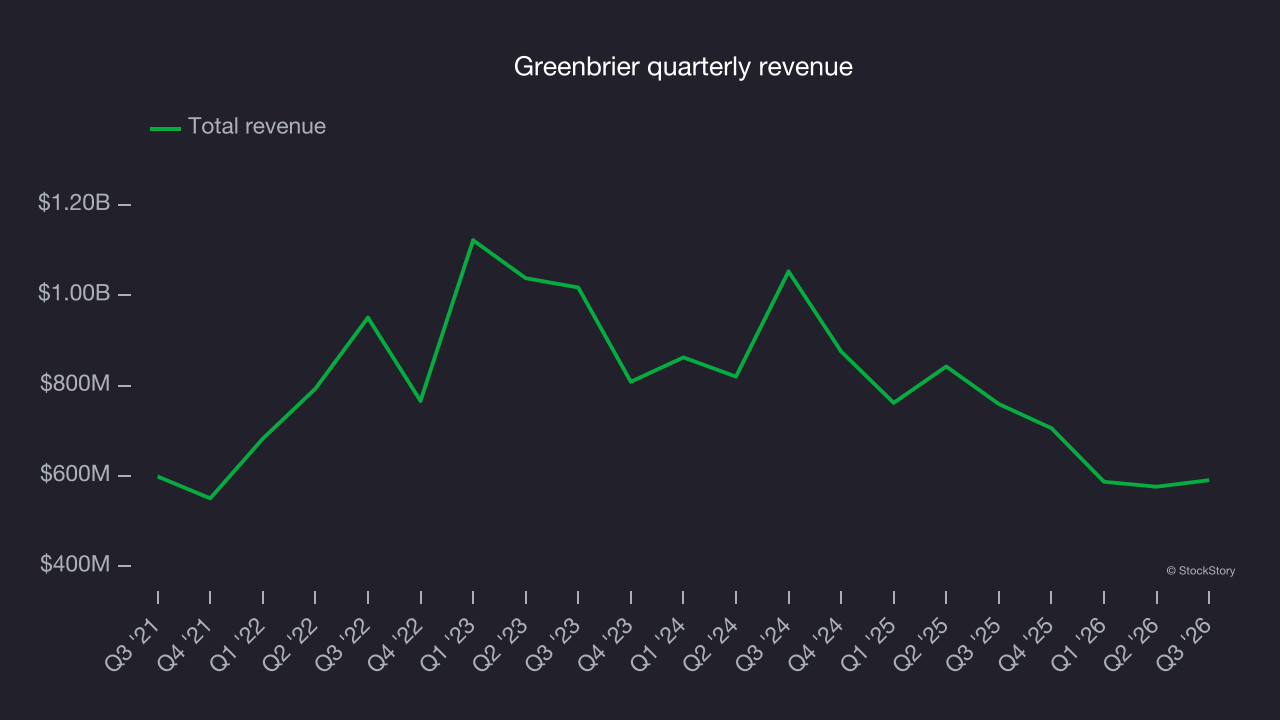
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Greenbrier’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 16.7% annually.
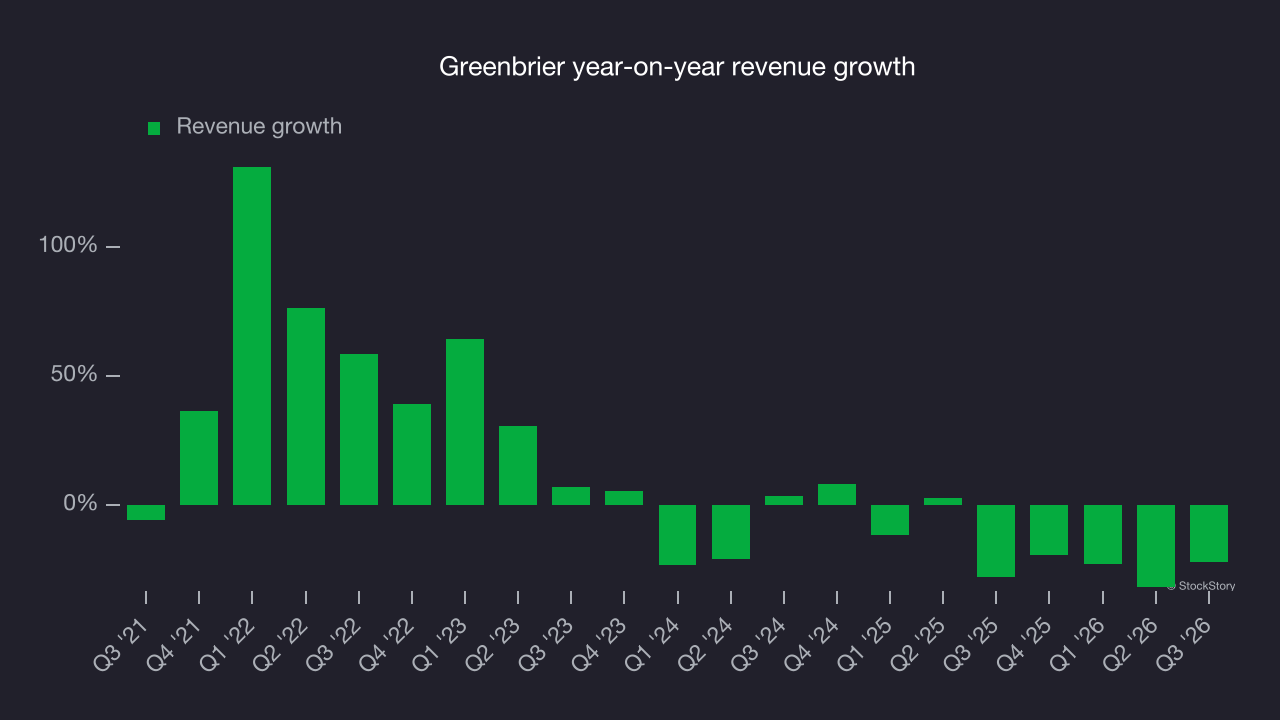
This quarter, Greenbrier missed Wall Street’s consensus estimates and reported a disappointing 22.2% year-on-year revenue decline, generating $591 million of revenue.
Looking ahead, sell-side analysts expect revenue to grow 5.6% over the next 12 months, according to S&P. While this projection suggests its newer products and services will fuel better top-line performance, it is still below average for the sector.
Operating margin
Greenbrier was profitable over the last five years but held back by its large cost base. Its average operating margin of 6.9% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, Greenbrier’s operating margin rose by 1.9 percentage points over the last five years, as its revenue growth provided operating leverage.
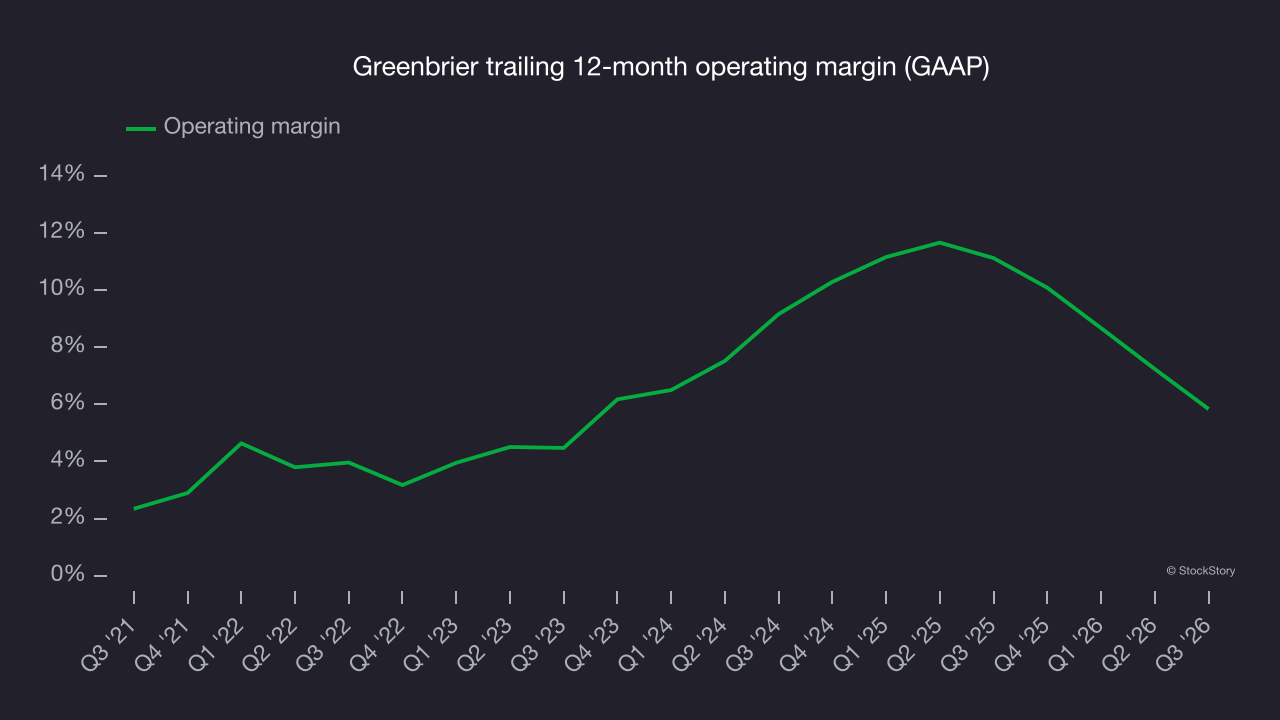
In Q3, Greenbrier generated an operating margin of 4.3%, down 5.2 percentage points year on year. Since Greenbrier’s gross margin decreased more than its operating margin, this suggests its recent inefficiencies were driven more by weaker leverage on its cost of sales than by increased marketing, R&D and administrative overhead expenses.
Earnings per share
Long-term changes in earnings per share (EPS) matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Greenbrier’s EPS grew at a 22.5% compounded annual growth rate over the last five years, higher than its 7.1% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
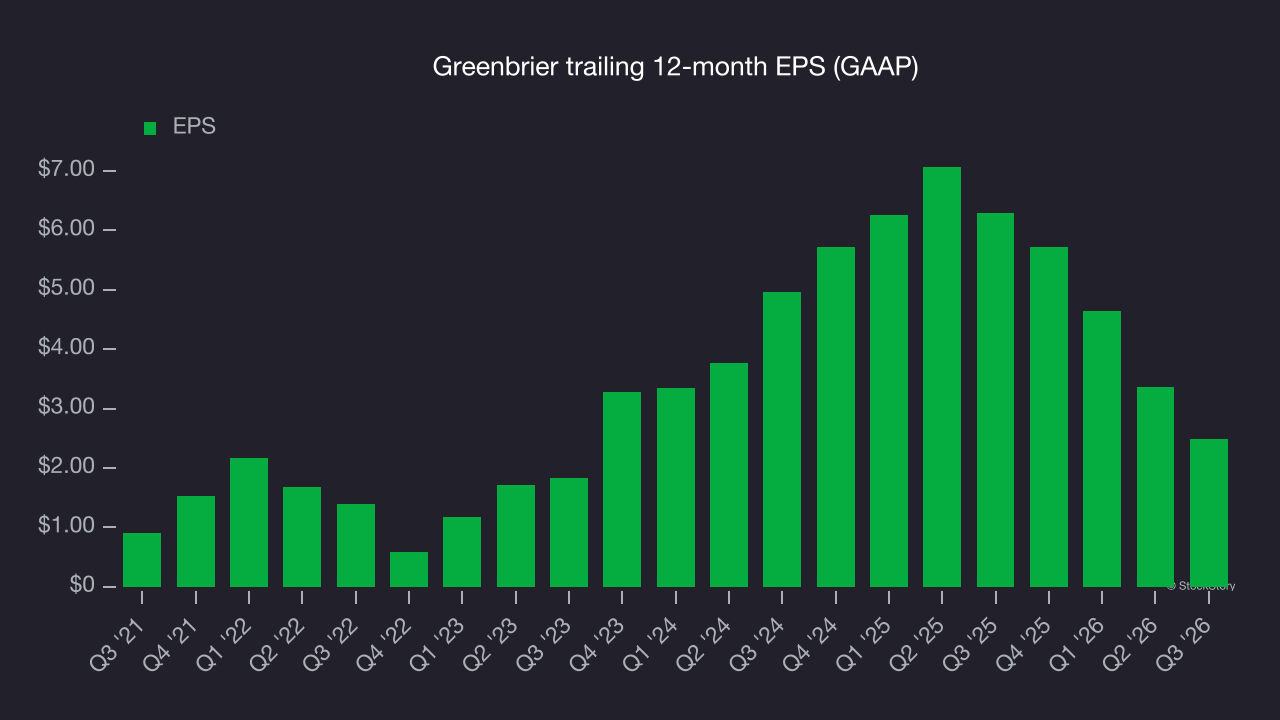
A closer look at Greenbrier’s earnings quality helps explain the drivers of its performance. As mentioned earlier, Greenbrier’s operating margin declined this quarter but expanded by 1.9 percentage points over the last five years. Its share count also shrank by 5.1%, and these factors together are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth.
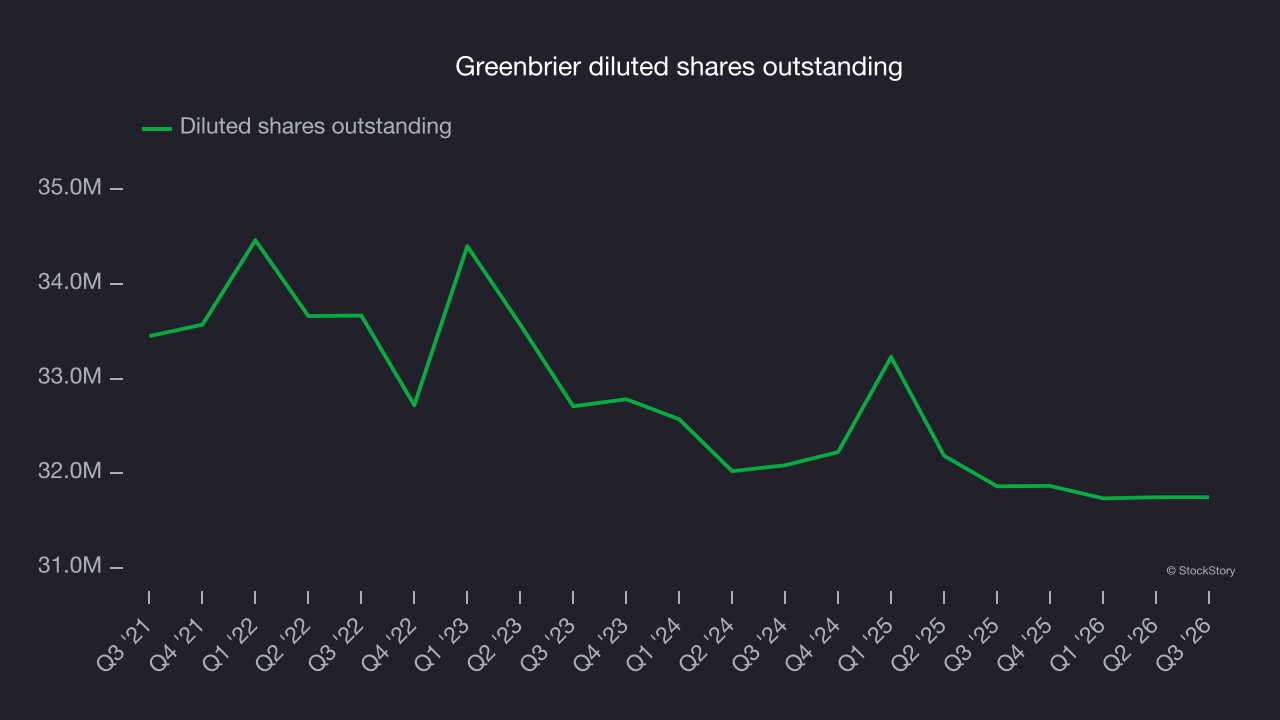
As with revenue, examining EPS over a shorter period can reveal changes in the business.
Greenbrier’s two-year annual EPS declines of 29.3% mark a reversal from its seemingly healthy five-year trend.
In Q3, Greenbrier reported EPS of $0.27, down from $1.15 in the same quarter last year. This result missed analysts’ consensus estimates, but long-term EPS growth matters more than short-term movements. There is insufficient data to assess expected EPS growth based on Wall Street analysts’ consensus projections.
Key takeaways from Greenbrier’s Q3 results
Greenbrier’s full-year guidance sent a mixed signal: Revenue was well above analysts’ consensus estimates, but EPS fell short. Revenue for the quarter also missed Wall Street’s consensus estimates. Taken together, the results left room for improvement. Shares fell 4.8% to $36.39 immediately after the report.
Greenbrier’s earnings report left more to be desired. The next question is whether the stock offers value after this quarter. That decision should take into account its valuation, business quality and latest quarterly results. For more on those factors, read our full research report here (it’s free).