Insurance and financial services company The Hartford (NYSE: HIG) fell short of the market’s revenue expectations in Q3 2026, with revenue flat year on year at $7.22 billion. Its non-GAAP profit of $3.50 per share was 10.4% above analysts’ consensus estimates.
For more on Hartford, read our free full research report.
Hartford (HIG) Q3 2026 highlights:
- Net premiums earned $6.35 billion vs analysts’ consensus estimates of $4.63 billion (37.2% beat)
- Revenue $7.22 billion vs S&P analysts’ consensus estimates of $7.41 billion (2.5% miss)
- Combined ratio 81.1% vs analysts’ consensus estimates of 92.3% (1,123 basis point beat)
- Adjusted EPS $3.50 vs S&P analysts’ consensus estimates of $3.17 (10.4% beat)
- Book value per share $69.10 vs analysts’ consensus estimates of $82.38 (6.7% year-on-year growth, 16.1% miss)
- Market capitalization $37.04 billion
Revenue growth
Insurers earn revenue three ways. The core insurance business itself, often called underwriting and represented in the income statement as premiums earned, is one way. Investment income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities is the second way. Fees from various sources such as policy administration, annuities or other value-added services are the third. Hartford’s revenue grew at a tepid 5.6% compounded annual growth rate over the last five years. This fell short of the standard for the insurance sector.
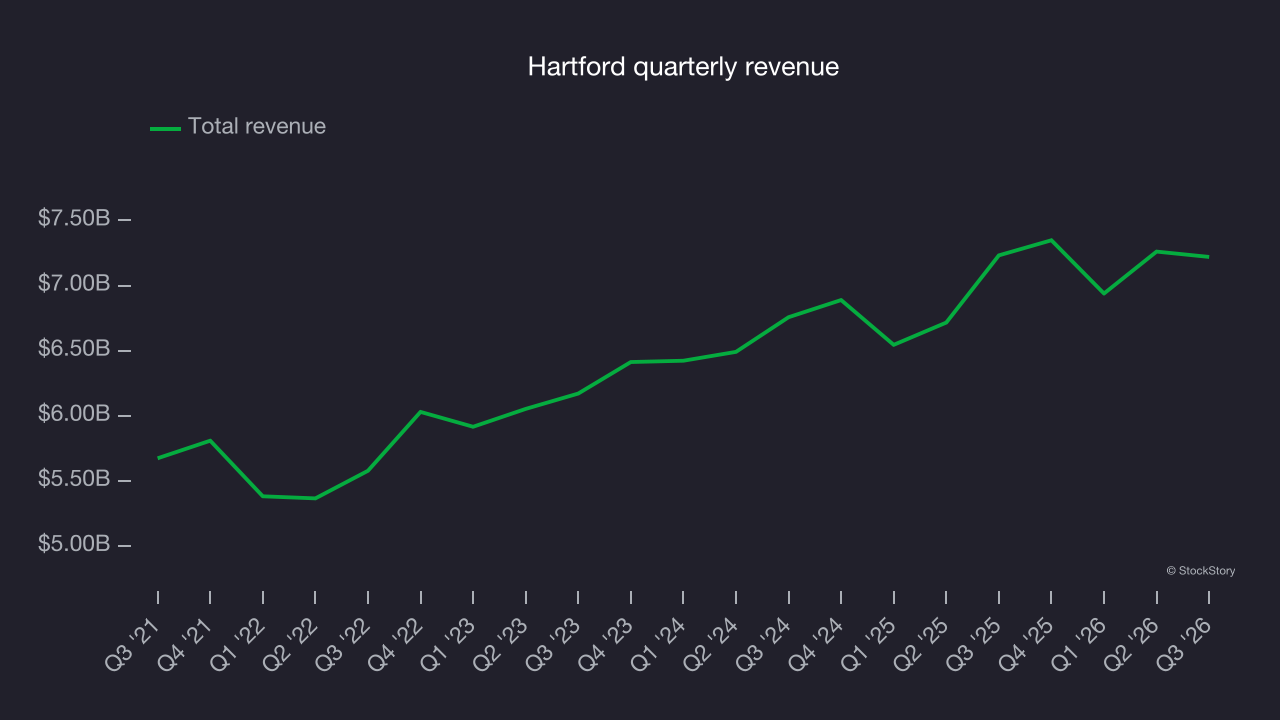
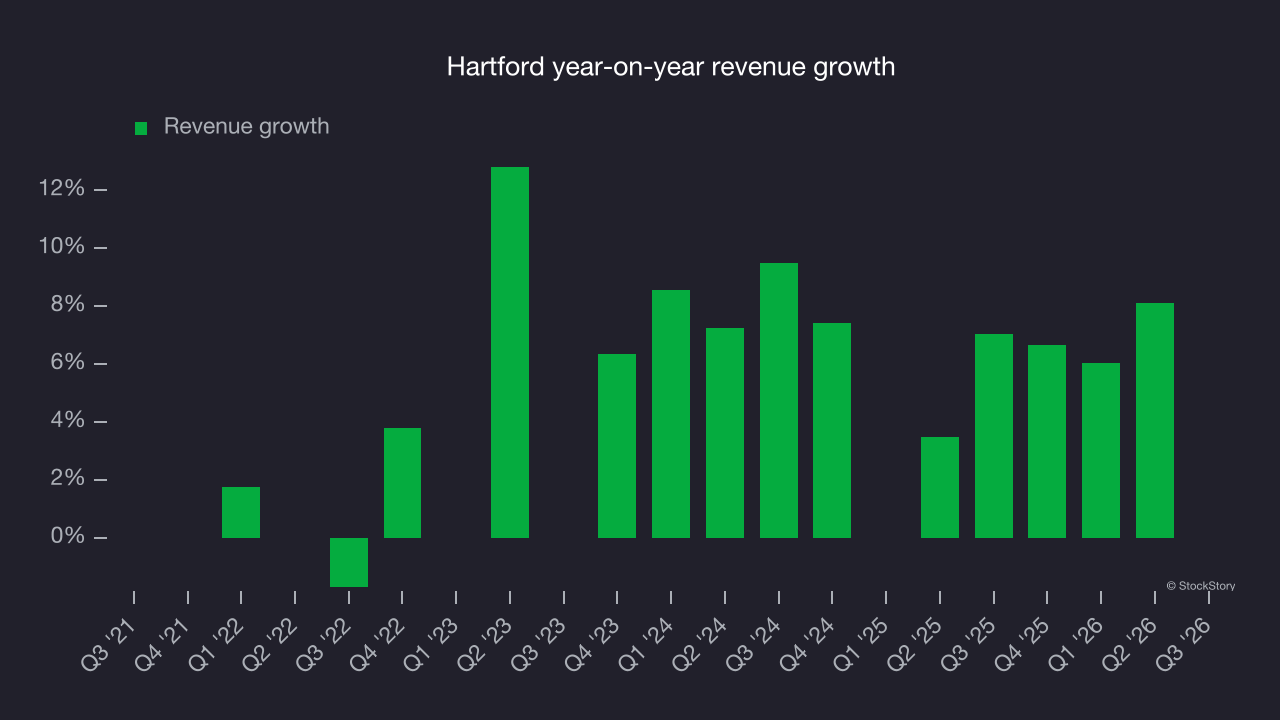
This quarter, Hartford’s $7.22 billion of revenue, falling short of Wall Street’s consensus estimates.
Net premiums earned made up 90.2% of the company’s total revenue during the last five years, meaning Hartford depends heavily on its underwriting activities because non-insurance operations contribute little to revenue.
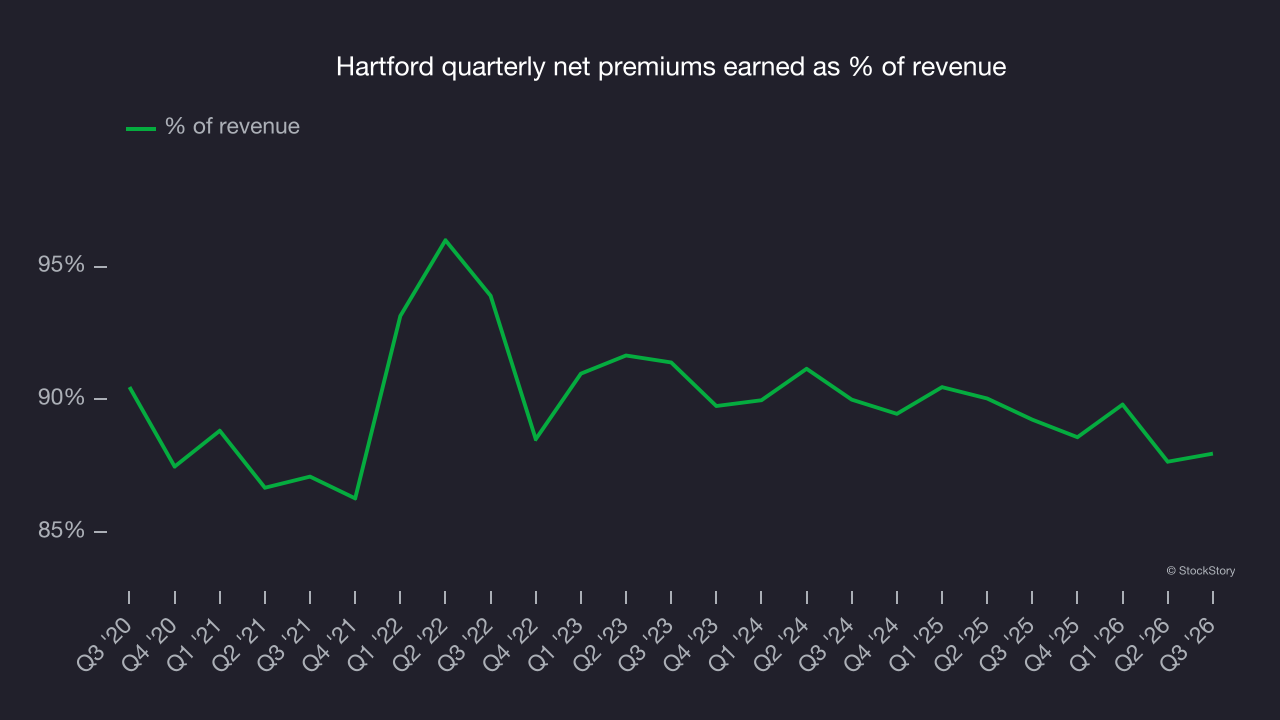
Markets consistently prioritize net premiums earned growth over investment and fee income, recognizing its superior quality as a core indicator of the company’s underwriting success and market penetration.
Book value per share (BVPS)
Insurance companies are balance sheet businesses, collecting premiums upfront and paying out claims over time. The float (premiums collected but not yet paid out) is invested, creating an asset base supported by a liability structure. Book value per share (BVPS) captures this dynamic by measuring these assets (investment portfolio, cash, reinsurance recoverables) less liabilities (claim reserves, debt, future policy benefits). BVPS is essentially the residual value for shareholders.
BVPS is therefore important to track for insurers and sheds light on business quality because it reflects long-term capital growth and is harder to manipulate than more commonly used metrics like EPS.
Hartford’s BVPS grew at a mediocre 6.1% annual rate over the last five years. However, BVPS growth has accelerated recently, rising by 9.8% annually over the last two years from $57.34 to $69.10 per share.
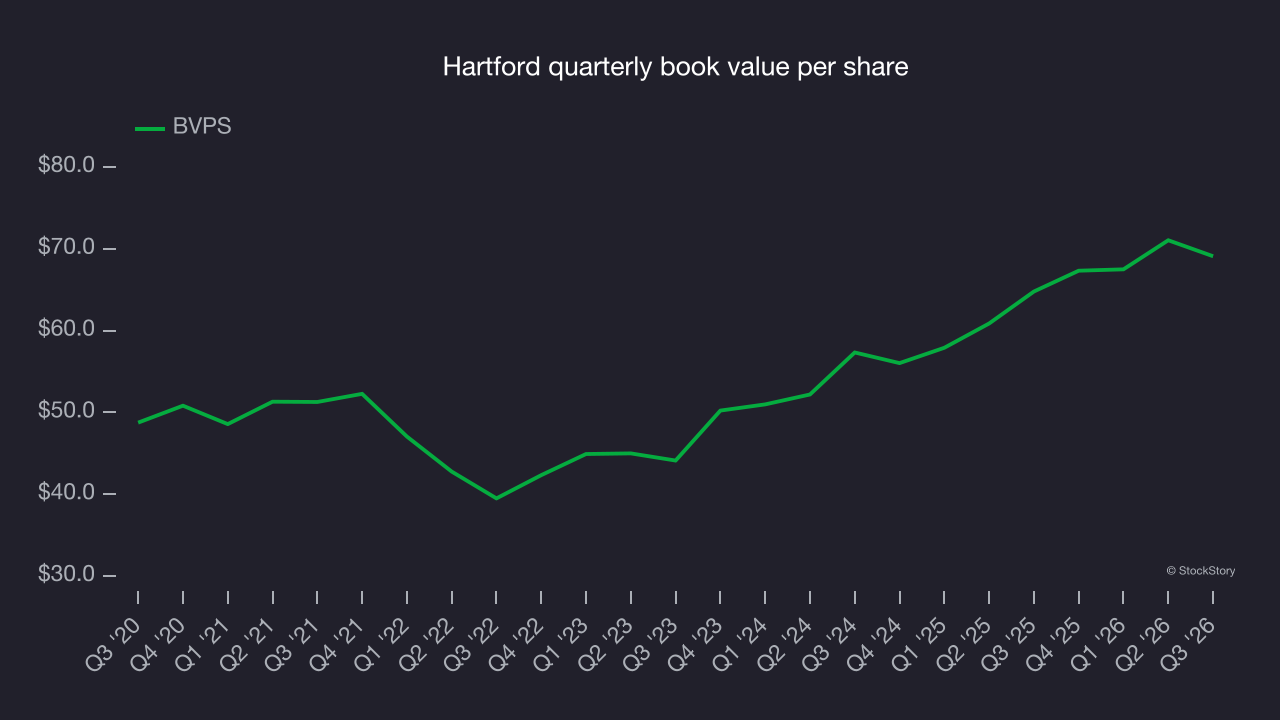
Over the next 12 months, consensus estimates call for Hartford’s BVPS to grow by 32.6% to $82.38, a high growth rate.
Key takeaways from Hartford’s Q3 results
Hartford’s quarter was weaker overall, with revenue below Wall Street’s consensus estimates and a miss on book value per share. Those shortfalls contrasted with net premiums earned well above analysts’ consensus estimates and EPS that also topped Wall Street’s consensus. Shares remained flat at $136.31 immediately after the report.
Is Hartford an attractive investment at the current price? That decision should take into account valuation, business quality and the latest earnings. Read the full research report for more on Hartford (it’s free).