Building products manufacturer Simpson (NYSE: SSD) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 2.3% year on year to $638.1 million. Its GAAP profit of $2.68 per share was 9.5% above analysts’ consensus estimates.
For more on Simpson, read our free full research report.
Simpson (SSD) Q3 2026 highlights:
- Revenue $638.1 million vs S&P analysts’ consensus estimates of $625.2 million (2.3% year-on-year growth, 2.1% beat)
- EPS (GAAP) $2.68 vs analysts’ consensus estimates of $2.45 (9.5% beat)
- Adjusted EBITDA $167.2 million vs analysts’ consensus estimates of $152.7 million (26.2% margin, 9.5% beat)
- Operating margin 22.1%, up from 20.4% in the same quarter last year
- Market capitalization $7.56 billion
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Over the last five years, Simpson grew its revenue at a compound annual rate of 11%. Its growth beat the average industrials company and shows its offerings resonate with customers.
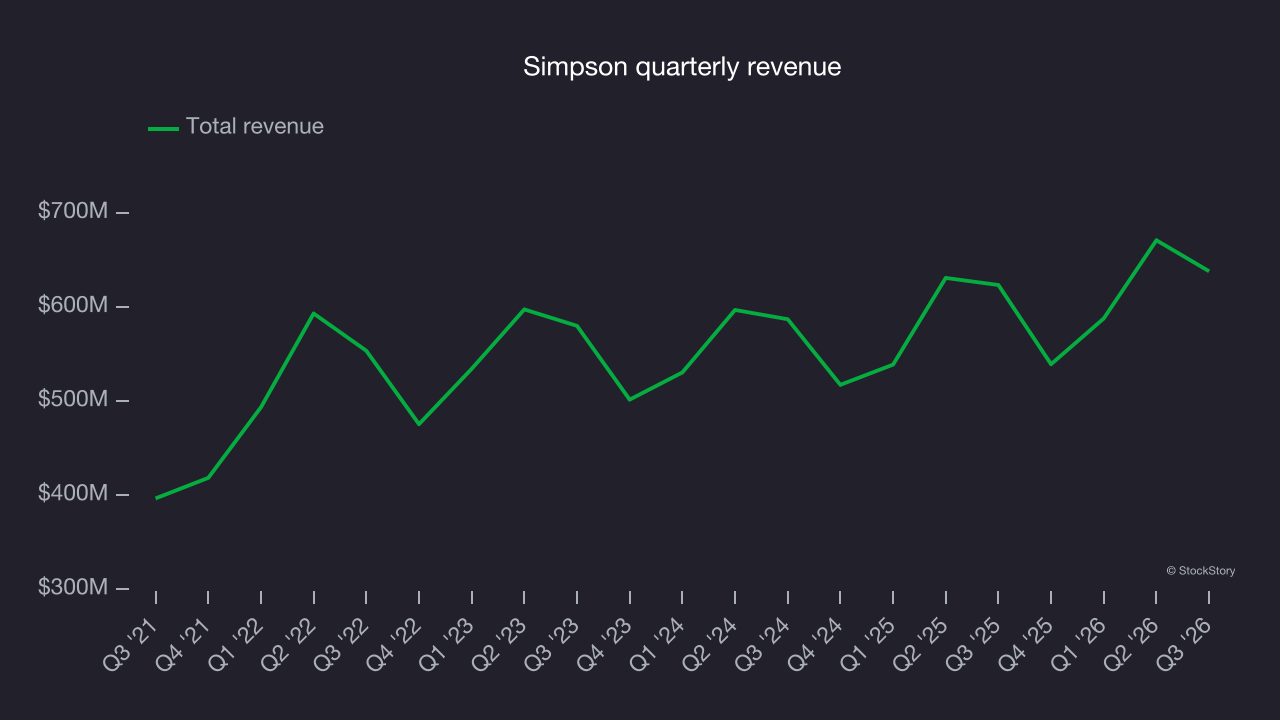
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Simpson’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 4.8% over the last two years was well below its five-year trend. 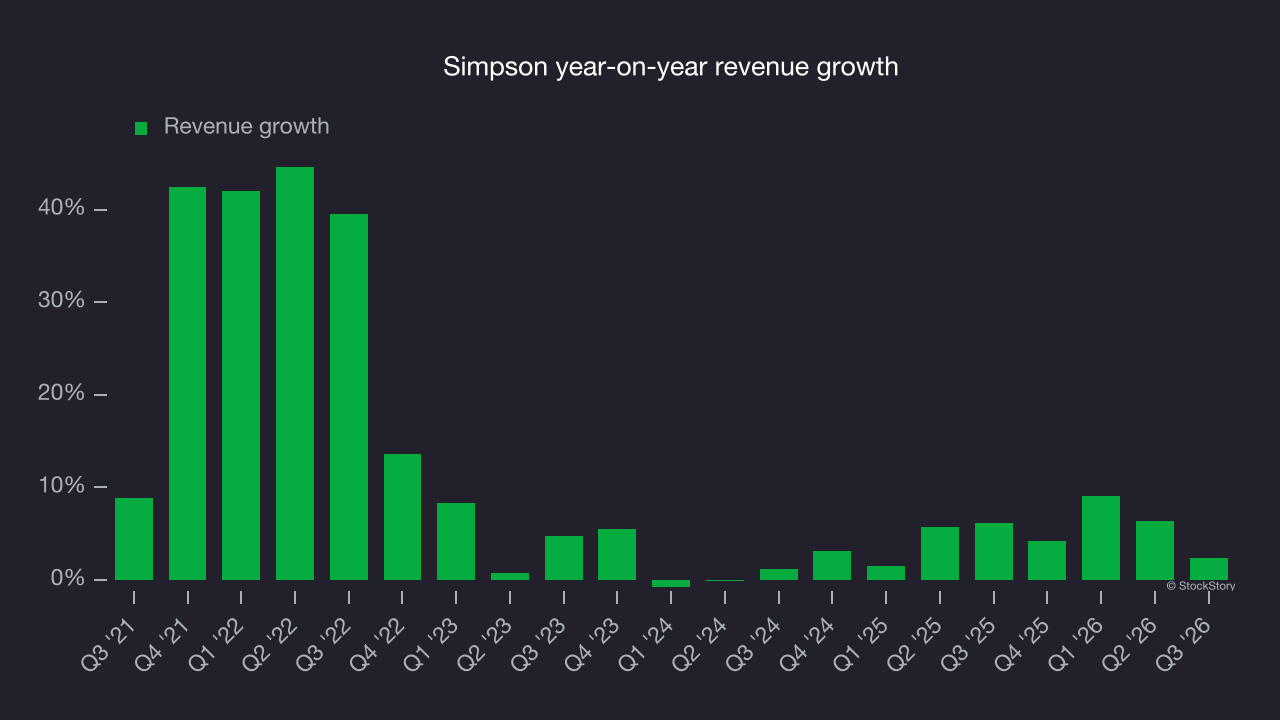
This quarter, Simpson reported modest year-on-year revenue growth of 2.3% but beat Wall Street’s consensus estimates by 2.1%.
Looking ahead, sell-side analysts expect revenue to grow 1.4% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection suggests its products and services will face some demand challenges.
Operating margin
Simpson has performed well over the last five years. It demonstrated high profitability for an industrials business, with an average operating margin of 21.1%. That outcome is unsurprising given its favorable gross margin baseline.
Looking at the trend in its profitability, Simpson’s operating margin decreased by 3.6 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
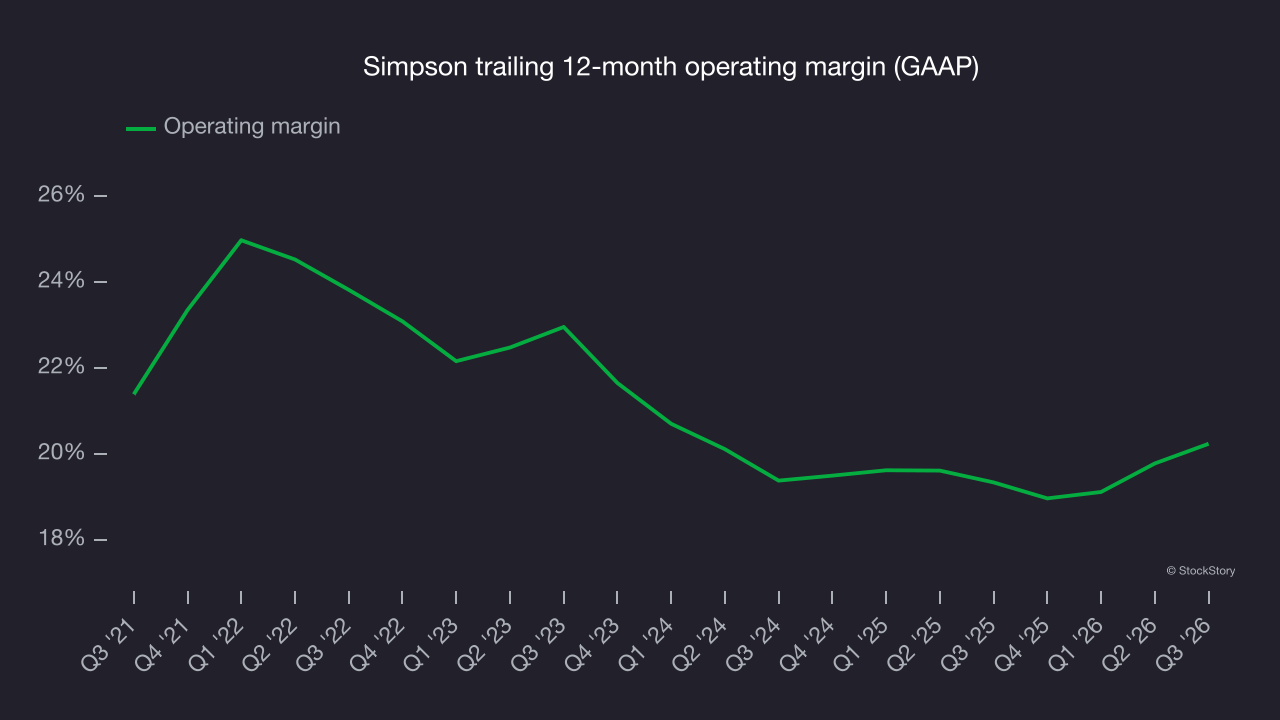
This quarter, Simpson generated an operating margin of 22.1%, up 1.7 percentage points year on year. The increase was encouraging, and operating margin rose more than gross margin, indicating greater efficiency in expenses such as marketing, R&D and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Simpson’s 12.2% annual EPS growth over the last five years aligns with its revenue performance. This indicates it maintained its per-share profitability as it expanded.
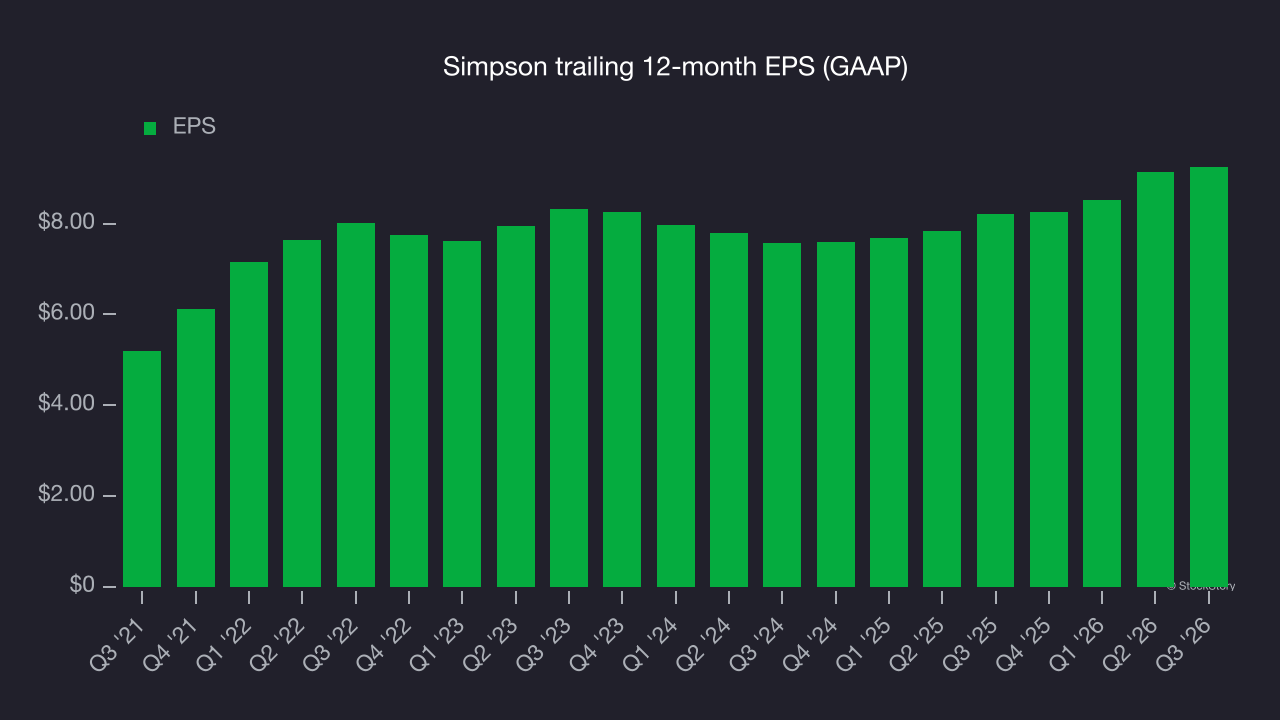
As with revenue, a more recent view of EPS can provide insight into an emerging theme or development for the business.
Simpson’s two-year annual EPS growth of 10.5% was good and topped its 4.8% two-year revenue growth.
A closer look at Simpson’s earnings quality helps explain the drivers of its performance. A two-year view shows that Simpson has repurchased its stock, shrinking its share count by 3.8%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 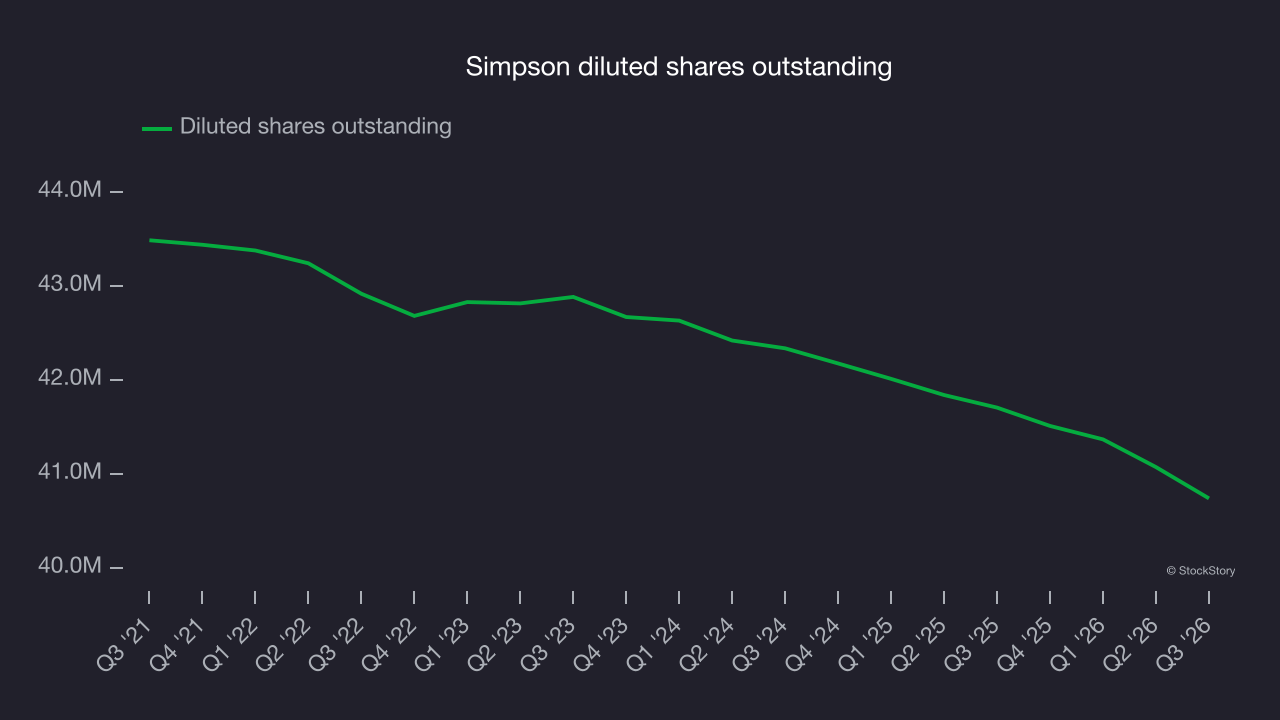
In Q3, Simpson reported EPS of $2.68, up from $2.58 in the same quarter last year. The result easily cleared analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Simpson’s full-year EPS to stay about the same, moving from $9.25 to $9.34, according to S&P.
Key takeaways from Simpson’s Q3 results
Simpson delivered a good quarter, led by EBITDA that came in well above analysts’ consensus estimates and revenue that also topped Wall Street’s expectations. Those beats were key positives in the results. Shares remained flat at $181.80 immediately after the release.
Is Simpson a buy at its current price? That decision calls for a look at its valuation, business qualities and latest quarterly results. Read the full research report here (it’s free).