Over the last six months, Constellation Brands’s shares have sunk to $130.93, producing a disappointing 15.7% loss - a stark contrast to the S&P 500’s 7.5% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Constellation Brands, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why is Constellation Brands not exciting?
Despite the more favorable entry price, we don’t have much confidence in Constellation Brands. Here are three reasons you should be careful with STZ, plus one stock we’d rather own.
1. Core business falling behind as organic sales decline
When analyzing revenue growth, we care most about organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions, and divestitures as well as foreign currency fluctuations.
Constellation Brands’s demand has been falling over the last eight quarters, and on average, its organic sales have declined by 1.4% year on year. 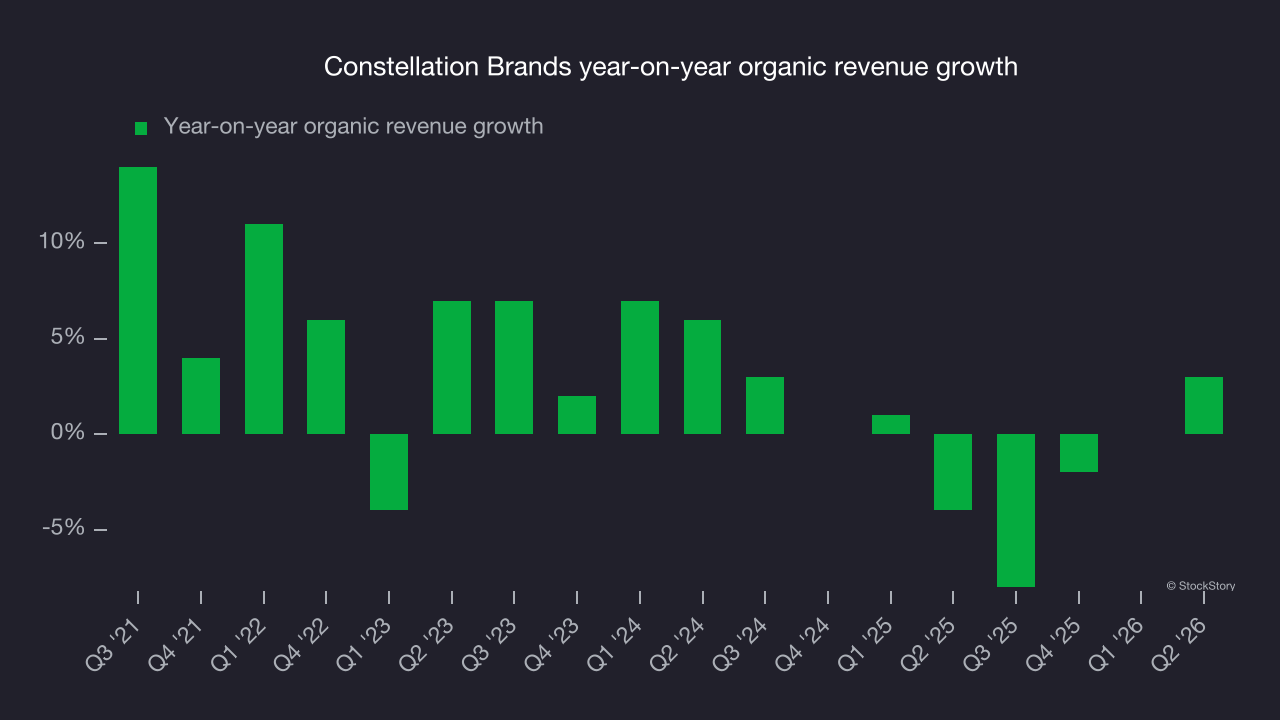
2. Projected revenue growth shows limited upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Constellation Brands’s revenue to stall, according to S&P. Although this projection indicates its newer products will spur better top-line performance, it is still below average for the sector.
3. EPS barely growing
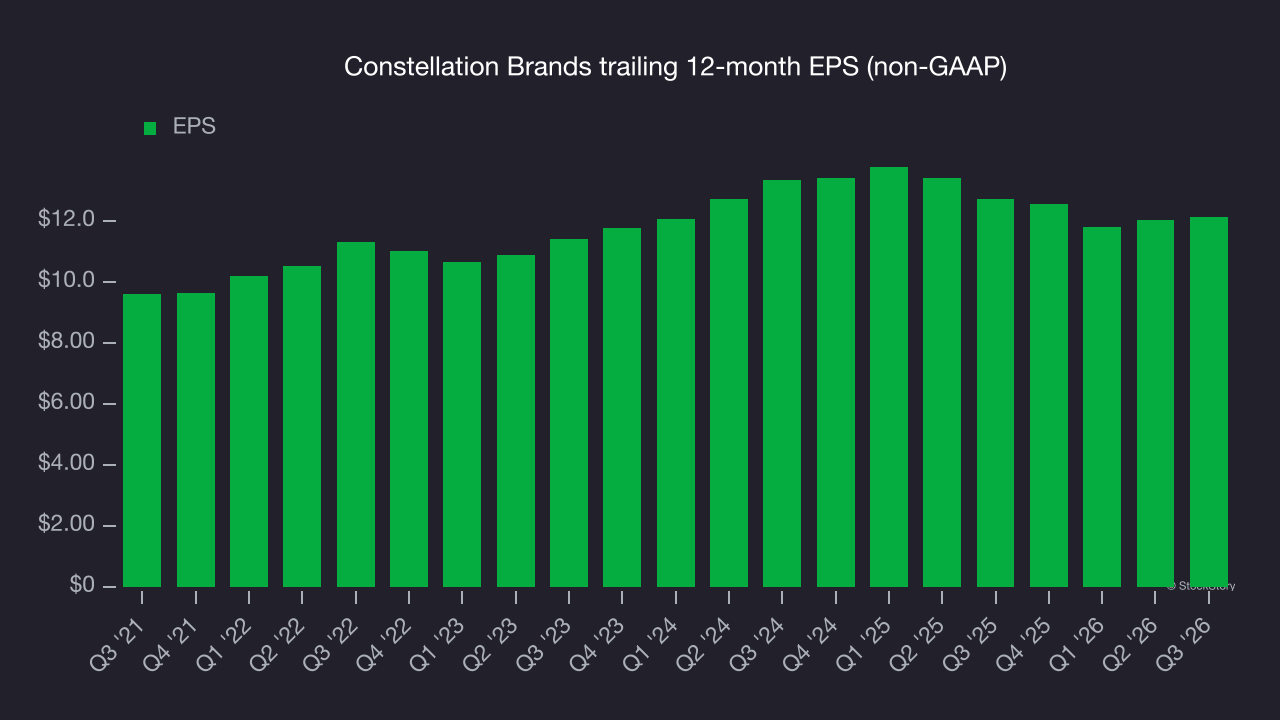
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Constellation Brands’s EPS grew at 2% compounded annual growth rate over the last three years. On the bright side, this performance was better than its 2% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
Final judgment
Constellation Brands isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 11.4× forward P/E (or $130.93 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better stocks to buy right now. Let us point you toward an all-weather company that owns household favorite Taco Bell.
High-quality stocks for all market conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.