


Household products company Church & Dwight (NYSE: CHD) beat Wall Street’s revenue expectations in Q3 2026, with revenue rising 1% year on year to $1.60 billion. On the other hand, next quarter’s revenue guidance of $1.64 billion was less impressive, coming in 1.4% below analysts’ consensus estimates. Its non-GAAP profit of $0.92 per share was 2.2% above analysts’ consensus estimates.
For more on Church & Dwight, read our full research report, which is free.
Church & Dwight (CHD) Q3 2026 highlights:
- Revenue $1.60 billion vs S&P analysts’ consensus estimates of $1.58 billion (1% year-on-year growth, 1.6% beat)
- Adjusted EPS $0.92 vs S&P analysts’ consensus estimates of $0.90 (2.2% beat)
- Revenue guidance $1.64 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $1.66 billion
- Adjusted EPS guidance $3.76 at the midpoint for the full year, roughly in line with what analysts were expecting
- Operating margin 18.2%, up from 16.1% in the same quarter last year
- Free cash flow margin 21.8%, down from 25.7% in the same quarter last year
- Organic revenue rose 5.1% year on year (beat)
- Market capitalization $25.14 billion
“We continue to execute with excellence in a challenging environment,” said Mr. Dierker. “Our focus remains on providing consumers with high-quality, solution-oriented products at the right value. Our improved sales outlook reflects the strength of our operating fundamentals, which underpin our volume growth, market share gains and gross margin expansion.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $6.25 billion in revenue over the past 12 months, Church & Dwight carries some recognizable products but is a mid-sized consumer staples company. Its size could bring disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale.
Church & Dwight grew its revenue at a sluggish 2.6% compounded annual growth rate over the last three years. This shows it failed to generate meaningful demand growth.
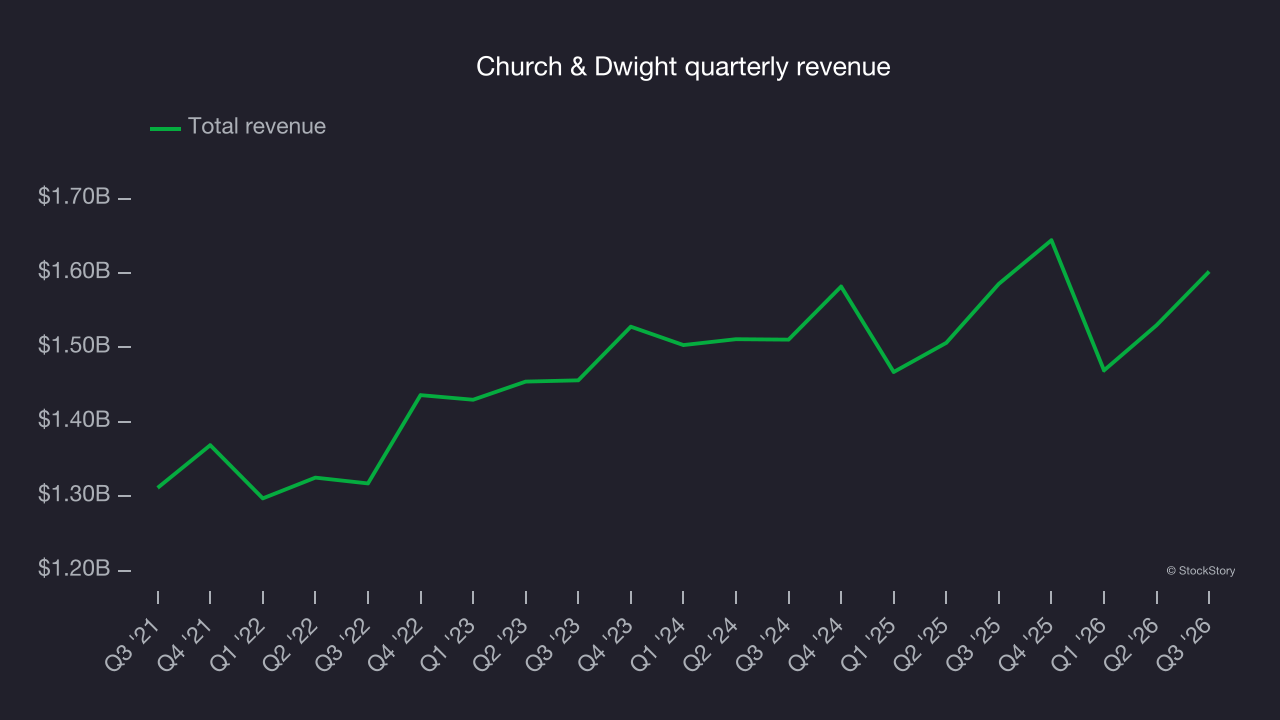
This quarter, Church & Dwight reported modest year-on-year revenue growth of 1% but beat Wall Street’s consensus estimates by 1.6%. Company management is currently guiding for flat revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 3.1% over the next 12 months, according to S&P, similar to its three-year rate. This underwhelming projection suggests its newer products will not lead to better top-line performance yet.
Organic revenue growth
The most important measure of revenue growth is organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions and divestitures as well as foreign currency fluctuations.
The demand for Church & Dwight’s products has generally risen over the last two years but lagged behind the broader sector. On average, the company’s organic revenue has grown by 2.9% year on year. 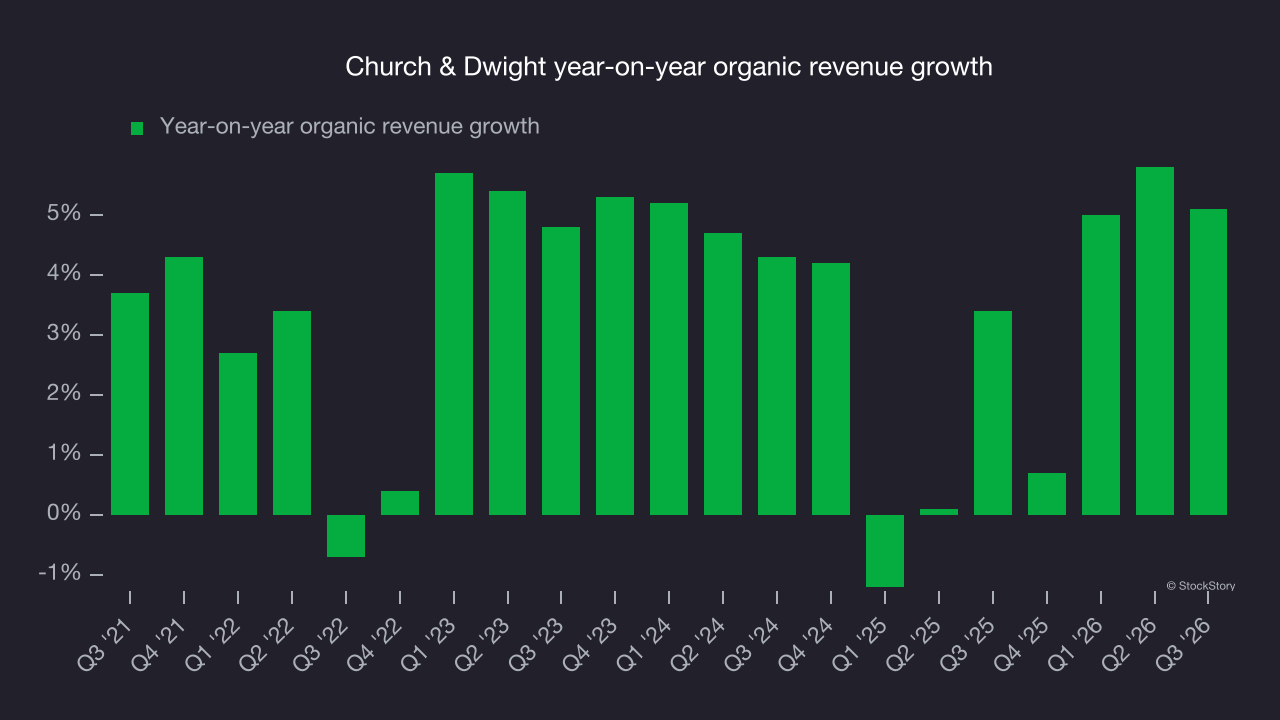
In the latest quarter, Church & Dwight’s organic revenue rose by 5.1% year on year. This marked an acceleration from its historical growth rates, a positive sign.
Key takeaways from Church & Dwight’s Q3 results
Church & Dwight’s organic revenue and total revenue both topped analysts’ consensus estimates, giving the quarter some key positives. However, revenue guidance for next quarter fell slightly short of expectations. Shares rose 3.8% to $110.02 immediately after the results.
To evaluate Church & Dwight as an investment, consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).






