News Corp has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 17.6% to $28.78 per share while the index has gained 16.8%.
Is now the time to buy News Corp, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think News Corp Will Underperform?
We’re cautious about News Corp. Here are three reasons why there are better opportunities than NWSA, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
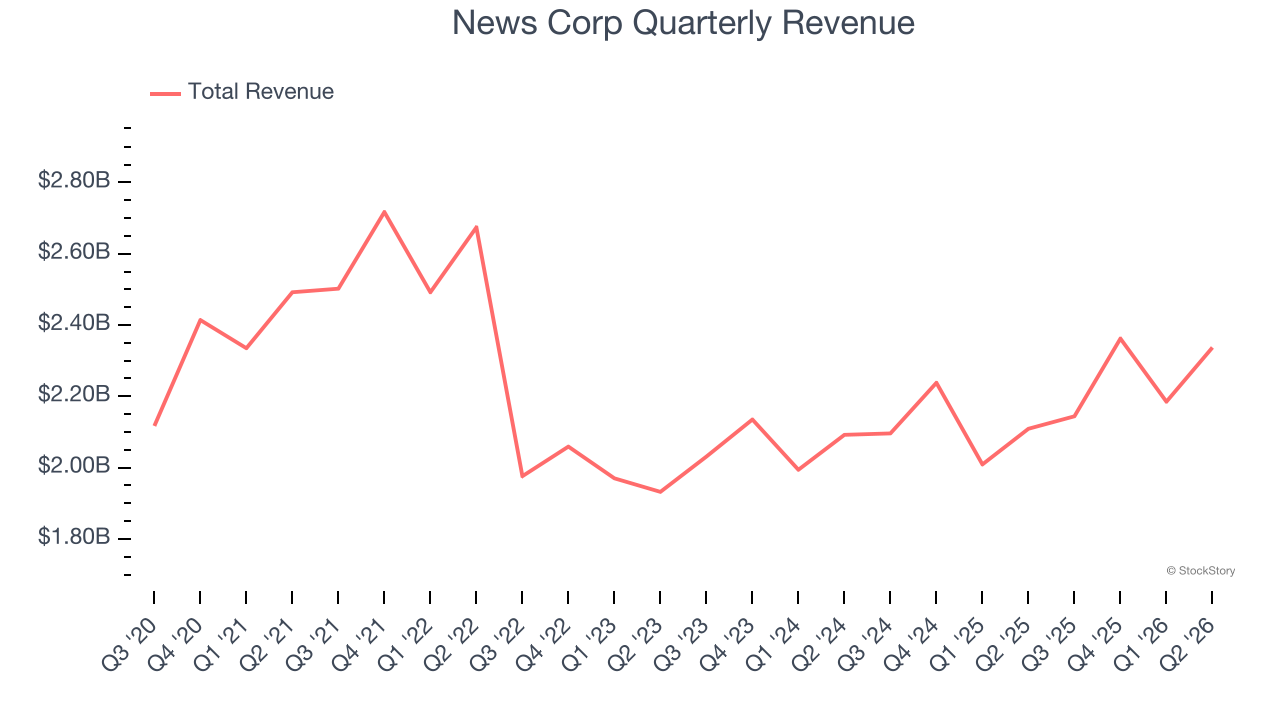
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Unfortunately, News Corp struggled to consistently increase demand as its $9.03 billion of sales for the trailing 12 months was close to its revenue five years ago. This wasn’t a great result and signals it’s a low quality business.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
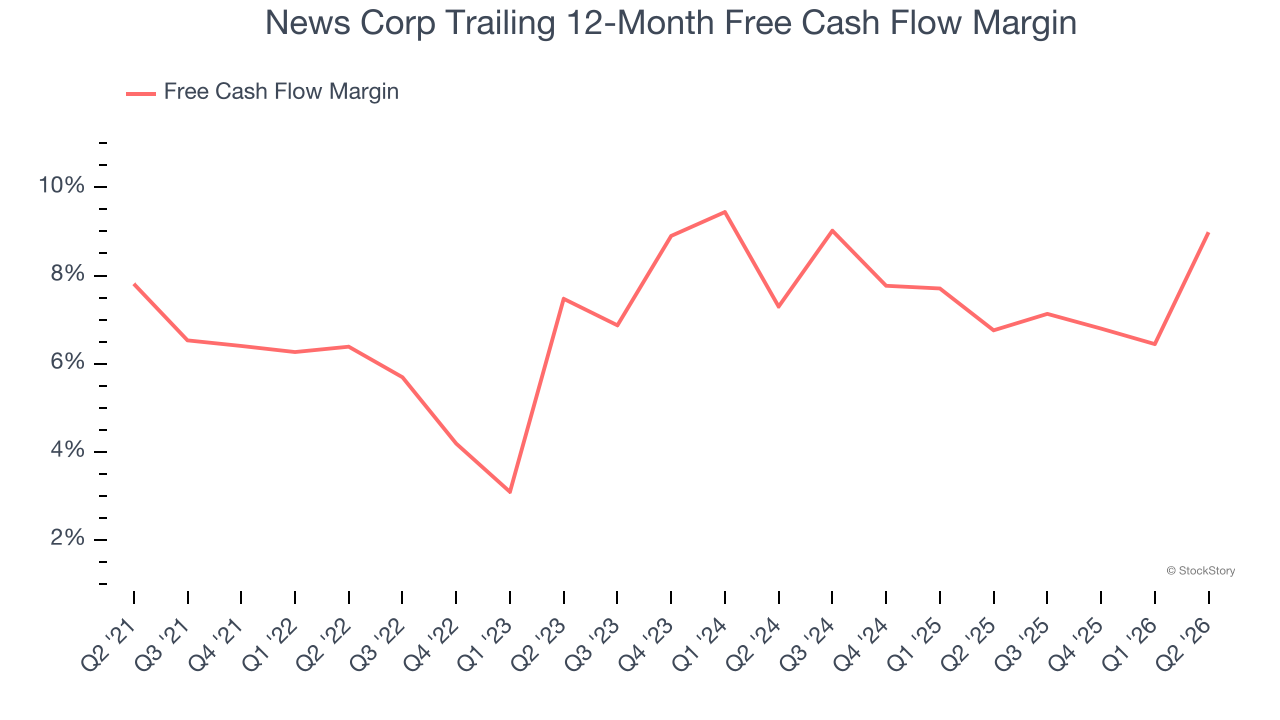
News Corp has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 7.9%, below what we’d expect for a consumer discretionary business.
3. New Investments Aren’t Moving the Needle
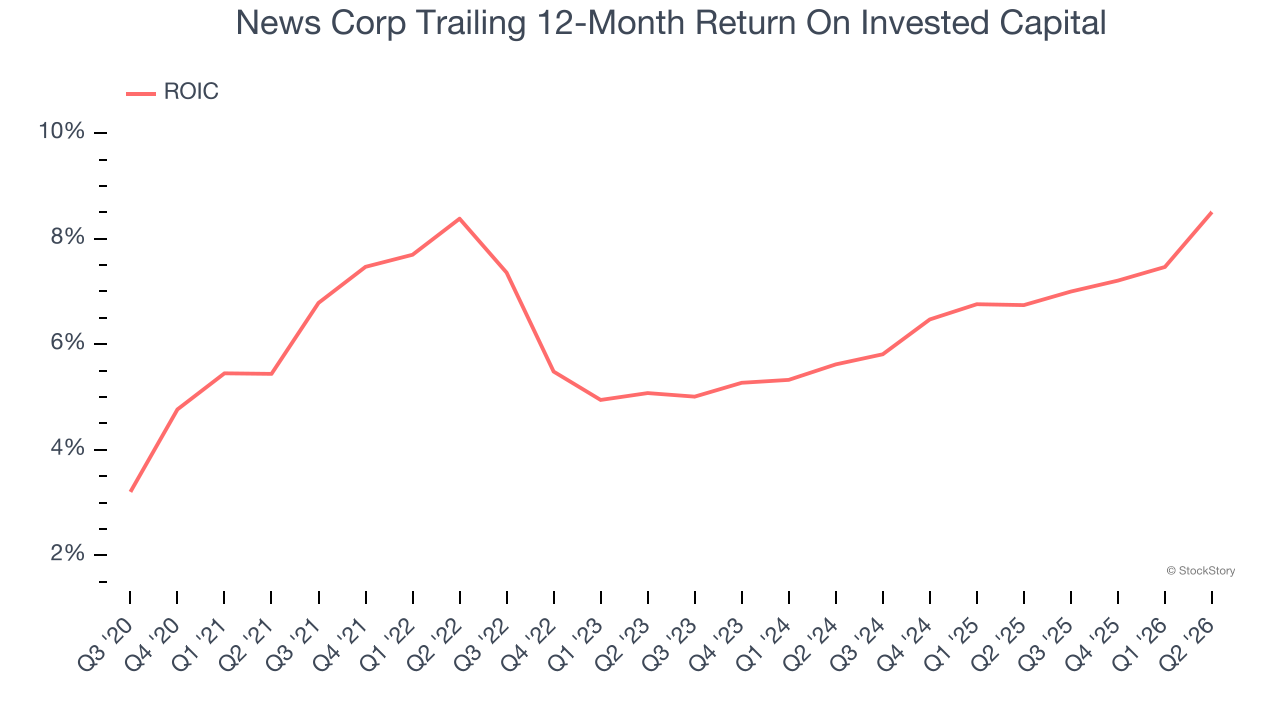
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Unfortunately, News Corp’s ROIC has stayed the same over the last few years. If the company wants to become an investable business, it must improve its returns by generating more profitable growth.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of News Corp, we’ll be cheering from the sidelines. That said, the stock currently trades at 21.5× forward P/E (or $28.78 per share). At this valuation, there’s a lot of good news priced in - we think other companies feature superior fundamentals at the moment. We’d recommend looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Like More Than News Corp
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.