Sport boat manufacturer MasterCraft (NASDAQ: MCFT) reported calendar Q3 2026 (fiscal Q1 2027) results topping the market’s revenue expectations, with revenue up 123% year on year to $154.1 million. Its non-GAAP profit of $0.50 per share was 25% above analysts’ consensus estimates.
For more on MasterCraft, read our full research report for free.
MasterCraft (MCFT) Q3 CY2026 highlights:
- Revenue $154.1 million vs S&P analyst consensus of $147.2 million (123% year-on-year growth, 4.7% beat)
- Adjusted EPS $0.50 vs S&P analyst consensus of $0.40 (25% beat)
- Adjusted EBITDA $20.06 million vs analysts’ consensus estimates of $16.55 million (13% margin, 21.2% beat)
- Operating margin 7.8%, up from 5.5% in the same quarter last year
- Free cash flow $2.91 million, up from -$9.99 million in the same quarter last year
- Market capitalization $499 million
Brad Nelson, Chief Executive Officer, commented, “We delivered results above our expectations in the first quarter of the Transition Period, with total company net sales growing more than 120% year-over-year. Importantly, our legacy business net sales grew 37% and delivered Adjusted EBITDA growth of nearly 140%, reflecting the deliberate product, commercial, and operational actions we have taken across our business to drive premium mix, clean channels, and reduce costs.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. MasterCraft’s demand was weak over the last five years as its revenue fell at a 4.7% annual rate. That decline suggests poor business quality.
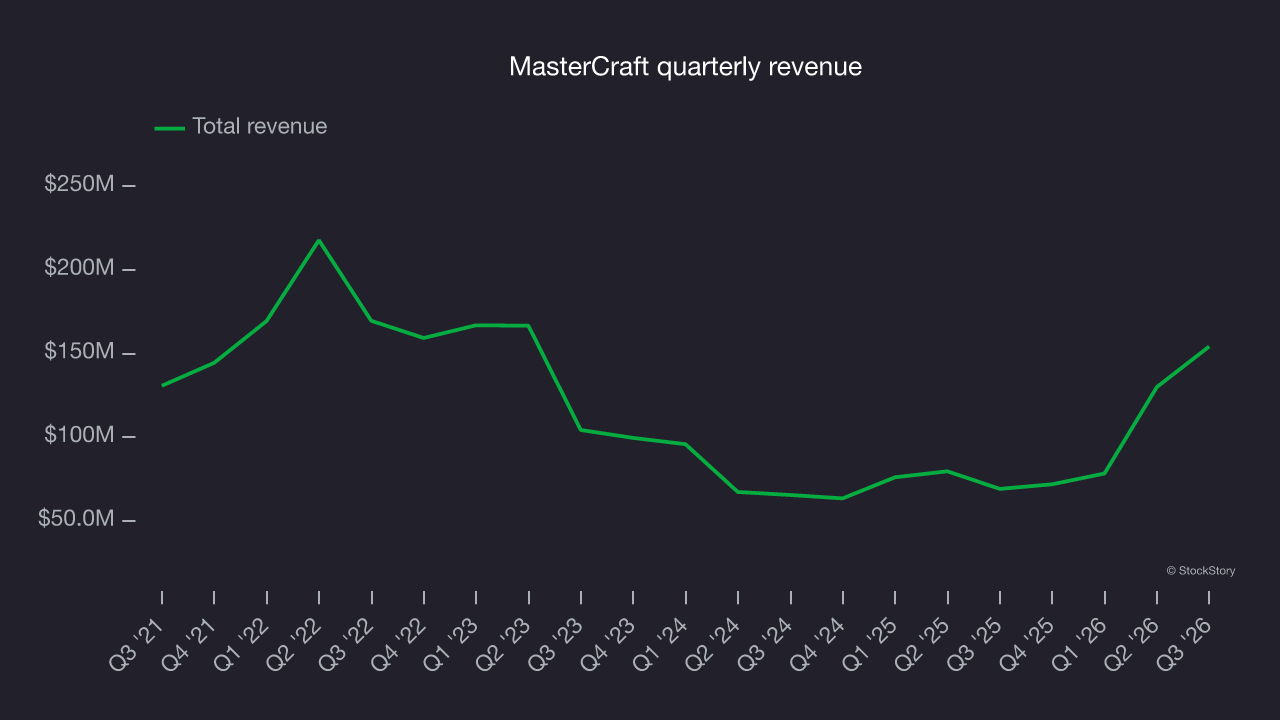
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. MasterCraft’s annualized revenue growth of 15.1% over the last two years is above its five-year trend, which is encouraging. 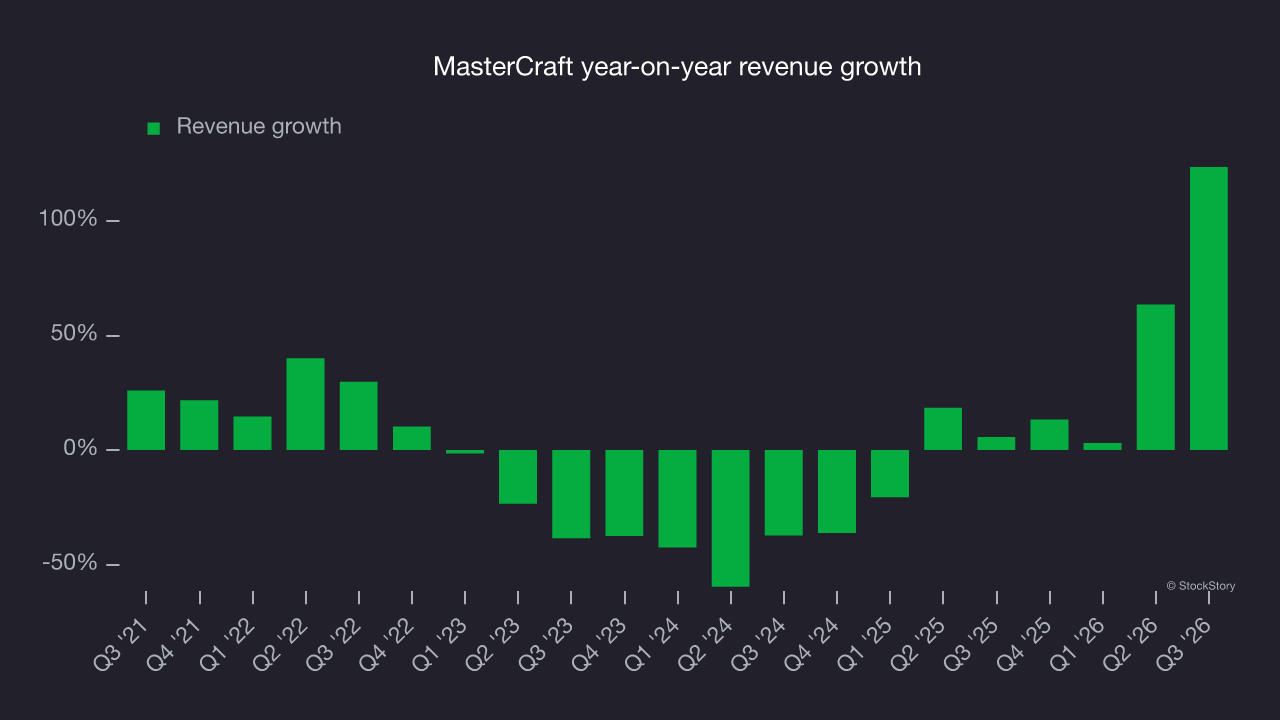
This quarter, MasterCraft reported year-on-year revenue growth of 123%, and its $154.1 million of revenue beat Wall Street’s consensus estimates by 4.7%.
Looking ahead, sell-side analysts expect revenue to grow 42.9% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection implies its newer products and services will drive better revenue performance.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
MasterCraft’s operating margin has been trending down over the last 12 months and averaged 2.9% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
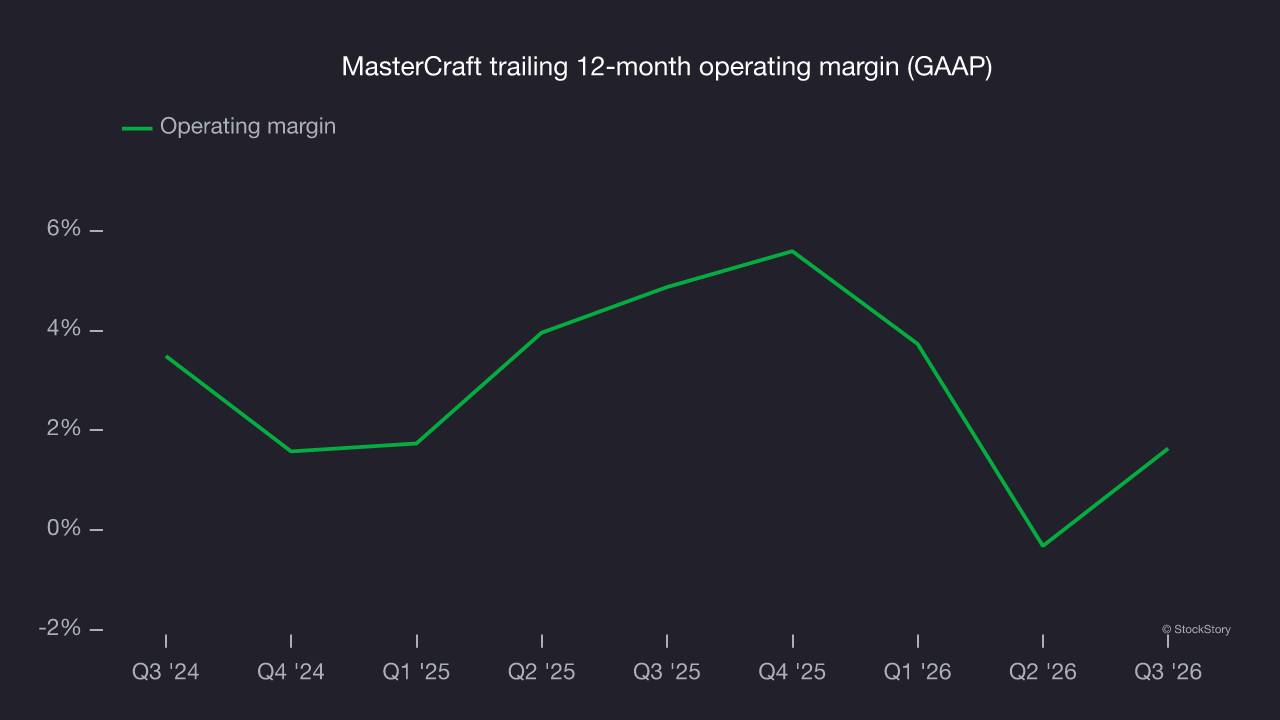
This quarter, MasterCraft generated an operating profit margin of 7.8%, up 2.3 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
MasterCraft’s EPS declined by 10.9% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
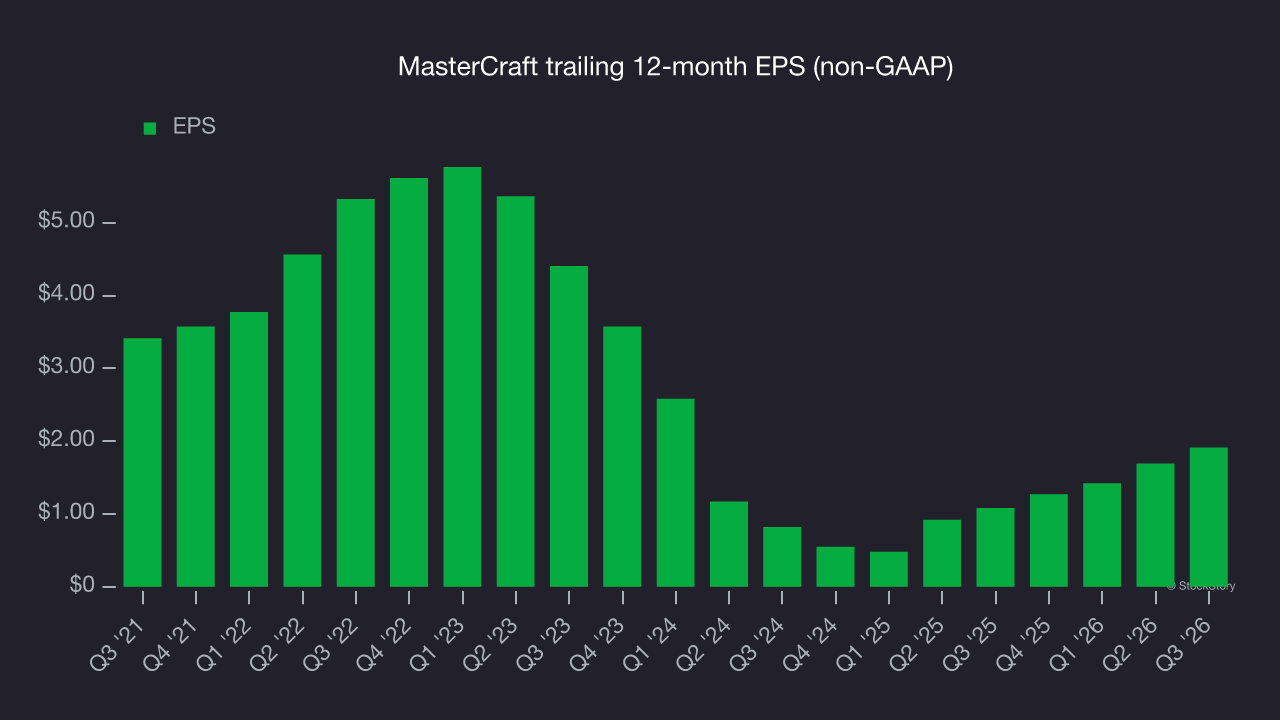
In Q3, MasterCraft reported adjusted EPS of $0.50, up from $0.28 in the same quarter last year. The result beat analysts’ consensus estimates by a wide margin, a positive outcome for shareholders. Over the next 12 months, Wall Street expects MasterCraft’s full-year EPS to grow 4.7% from $1.91 to $2, according to S&P.
Key takeaways from MasterCraft’s Q3 results
Beats on both EBITDA and EPS made this a positive quarter for MasterCraft, with both measures topping analysts’ consensus estimates. Shares rose 4.6% to $21.44 immediately after the results.
MasterCraft had a solid quarter, but assessing whether the stock is a buy requires a broader view. That decision should take into account valuation and business quality as well as the latest earnings. For more on MasterCraft, read the full research report here (it’s free).