Modular home and building manufacturer Champion Homes (NYSE: SKY) reported calendar Q3 2026 (fiscal Q2 2027) results exceeding the market’s revenue expectations, with revenue up 6.2% year on year to $727 million. Its non-GAAP profit of $0.95 per share was in line with analysts’ consensus estimates.
For more on Champion Homes, read our free full research report.
Champion Homes (SKY) Q3 CY2026 highlights:
- Revenue $727 million vs S&P analysts’ consensus estimates of $722.3 million (6.2% year-on-year growth, 0.7% beat)
- Adjusted EPS $0.95 vs S&P analysts’ consensus estimates of $0.94 (in line)
- Adjusted EBITDA $76.59 million vs analysts’ consensus estimates of $75.97 million (10.5% margin, 0.8% beat)
- Operating margin 9%, down from 10.9% in the same quarter last year
- Free cash flow margin 4.3%, down from 9.7% in the same quarter last year
- Sales volumes rose 2.3% year on year (3.4% in the same quarter last year)
- Market capitalization $4.81 billion
“We delivered strong results in our second quarter that were in line with our expectations," said Tim Larson, President and Chief Executive Officer of Champion Homes. "Our team’s focused execution against our strategic priorities enabled us to outperform the housing market in the quarter and build meaningful order momentum. From a product and regulatory perspective, our team flawlessly executed and delivered our two-story home, the New Horizon, to the National Mall for Homes on the Hill in September. This innovative home, which was built to the HUD Code, features a removed second-floor chassis and is designed for vertical construction in narrow urban infill lots offering a unique solution for attainable housing. In addition to delivering new and innovative products, we continue to drive long-term growth across our business, including in our retail channel through the recently announced planned acquisition of Timberline Homes.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Champion Homes’s revenue grew at a decent 7.9% compounded annual growth rate over the last five years. Its growth was slightly above the average industrials company and shows its offerings resonate with customers.
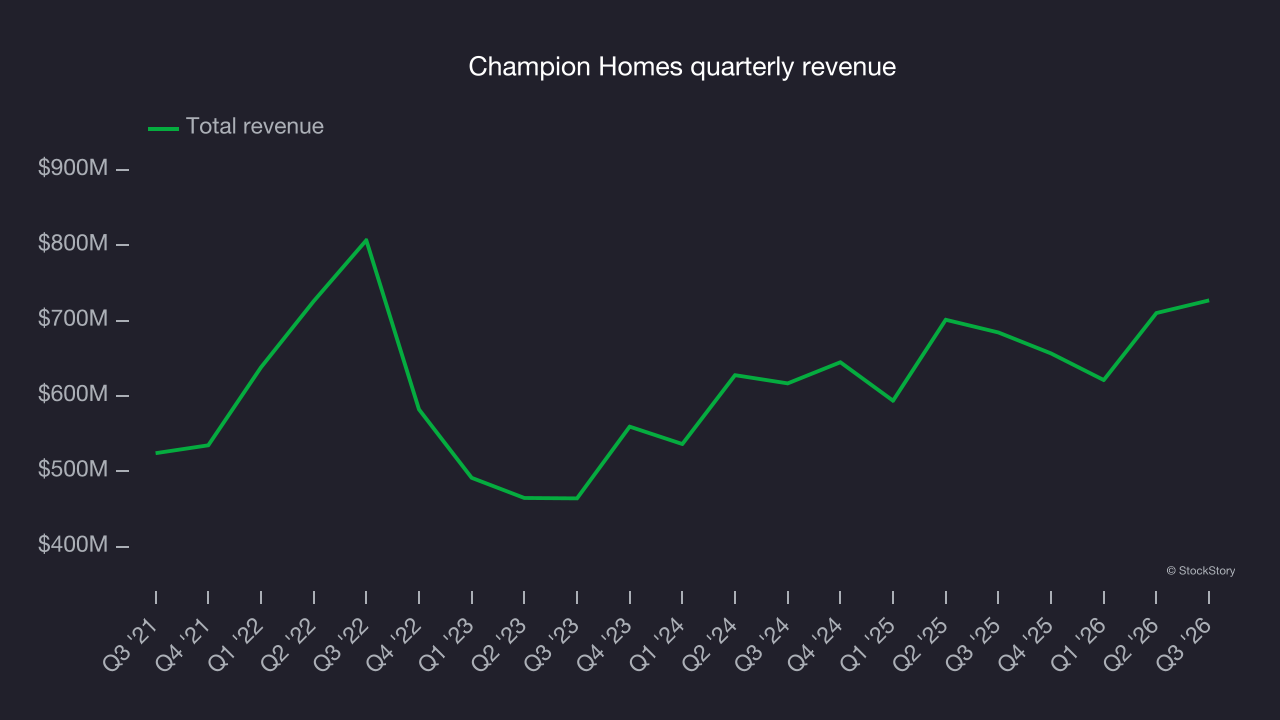
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Champion Homes’s annualized revenue growth of 7.7% over the last two years aligns with its five-year trend, suggesting its demand was stable. Champion Homes’s recent performance also stands out as many other homebuilding businesses have faced declining revenue because of cyclical headwinds. 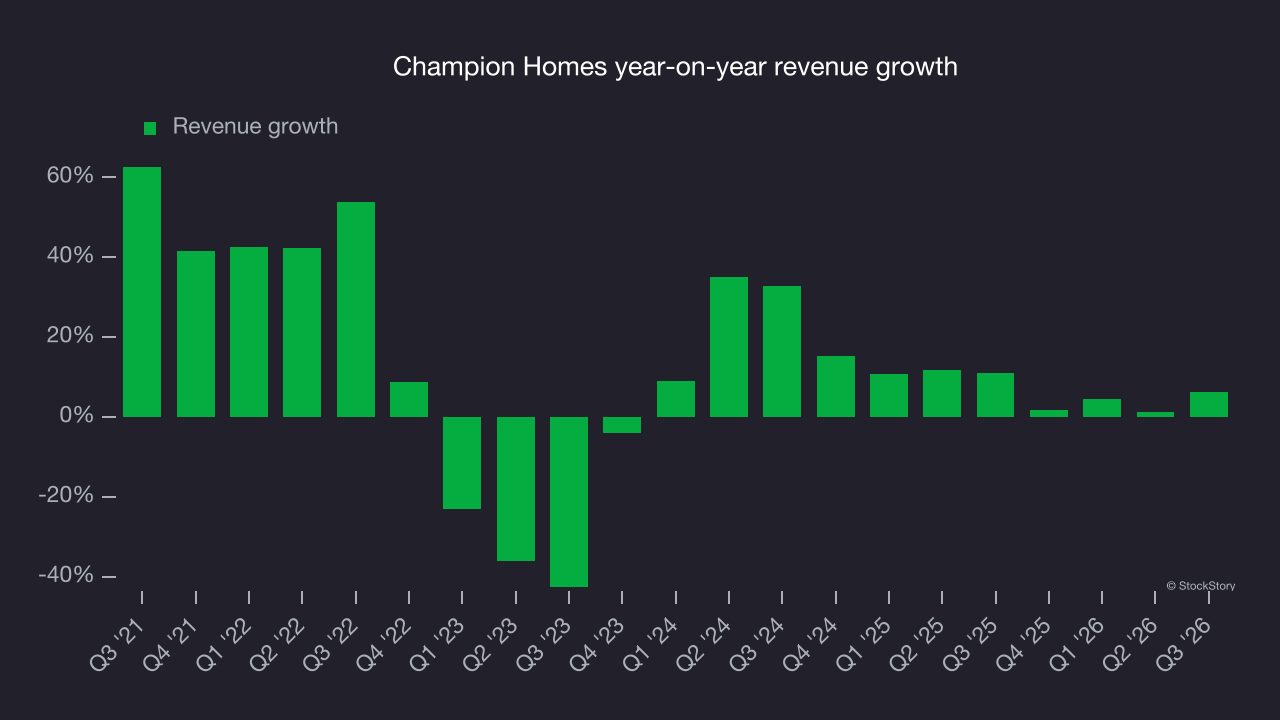
The number of units sold offers a closer look at the company’s revenue dynamics, reaching 6,724 in the latest quarter. Over the last two years, Champion Homes’s units sold averaged 2.3% year-on-year growth. Revenue growth outpaced this metric, indicating that price increases contributed to growth. 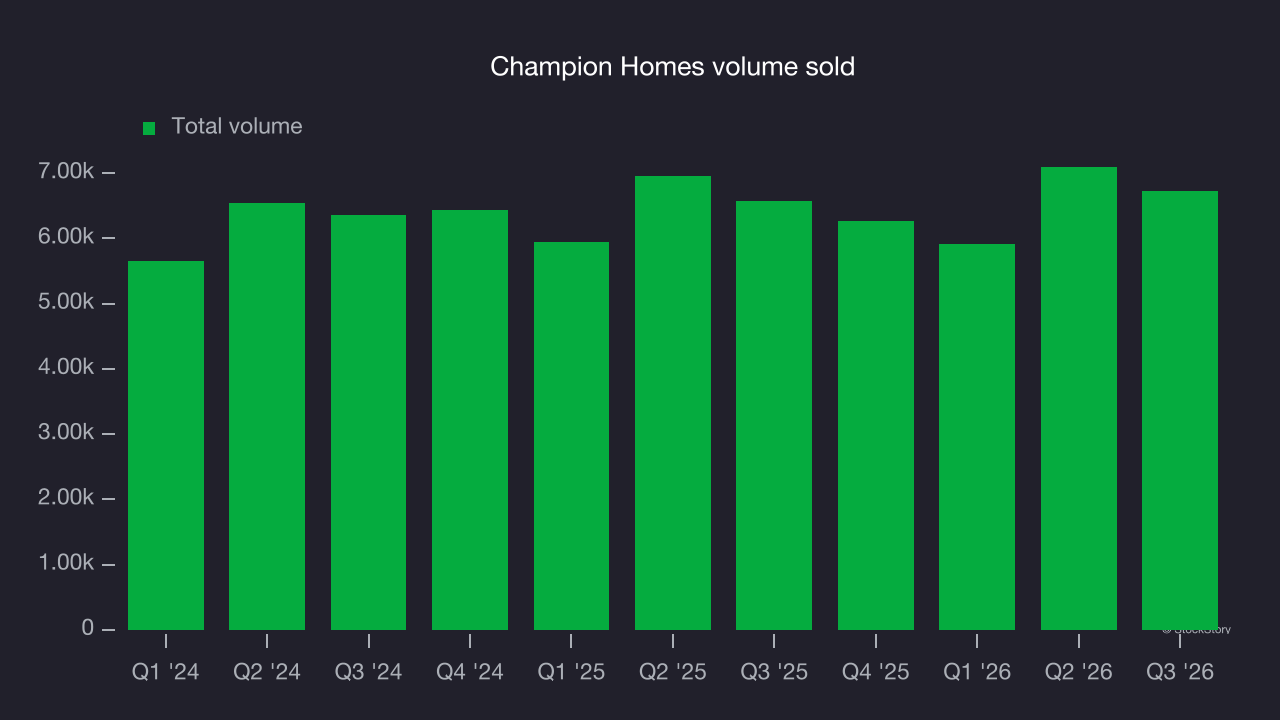
This quarter, Champion Homes reported year-on-year revenue growth of 6.2%, and its $727 million of revenue exceeded Wall Street’s consensus estimates by 0.7%.
Looking ahead, sell-side analysts expect revenue to grow 8.1% over the next 12 months, according to S&P, similar to its two-year rate. This projection is above the sector average and indicates its newer products and services will help sustain its recent top-line performance.
Operating margin
Champion Homes has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 12.2%. This result was particularly impressive given its low gross margin, which largely reflects what it sells and requires significant shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Champion Homes’s operating margin decreased by 12.2 percentage points over the last five years. Many home builders also saw their margins fall (along with revenue, as mentioned above) as the cycle weakened. Champion Homes could emerge as a stronger company, as a downturn offers opportunities to gain market share and improve efficiency.
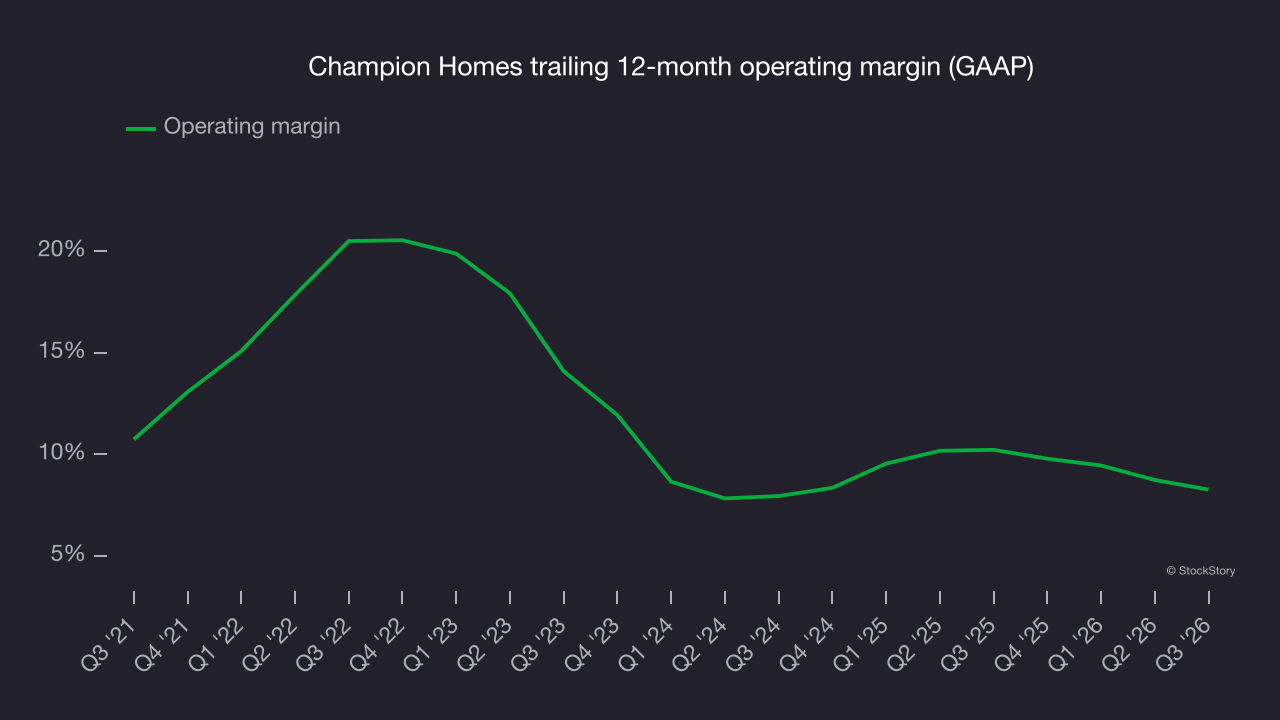
This quarter, Champion Homes generated an operating margin of 9%, down 1.9 percentage points year on year. Its gross margin decreased more than its operating margin, suggesting its recent inefficiencies were driven more by weaker leverage on its cost of sales than by increased marketing, research and development or administrative overhead expenses.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Champion Homes’s EPS grew at an unimpressive 5.7% compounded annual growth rate over the last five years, lower than its 7.9% annualized revenue growth. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
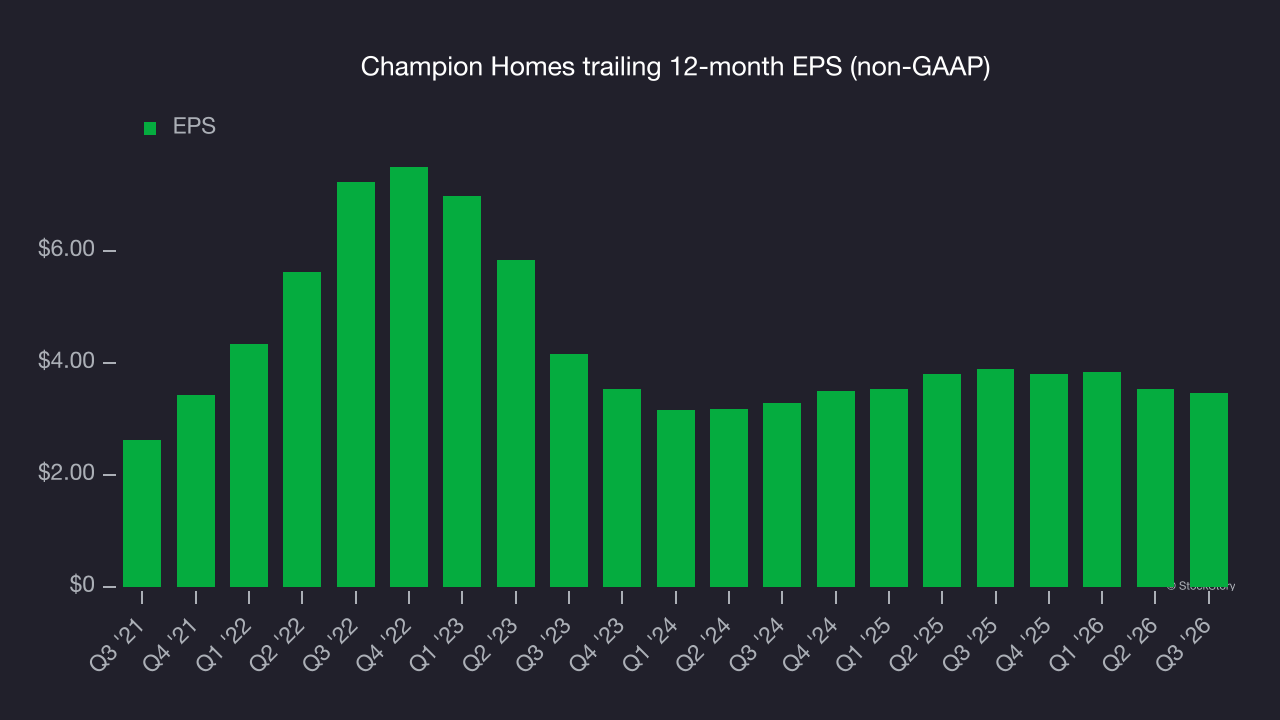
A closer look at Champion Homes’s earnings helps explain its performance. As noted earlier, Champion Homes’s operating margin declined by 12.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Champion Homes, its two-year annual EPS growth of 2.9% was lower than its five-year trend.
In Q3, Champion Homes reported adjusted EPS of $0.95, down from $1.01 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects Champion Homes’s full-year EPS to grow 9.6% from $3.47 to $3.80, according to S&P.
Key takeaways from Champion Homes’s Q3 results
Champion Homes delivered a quarter with some key positives, as revenue and EBITDA both narrowly beat consensus estimates. Shares remained flat at $86.36 immediately after the results.
Champion Homes’ latest quarter is only one part of its longer-term business quality. Business quality, combined with valuation, can help determine whether the stock is a buy. Read our full research report here for more on Champion Homes (it’s free).