Health and wellness products company USANA Health Sciences (NYSE: USNA) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 3.6% year on year to $205.9 million. The company’s full-year revenue guidance of $900 million at the midpoint came in 1% below analysts’ consensus estimates. Its non-GAAP loss of $0.11 per share was significantly below analysts’ consensus estimates.
For more on USANA, read our free full research report.
USANA (USNA) Q3 2026 highlights:
- Revenue $205.9 million vs S&P analysts’ consensus estimates of $217.4 million (3.6% year-on-year decline, 5.3% miss)
- Adjusted EPS -$0.11 vs S&P analysts’ consensus estimates of $0.11 (significant miss)
- Adjusted EBITDA $12.05 million vs analysts’ consensus estimates of $12.83 million (5.9% margin, 6.1% miss)
- Revenue guidance The company dropped its revenue guidance for the full year to $900 million at the midpoint from $962.5 million, a 6.5% decrease
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $0.55 at the midpoint, a 74.1% decrease
- EBITDA guidance $77 million at the midpoint for the full year, below analysts’ consensus estimates of $85.08 million
- Operating margin -0.7%, down from 0.6% in the same quarter last year
- Free cash flow $8.44 million, up from -$5.16 million in the same quarter last year
- Market capitalization $272 million
“As we continue our transformation to an omnichannel health and wellness company, our third quarter results were mixed, with meaningful improvement in some areas and results that fell short of our expectations in others,” said Kevin Guest, Chairman and Chief Executive Officer. “We are investing across each of our businesses to strengthen their long-term competitive position and made clear progress in key areas. At Hiya, as customer acquisition began responding positively during the quarter, we increased marketing spend to build on that traction, which pressured margins but generated an 18% sequential increase in active subscribers and returned the segment to year-over-year net sales growth. Additionally, our Core Nutritional business expanded its operating margin from a year ago on a leaner cost structure despite lower net sales. While we have more work to do in growing Core Nutritional active customers and net sales at Rise Wellness, we believe we have the right strategies in place.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years.
With $905.6 million in revenue over the past 12 months, USANA is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
USANA struggled to increase demand as its $905.6 million in revenue for the trailing 12 months was close to its revenue three years ago. This shows demand was soft.
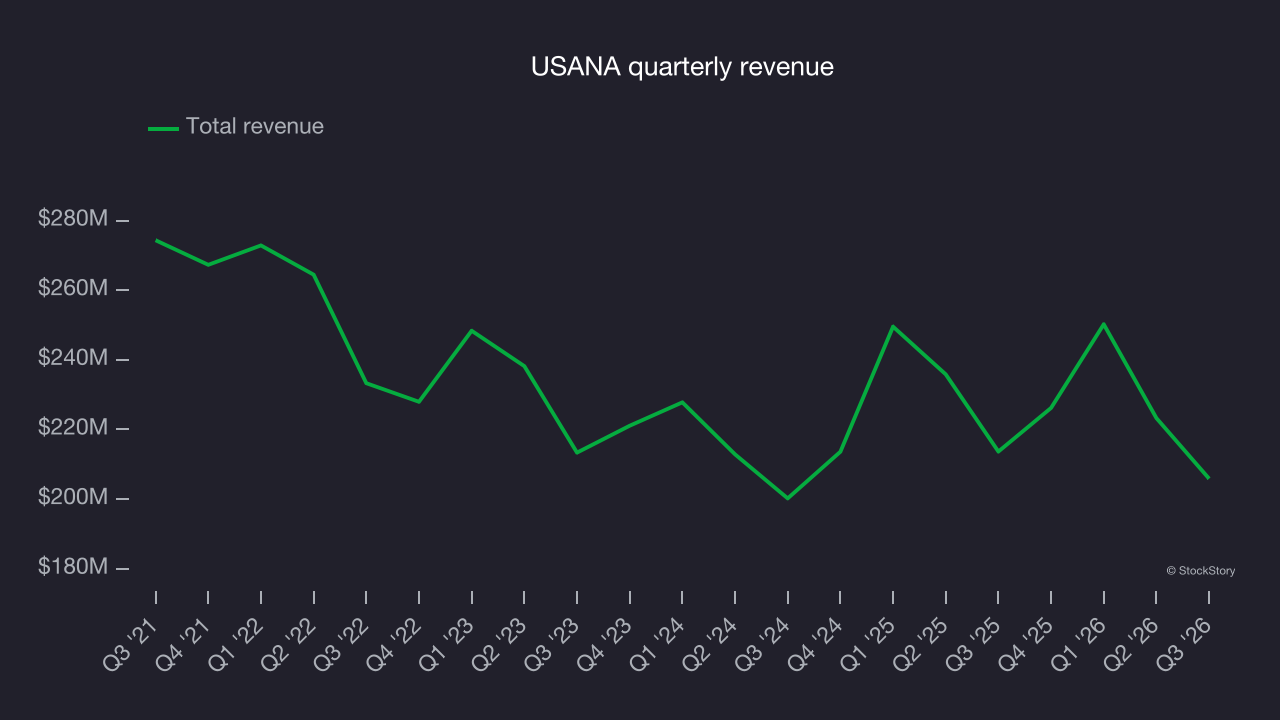
This quarter, USANA missed Wall Street’s consensus estimates and reported an uninspiring 3.6% year-on-year revenue decline, generating $205.9 million in revenue.
Looking ahead, sell-side analysts expect revenue to grow 3.2% over the next 12 months, according to S&P. Although this projection indicates its newer products will fuel better top-line performance, it is still below average for the sector.
Free cash flow
Free cash flow matters because accounting profits alone can’t pay the bills.
USANA has shown weak cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.7%, below expectations for a consumer staples business.
On the positive side, USANA’s margin expanded by 1.2 percentage points over the last year. The improvement shows it is heading in the right direction, and the rise in free cash flow profitability despite falling operating profitability indicates the business became less capital-intensive.
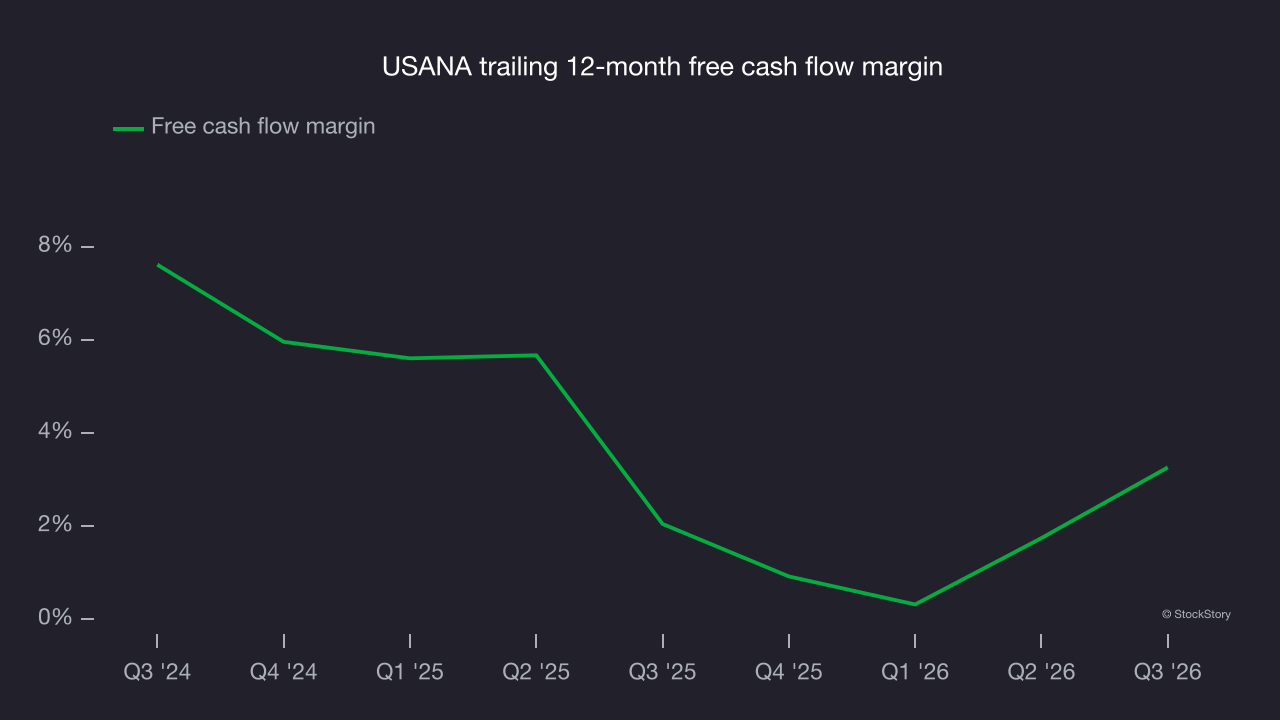
USANA’s free cash flow totaled $8.44 million in Q3, equivalent to a 4.1% margin. Its cash flow turned positive after being negative in the same quarter last year, building on its favorable historical trend.
Key takeaways from USANA’s Q3 results
USANA’s revenue and EBITDA both fell short of Wall Street’s consensus estimates, leaving few positives in a disappointing quarter. Shares plunged 14.9% to $12.65 immediately after the report.
USANA’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so a closer look can help assess whether the stock is a buy at the current price. The latest quarter is only one part of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. For more on business quality and valuation, read our full research report here (it’s free).