IT solutions integrator Insight Enterprises (NASDAQ: NSIT) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 21.8% year on year to $2.44 billion. Its non-GAAP profit of $3.59 per share was 25.9% above analysts’ consensus estimates.
For more on Insight Enterprises, read our free full research report.
Insight Enterprises (NSIT) Q3 2026 highlights:
- Revenue $2.44 billion vs S&P analysts’ consensus estimates of $2.14 billion (21.8% year-on-year growth, 13.9% beat)
- Adjusted EPS $3.59 vs S&P analysts’ consensus estimates of $2.85 (25.9% beat)
- Adjusted EBITDA $177.4 million vs analysts’ consensus estimates of $146.4 million (7.3% margin, 21.1% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $13.65 at the midpoint, a 9.6% increase
- Operating margin 2.8%, down from 4.6% in the same quarter last year
- Free cash flow margin 5%, down from 12.2% in the same quarter last year
- Market capitalization $5.15 billion
“We delivered another strong quarter, with broad-based momentum across our business. Gross profit increased 20%, adjusted earnings from operations grew 23%, and adjusted diluted earnings per share increased 34%,” stated Jack Azagury, President and Chief Executive Officer. “We continue to see strong performance in our strategic growth priorities, with infrastructure hardware gross profit increasing more than 50% and more than 20% gross profit growth across Cloud and Insight Core Services,” Azagury added.
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $9.02 billion in revenue over the past 12 months, Insight Enterprises is one of the larger companies in the business services industry and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s harder to find incremental growth when you’ve penetrated most of the market. For Insight Enterprises to boost its revenue, it likely needs to adjust its prices, launch new offerings or expand in foreign markets.
Insight Enterprises struggled to increase demand as its $9.02 billion in revenue for the trailing 12 months was close to its revenue five years ago. This shows demand was soft.
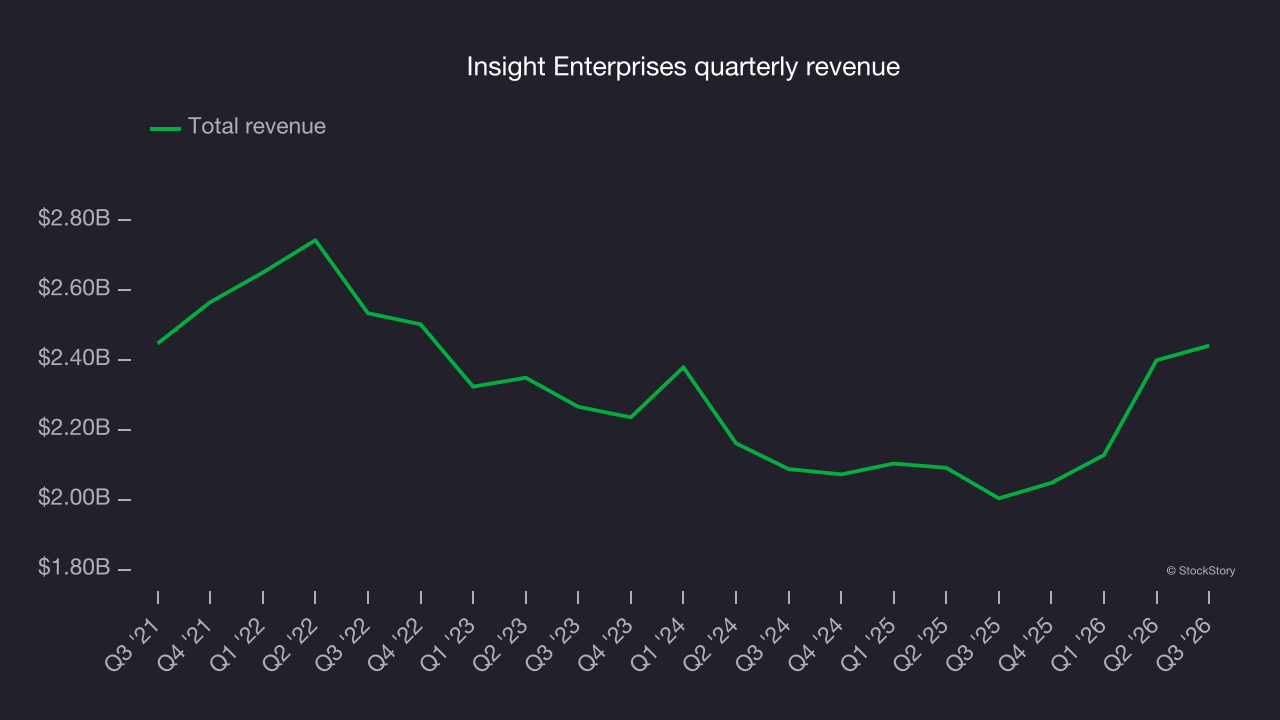
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Just like its five-year trend, Insight Enterprises’s revenue over the last two years was flat, suggesting it is in a slump. 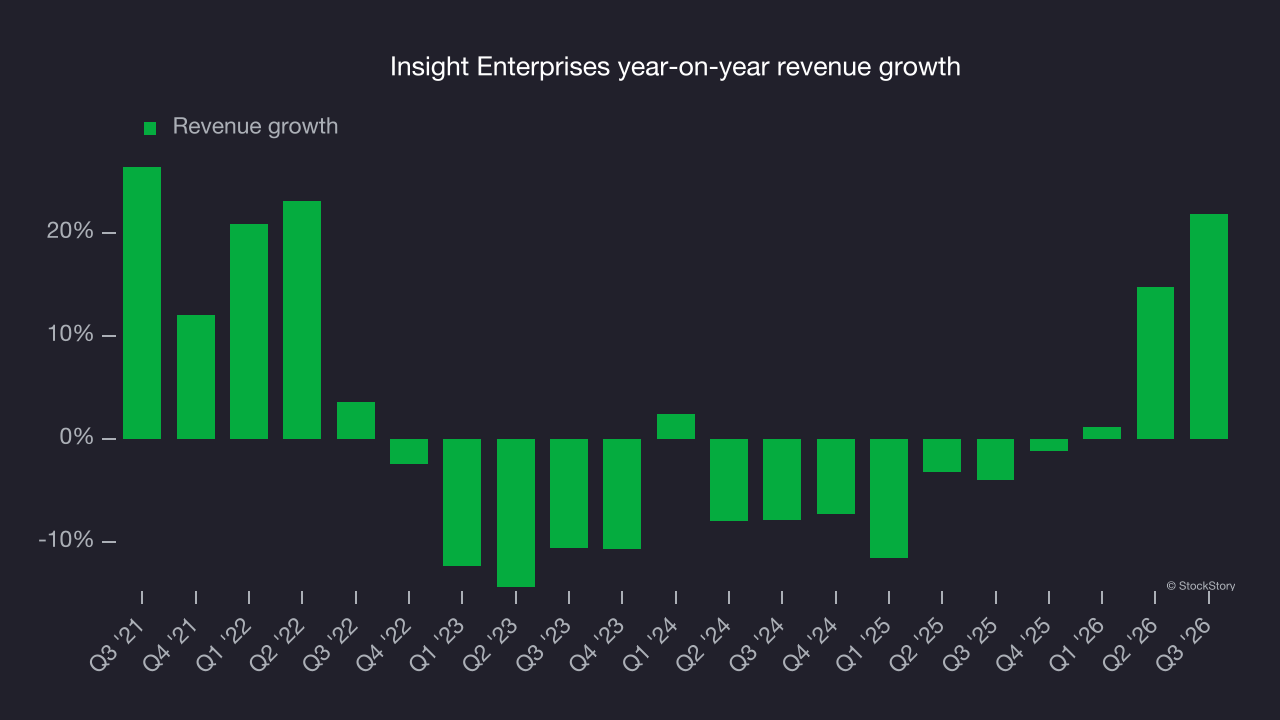
This quarter, Insight Enterprises reported strong year-on-year revenue growth of 21.8%, and its $2.44 billion in revenue topped Wall Street’s consensus estimates by 13.9%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. This underwhelming projection indicates its products and services will face some demand challenges.
Adjusted operating margin
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes and interest on debt – items less connected to business fundamentals.
Insight Enterprises was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 5.4% was weak for a business services company.
On the positive side, Insight Enterprises’s adjusted operating margin rose by 1.7 percentage points over the last five years.
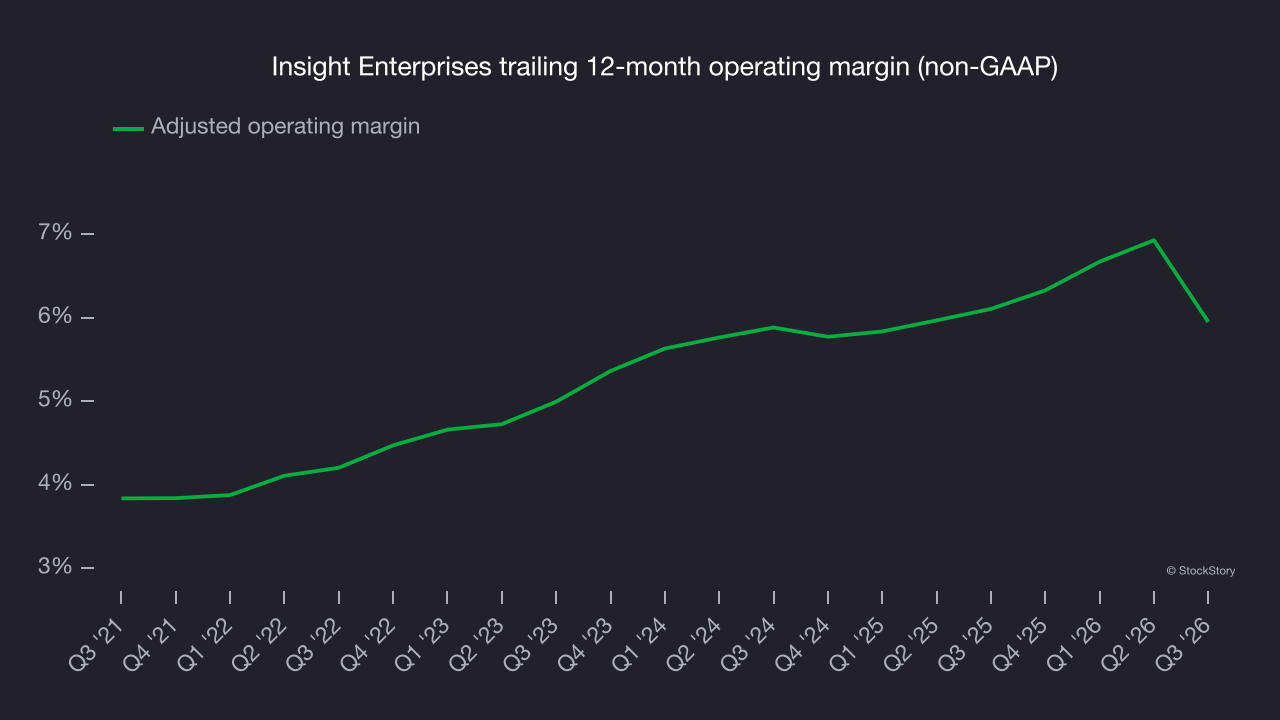
In Q3, Insight Enterprises generated an adjusted operating margin of 2.8%, down 3.5 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Insight Enterprises’s EPS grew at a 14.2% compounded annual growth rate over the last five years, outpacing its flat revenue. This indicates management responded to softer demand by adapting its cost structure.
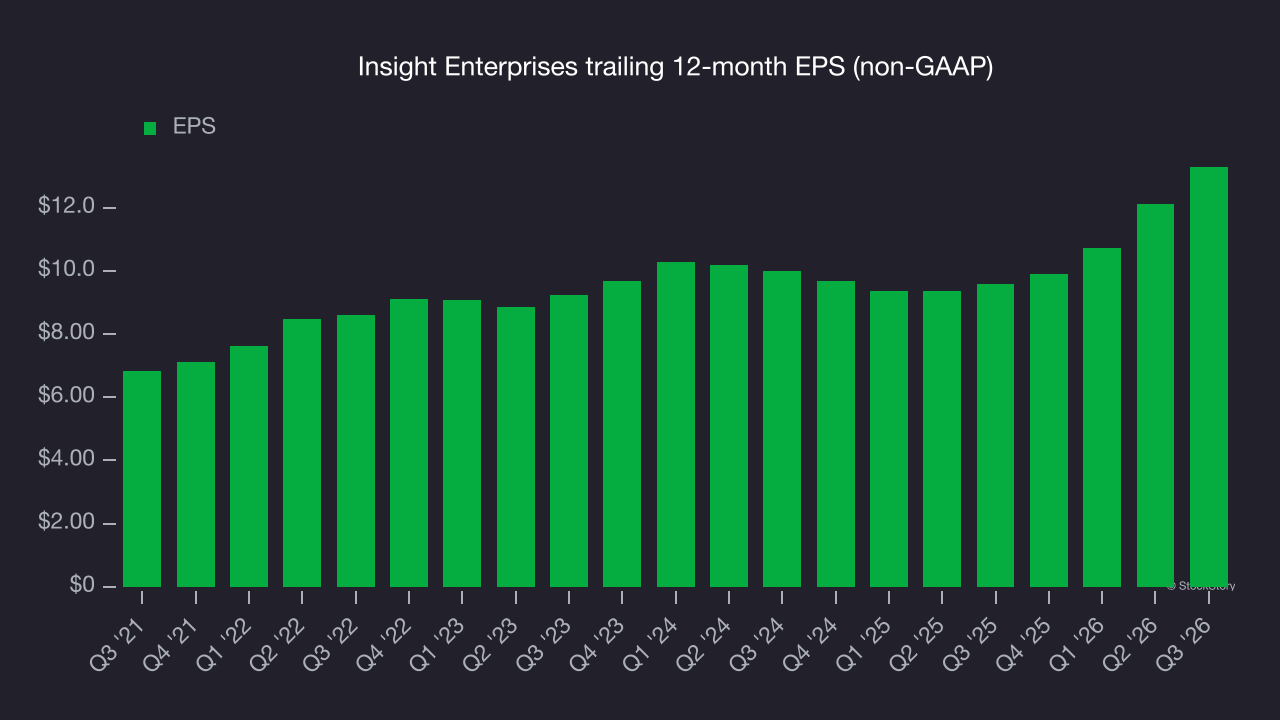
Examining Insight Enterprises’s quality of earnings can give us a better understanding of its performance. As we mentioned earlier, Insight Enterprises’s adjusted operating margin declined this quarter but expanded by 1.7 percentage points over the last five years. Its share count also shrank by 18.8%, and these factors together are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 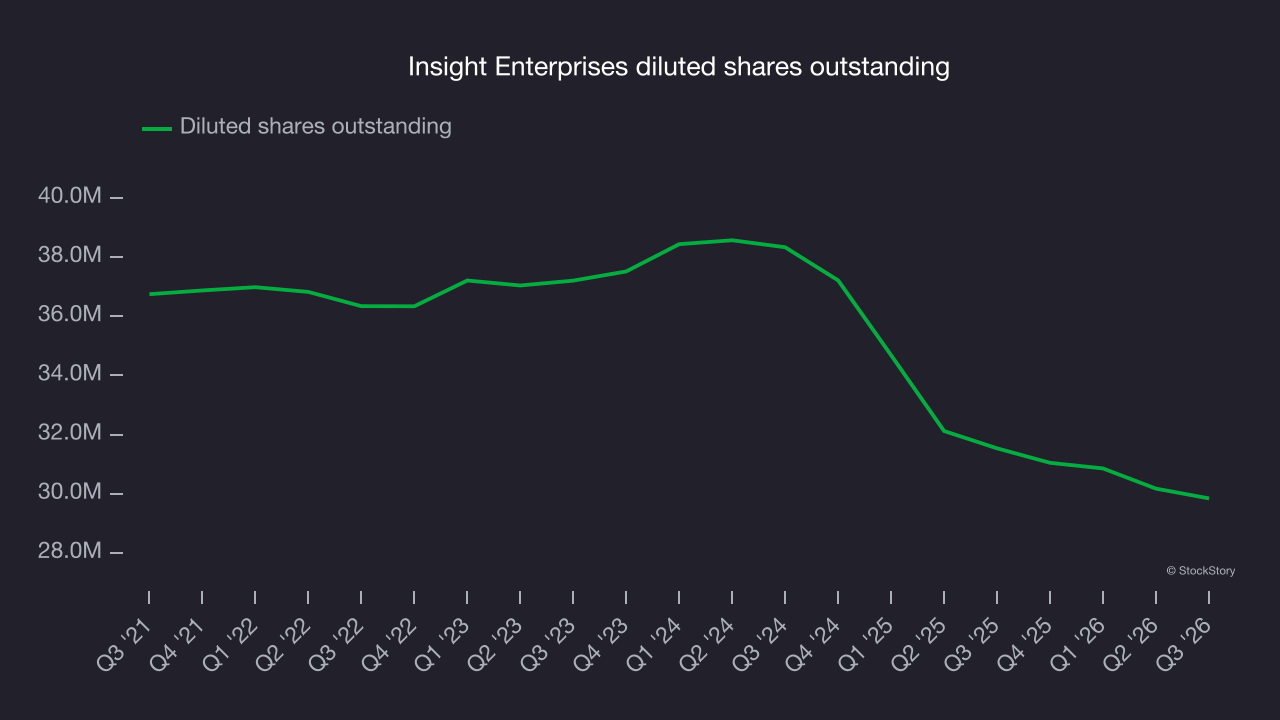
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Insight Enterprises, its two-year annual EPS growth of 15.3% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Insight Enterprises reported adjusted EPS of $3.59, up from $2.43 in the same quarter last year. EPS came in well above analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Insight Enterprises’s full-year EPS to shrink by 2.6% from $13.29 to $12.94, according to S&P.
Key takeaways from Insight Enterprises’s Q3 results
Insight Enterprises delivered a strong Q3, with revenue beating Wall Street’s consensus estimates by a wide margin and EPS also topping analysts’ consensus expectations. Shares rose 2.4% to $179.75 immediately after the report.
Insight Enterprises had a solid quarterly earnings result, but that alone does not determine whether the stock is a good investment. That decision requires considering its valuation, business quality and latest quarterly results. For more on Insight Enterprises, read our full research report here (it’s free).