AdaptHealth has gotten torched over the last six months - since March 2026, its stock price has dropped 44.1% to $5.82 per share. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is there a buying opportunity in AdaptHealth, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think AdaptHealth Will Underperform?
Even though the stock has become cheaper, we don’t have much confidence in AdaptHealth. Here are three reasons you should be careful with AHCO, plus one stock we’d rather own.
1. Revenue Tumbling Downwards
Long-term growth is the most important, but within healthcare, a stretched historical view may miss new innovations or demand cycles. AdaptHealth’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 2.7% over the last two years. 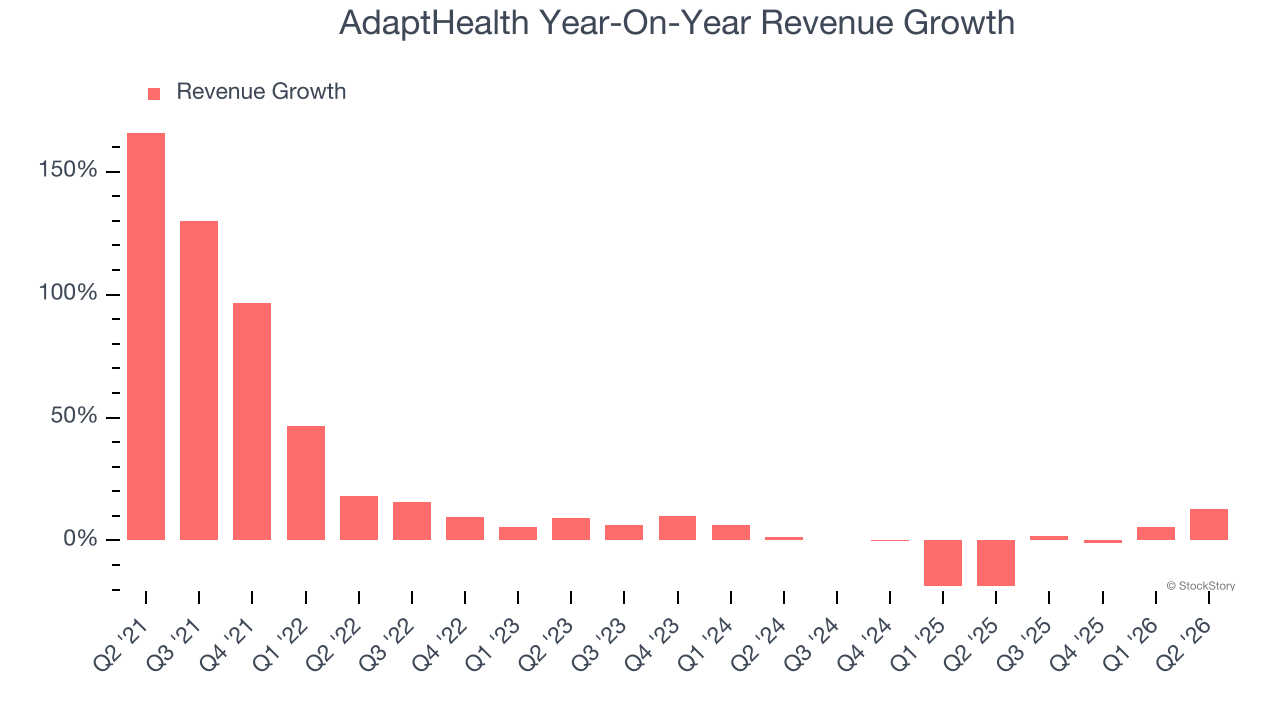
2. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
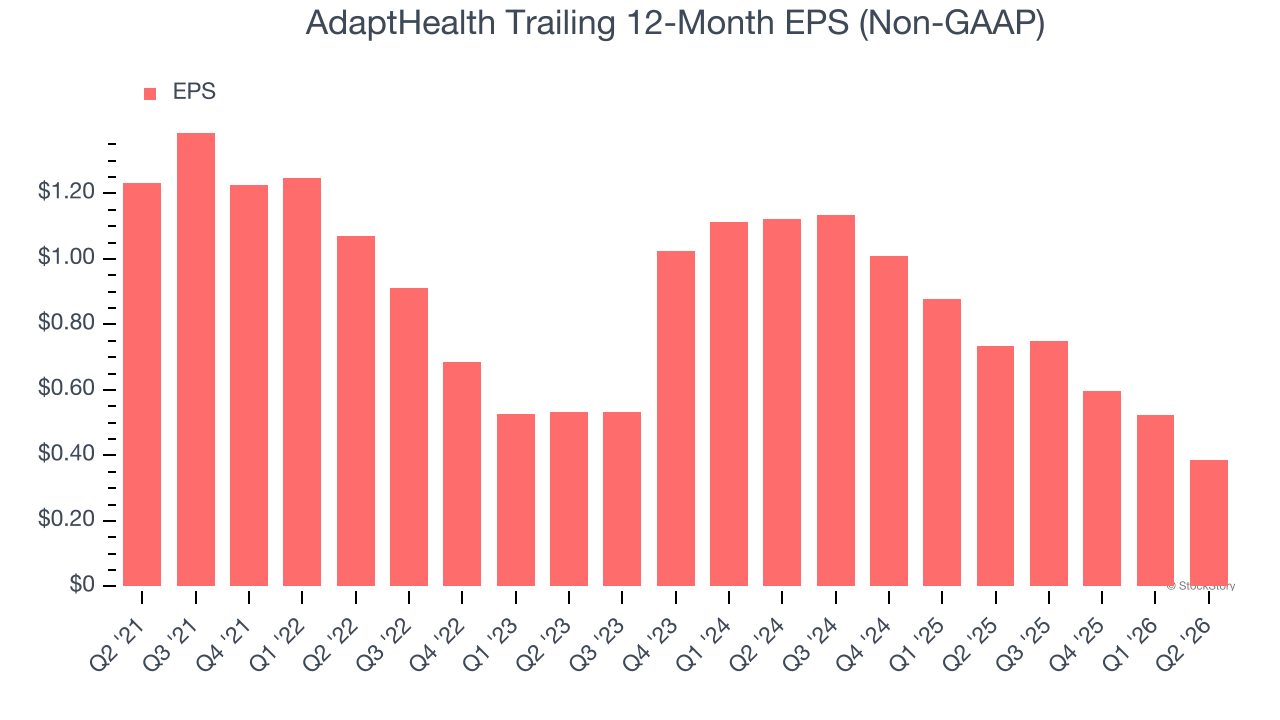
Sadly for AdaptHealth, its EPS declined by 20.7% annually over the last five years while its revenue grew by 12.1%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Previous Growth Initiatives Haven’t Paid Off Yet
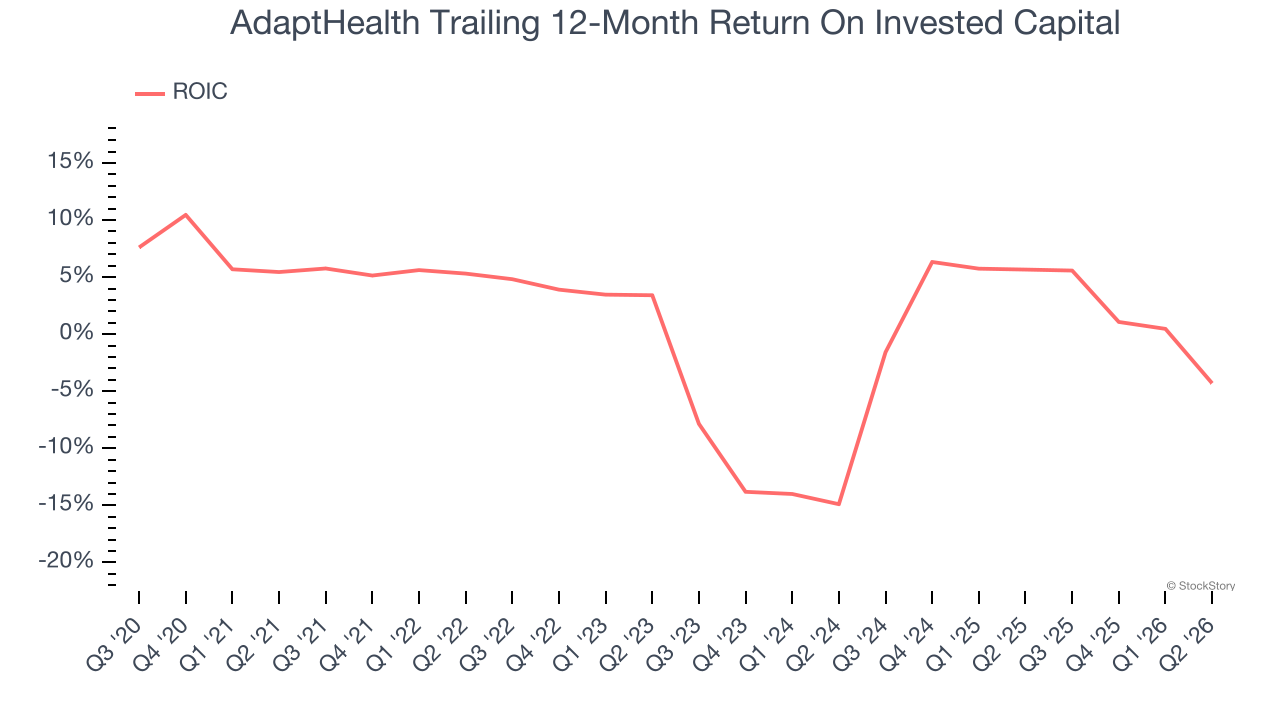
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
AdaptHealth’s five-year average ROIC was negative 1%, meaning management lost money while trying to expand the business. Investors are likely hoping for a change soon.
Final Judgment
We cheer for all companies helping people live better, but in the case of AdaptHealth, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 5.4× forward EV-to-EBITDA (or $5.82 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are superior stocks to buy right now. Let us point you toward one of our all-time favorite software stocks.
Stocks We Would Buy Instead of AdaptHealth
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.