QuinStreet has been on fire lately. In the past six months alone, the company’s stock price has rocketed 53.9%, reaching $18.37 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Following the strength, is QNST a buy right now? Or is the market overestimating its value? Find out in our full research report, it’s free.
Why Are We Positive on QNST?
Founded during the dot-com era in 1999 and specializing in high-intent consumer traffic, QuinStreet (NASDAQ: QNST) operates digital performance marketplaces that connect clients in financial and home services with consumers actively searching for their products.
1. Skyrocketing Revenue Shows Strong Momentum
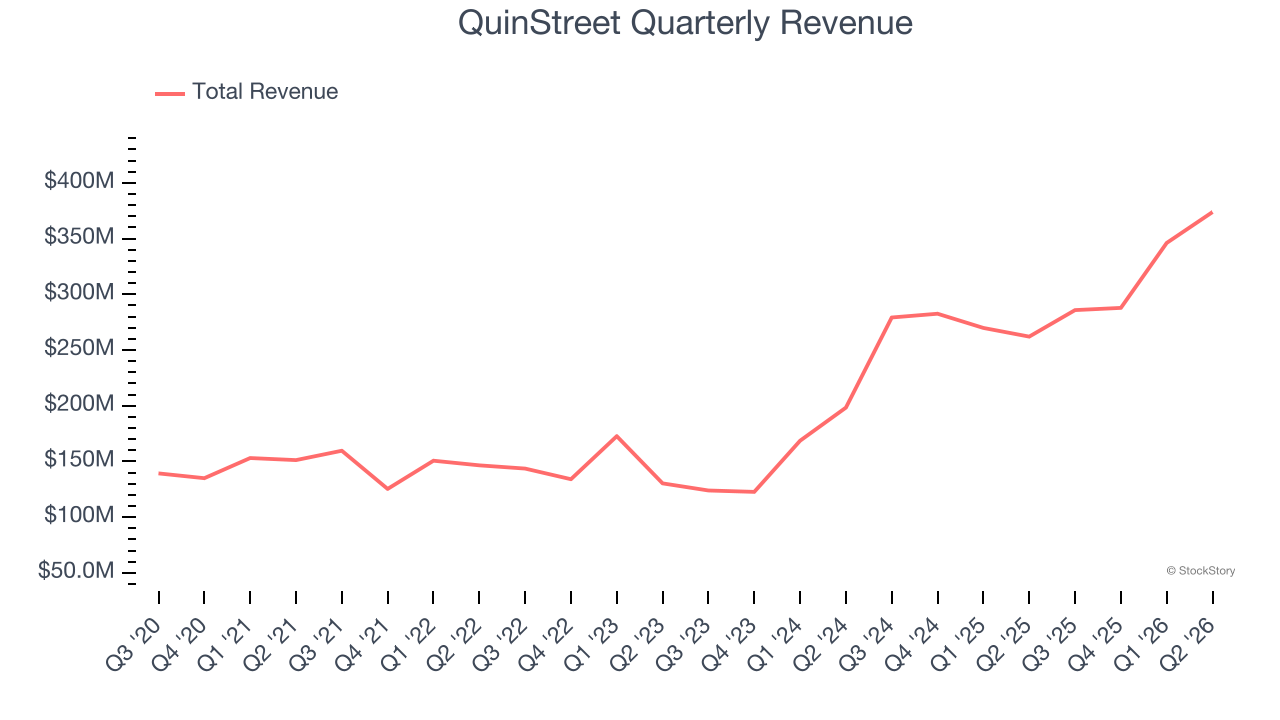
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Luckily, QuinStreet’s sales grew at an incredible 17.5% compounded annual growth rate over the last five years. Its growth beat the average business services company and shows its offerings resonate with customers.
2. Increasing Free Cash Flow Margin Juices Financials
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
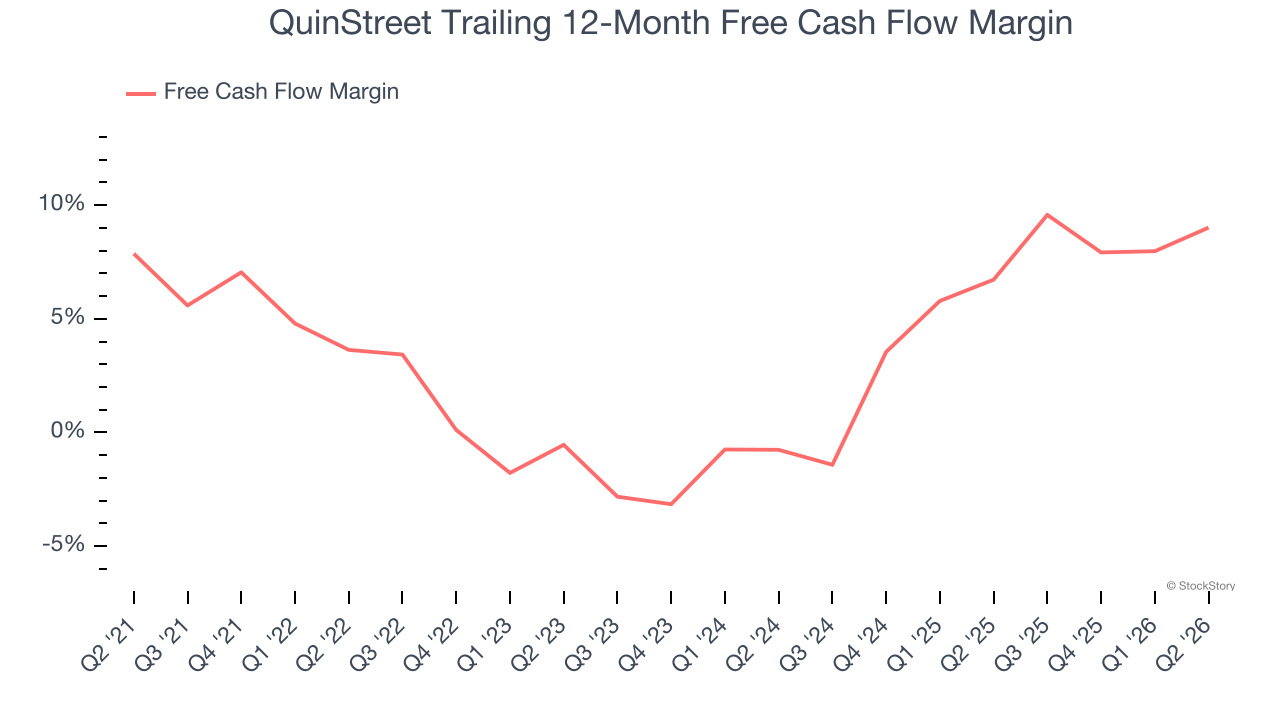
As you can see below, QuinStreet’s margin expanded by 5.4 percentage points over the last five years. The company’s improvement shows it’s heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. QuinStreet’s free cash flow margin for the trailing 12 months was 9%.
3. New Investments Bear Fruit as ROIC Jumps
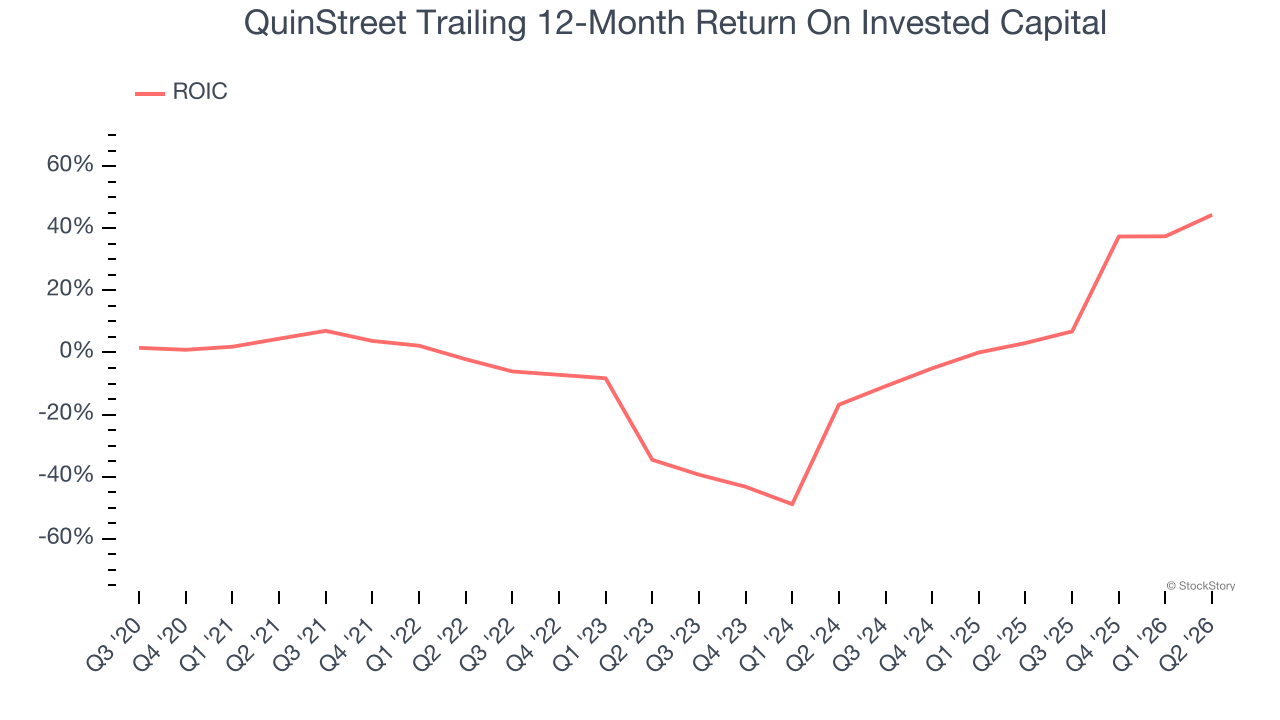
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, QuinStreet’s ROIC has increased. This is a good sign, but we recognize its lack of profitable growth during the COVID era was the primary reason for the change.
Final Judgment
These are just a few reasons why QuinStreet is a cream-of-the-crop business services company, and after the recent surge, the stock trades at 11.6× forward P/E (or $18.37 per share). Is now a good time to buy despite the apparent froth? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than QuinStreet
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.