Marqeta currently trades at $16.09 per share and has shown little upside over the past six months, posting a middling return of 1.3%. The stock also fell short of the S&P 500’s 13.7% gain during that period.
Is there a buying opportunity in Marqeta, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Marqeta Not Exciting?
We’re passing on Marqeta for now. Here are three reasons why there are better opportunities than MQ, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
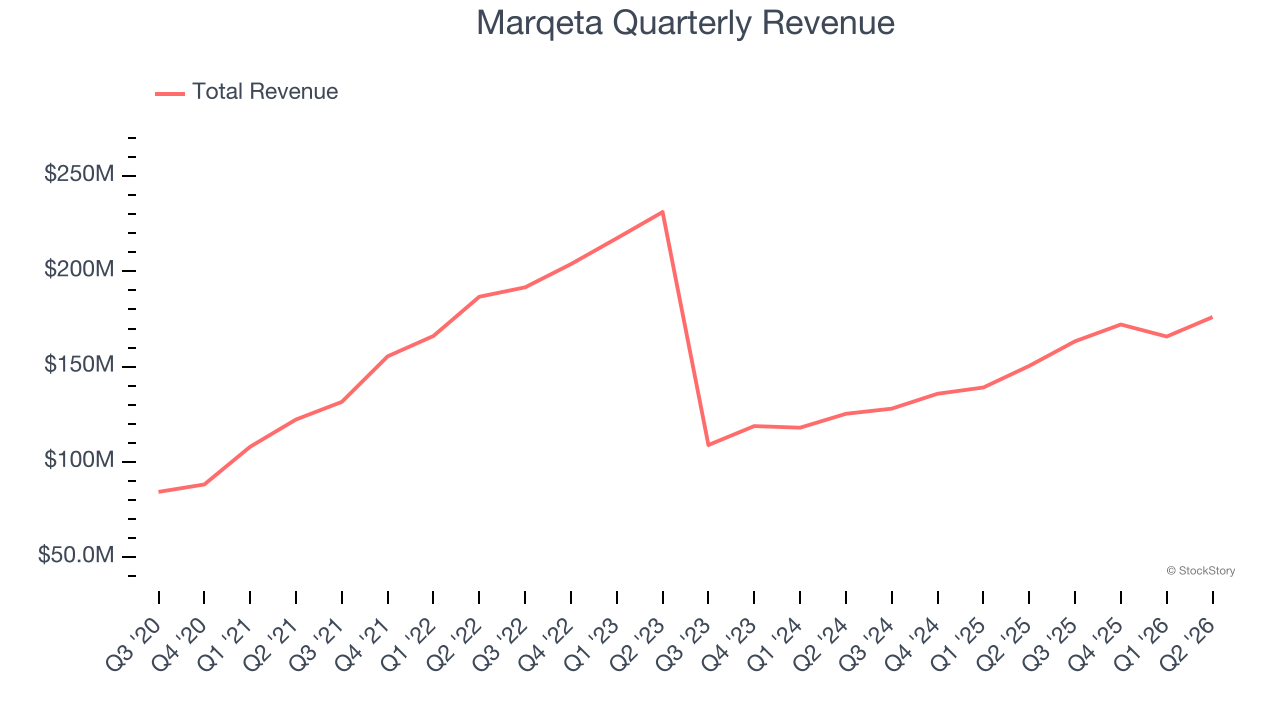
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, Marqeta grew its sales at a 11% annual rate. Although this growth is acceptable on an absolute basis, it fell short of our standards for the software sector, which enjoys a number of secular tailwinds.
2. Long Payback Periods Delay Returns
The customer acquisition cost (CAC) payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
Marqeta’s recent customer acquisition efforts haven’t yielded returns as its CAC payback period was negative this quarter, meaning its incremental sales and marketing investments outpaced its revenue. The company’s inefficiency indicates it operates in a competitive market and must continue investing to grow.
3. Cash Flow Margin Set to Decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict Marqeta’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 24.7% for the last 12 months will decrease to 25.4%.
Final Judgment
Marqeta’s business quality ultimately falls short of our standards. With its shares underperforming the market lately, the stock trades at 2.4× forward price-to-sales (or $16.09 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better stocks to buy right now. Let us point you toward the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.