Zillow’s stock price has taken a beating over the past six months, shedding 21.5% of its value and falling to $33.17 per share. This might have investors contemplating their next move.
Is now the time to buy Zillow, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Zillow Will Underperform?
Even with the cheaper entry price, we’re cautious about Zillow. Here are three reasons you should be careful with ZG, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
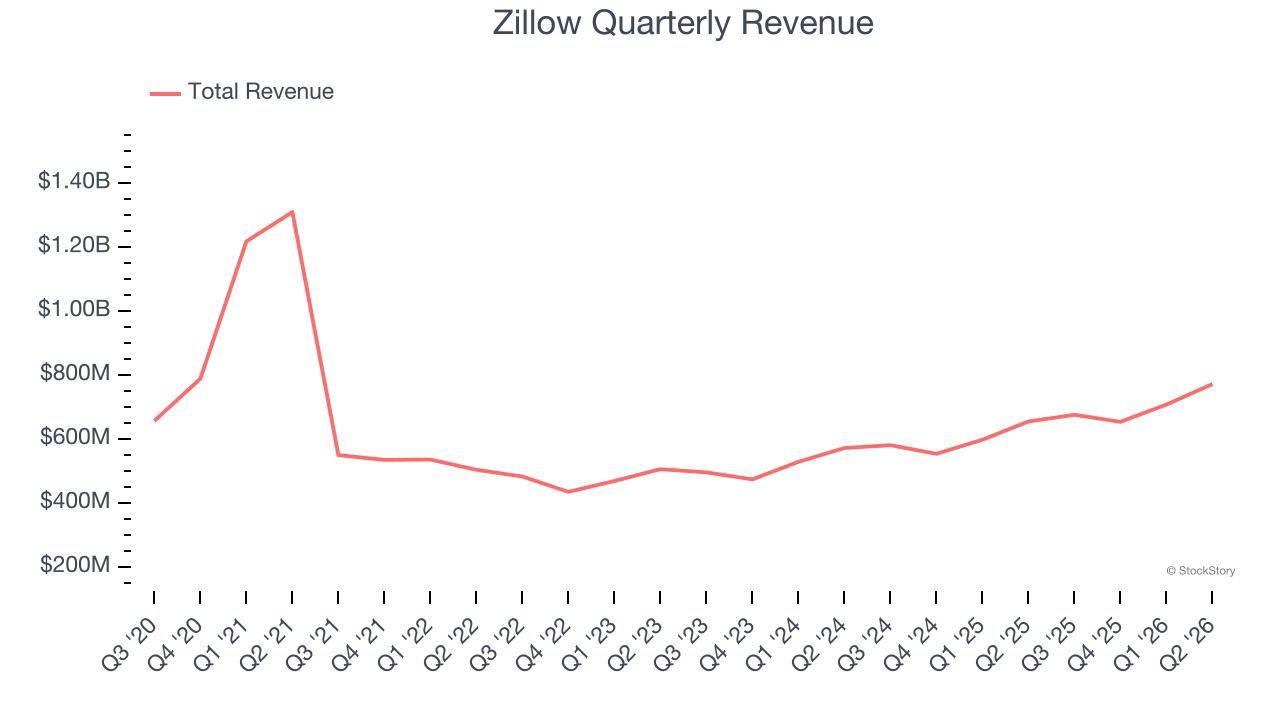
A company’s long-term sales performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Zillow’s demand was weak over the last five years as its sales fell at a 6.7% annual rate. This wasn’t a great result and signals it’s a low quality business.
2. EPS Barely Growing
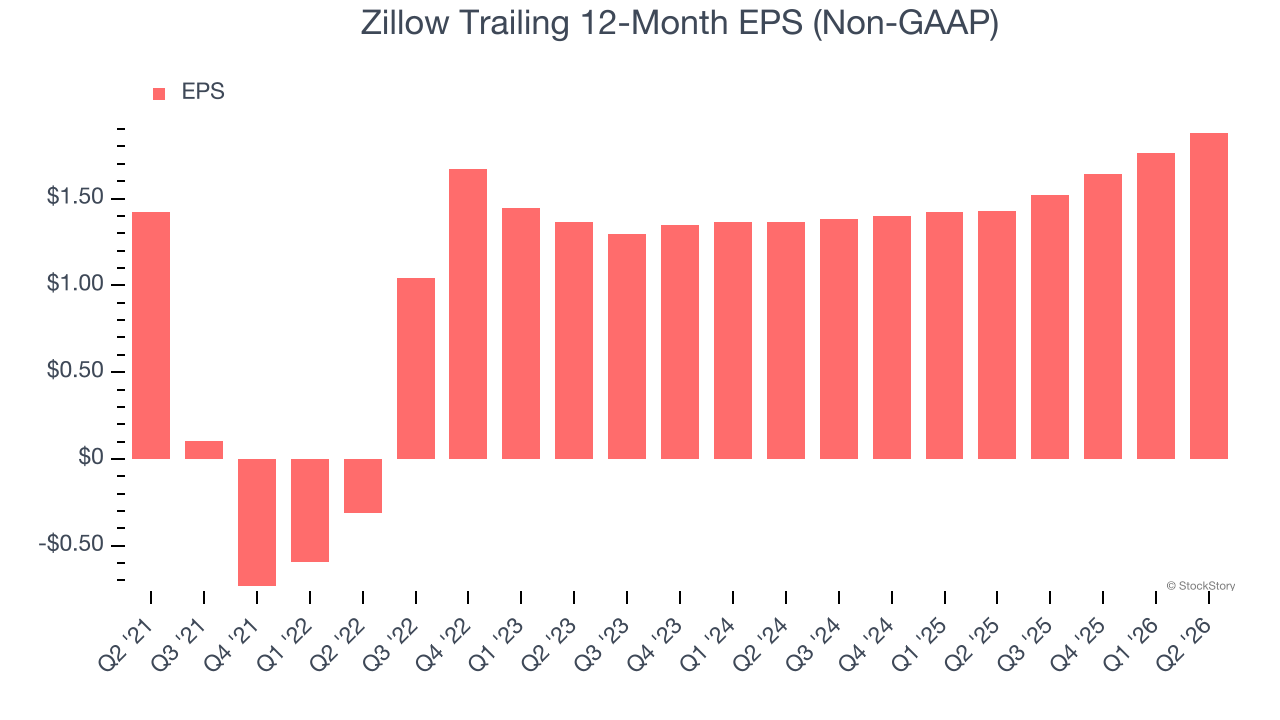
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Zillow’s EPS grew at 5.8% compounded annual growth rate over the last five years. On the bright side, this performance was better than its 6.7% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
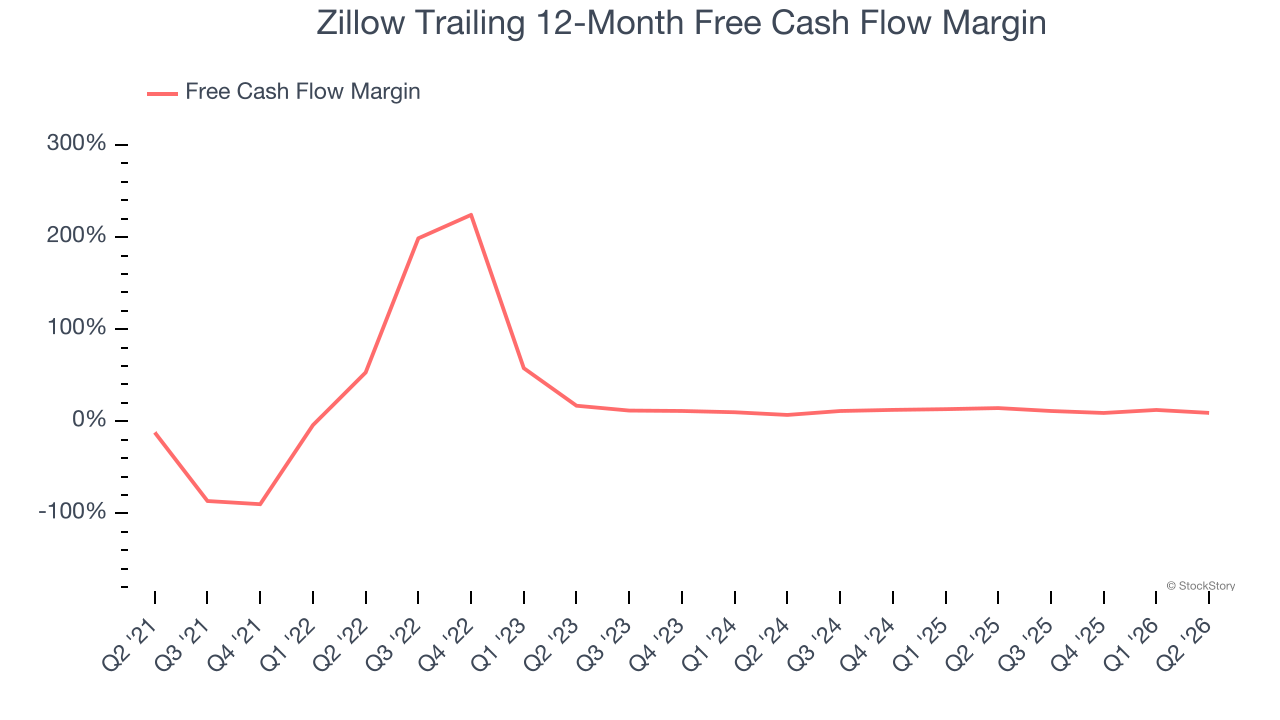
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Zillow has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 11.6%, below what we’d expect for a consumer discretionary business.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Zillow, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 13.2× forward P/E (or $33.17 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are better investments elsewhere. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.